
Biotech company 10x Genomics (NASDAQ: TXG) reported Q3 2026 results topping the market’s revenue expectations, with revenue up 1.1% year on year to $150.7 million. The company’s full-year revenue guidance of $630 million at the midpoint came in 1.5% above analysts’ consensus estimates. Its GAAP loss of $0.15 per share was 42.8% above analysts’ consensus estimates.
For more on 10x Genomics, read our full research report for free.
10x Genomics (TXG) Q3 2026 highlights:
- Revenue $150.7 million vs S&P analysts’ consensus estimates of $148 million (1.1% year-on-year growth, 1.8% beat)
- EPS (GAAP) -$0.15 vs analysts’ consensus estimates of -$0.26 (42.8% beat)
- Revenue guidance The company lifted its revenue guidance for the full year to $630 million at the midpoint from $620 million, a 1.6% increase
- Operating margin -10.7%, up from -21.6% in the same quarter last year
- Market capitalization $8.80 billion
"The biggest highlight of the quarter was the start of commercial shipments of Atera. Enthusiasm for the platform has continued to build, and we are incredibly excited to be putting instruments in customers' hands. We were also encouraged with the results across our broader business, driven by continued strength in consumables," said Serge Saxonov, co-founder and CEO of 10x Genomics. "As biology is entering a new era of AI and data maximalism, 10x is positioned incredibly well to benefit and to be the key enabler of progress going forward."
Revenue growth
A company’s long-term revenue performance is one signal of its overall quality. Any business can have short-term success, but a top-tier one grows for years. 10x Genomics’s revenue grew at a mediocre 6.1% compounded annual growth rate over the last five years, falling short of our benchmark for the healthcare sector.
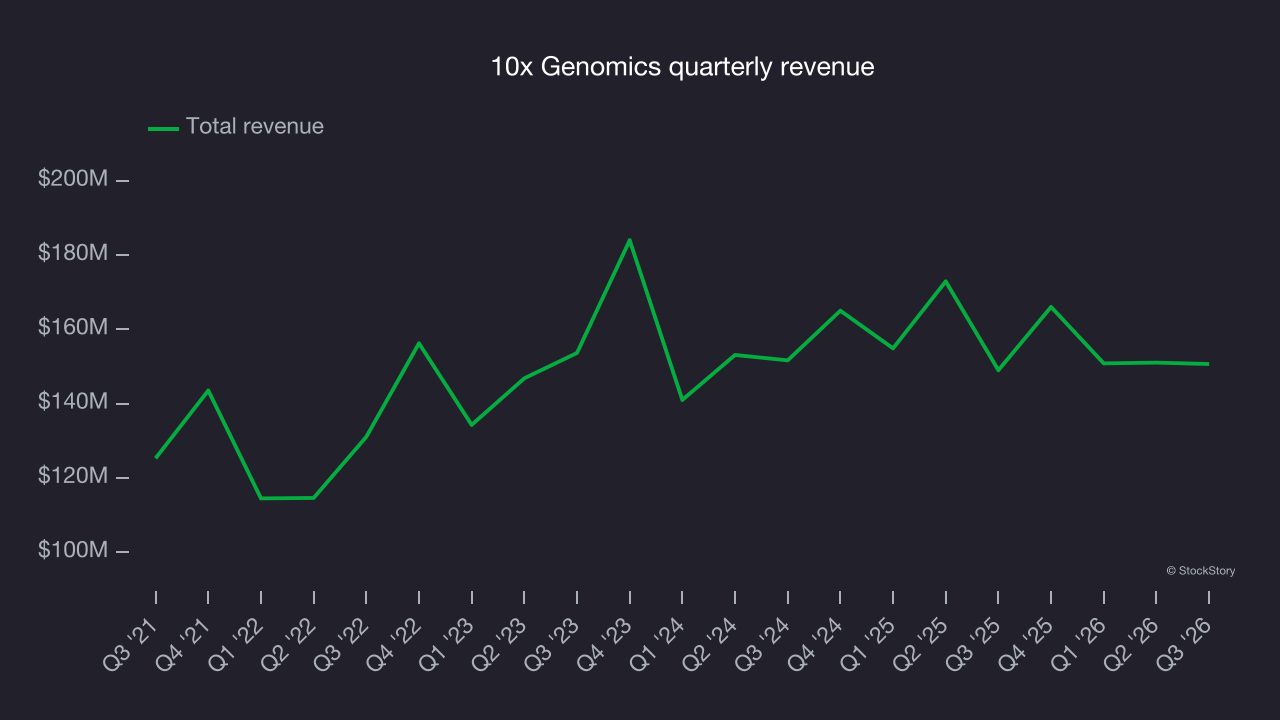
Long-term growth matters most, but within healthcare, a half-decade historical view may miss recent innovations or disruptive industry trends. 10x Genomics’s recent performance shows its demand has slowed as its revenue was flat over the last two years. 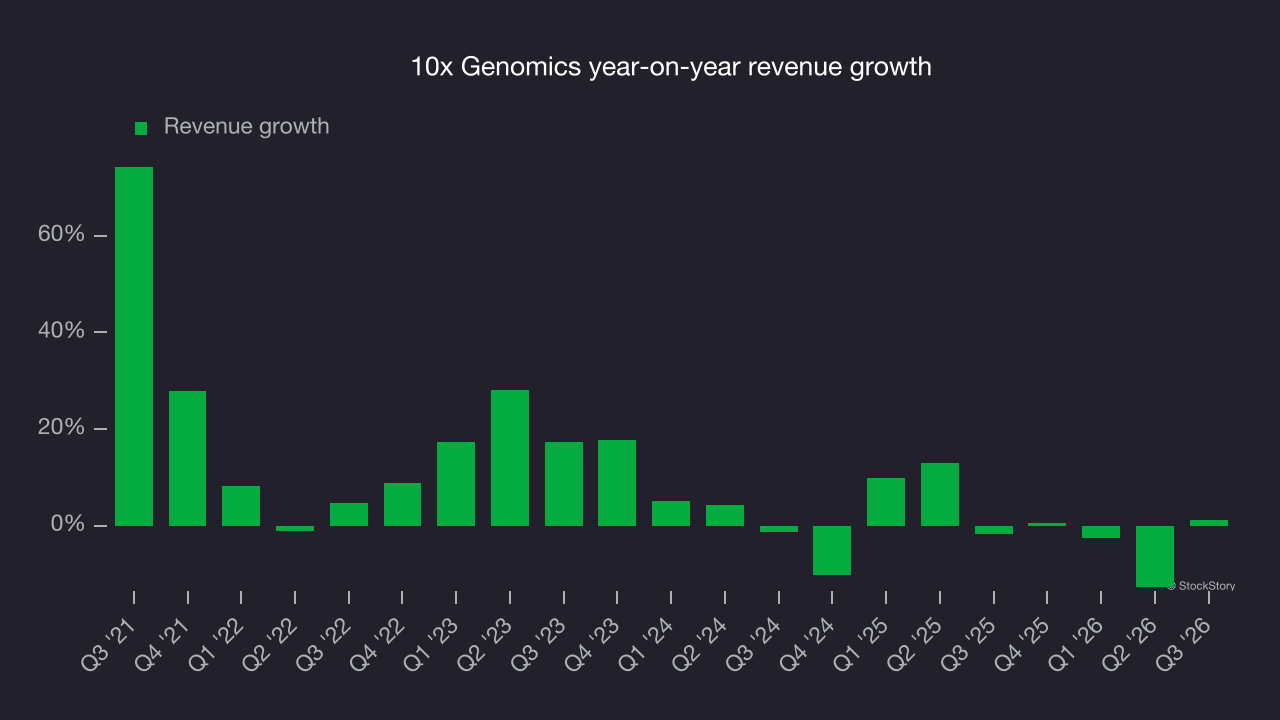
10x Genomics also breaks out the revenue for its most important segment, Consumables. Over the last two years, 10x Genomics’s Consumables revenue (recurring orders) averaged 9.5% year-on-year growth. This segment has outperformed its total revenue during the same period, lifting the company’s performance. 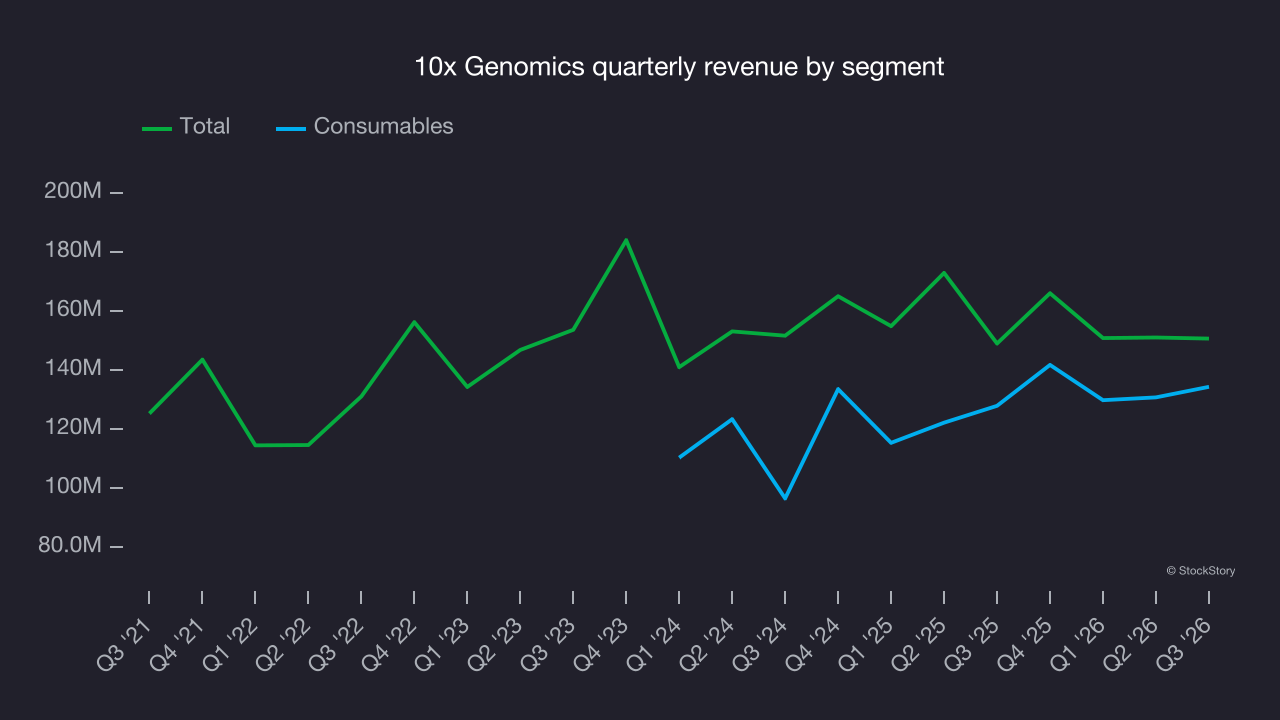
This quarter, 10x Genomics reported modest year-on-year revenue growth of 1.1% but beat Wall Street’s consensus estimates by 1.8%.
Looking ahead, sell-side analysts expect revenue to grow 7.7% over the next 12 months, according to S&P, an improvement versus the last two years. This projection is above average for the sector and implies its newer products and services will catalyze better top-line performance.
Adjusted operating margin
Adjusted operating margin is one of the best measures of profitability because it shows how much a company earns after subtracting all core expenses, like marketing and research and development. It also removes various one-time costs to give a clearer picture of normalized profits.
Although 10x Genomics was profitable this quarter from an operational perspective, it has generally struggled over a longer time period. Its expensive cost structure has contributed to an average adjusted operating margin of negative 3.5% over the last five years. Unprofitable healthcare companies require extra attention because they could be vulnerable in a downturn. That raises doubts about whether the business can endure a full cycle.
On the positive side, 10x Genomics’s adjusted operating margin rose by 11.5 percentage points over the last five years, as its revenue growth gave it operating leverage. The company’s two-year trajectory shows its performance was mostly driven by its recent improvements.
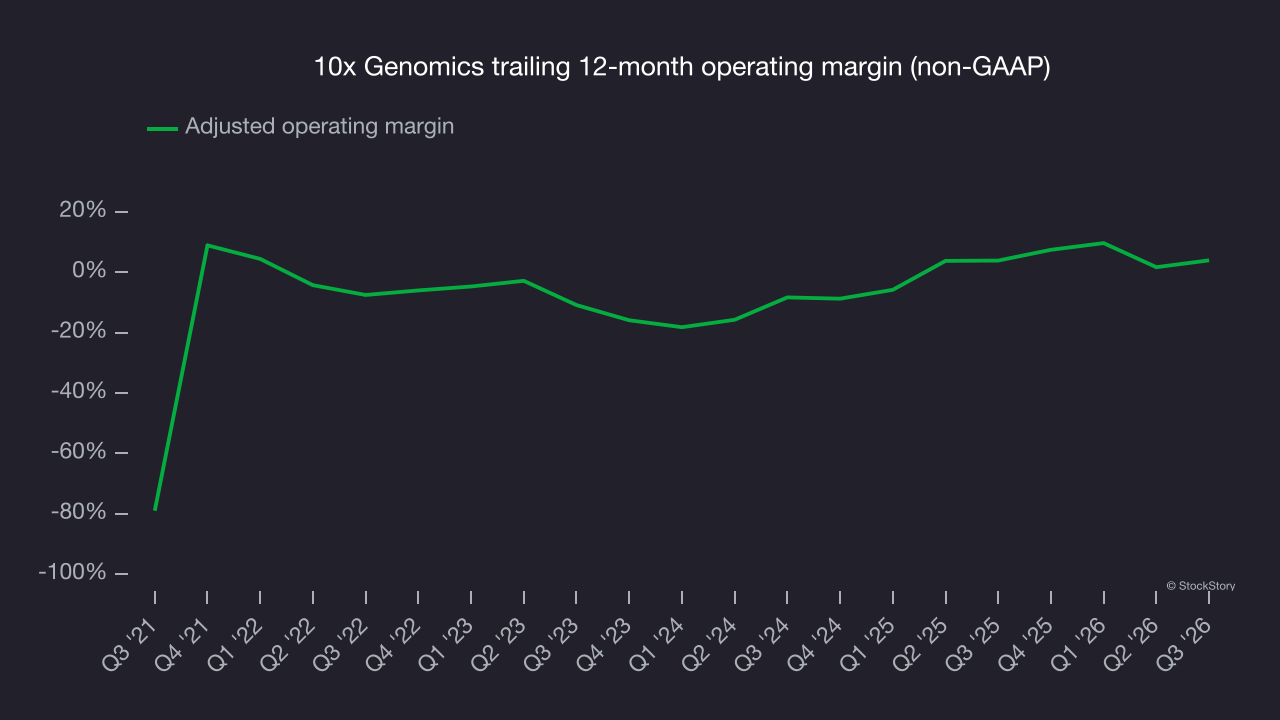
In Q3, 10x Genomics generated an adjusted operating margin of 4.7%, up 9.4 percentage points year on year. This improvement shows it was more efficient.
Earnings per share
Revenue trends explain a company’s historical growth, but the long-term change in earnings per share (EPS) points to the profitability of that growth – for example, a company could inflate its revenue through excessive spending on advertising and promotions.
Although 10x Genomics’s full-year earnings are still negative, it reduced its losses and improved its EPS by 34.2% annually over the last five years. The next few quarters will be critical for assessing its long-term profitability.
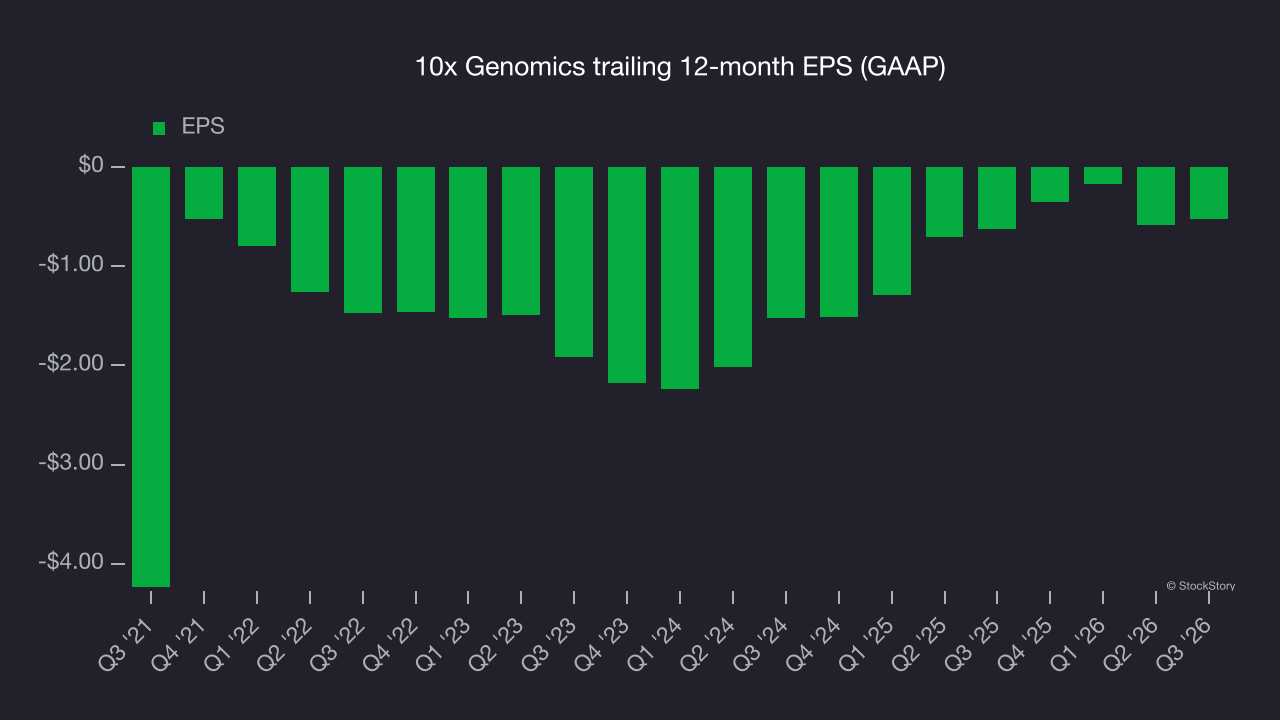
In Q3, 10x Genomics reported EPS of negative $0.15, up from negative $0.22 in the same quarter last year. The result comfortably beat analysts’ consensus estimates, a positive outcome for shareholders. Over the next 12 months, Wall Street expects 10x Genomics to perform poorly. Analysts forecast its full-year EPS will decline from negative $0.52 to negative $0.78, according to S&P.
Key takeaways from 10x Genomics’s Q3 results
10x Genomics delivered a solid quarter, with EPS beating analysts’ consensus estimates and full-year revenue guidance topping Wall Street’s consensus. But the market seemed to be hoping for more, and shares plunged 10% to $52.18 immediately after the release.
The latest quarter is only one piece of the longer-term business quality picture for 10x Genomics. Quality, combined with valuation, can help determine whether the stock is a buy. Read the full research report here (it’s free).




