Media, broadcasting and digital services company E.W. Scripps (NASDAQ: SSP) missed Wall Street’s revenue expectations in Q3 2026 as revenue rose 3.6% year on year to $544.9 million. Its GAAP profit of $0.21 per share was significantly above analysts’ consensus estimates.
For more on E.W. Scripps, read our free full research report.
E.W. Scripps (SSP) Q3 2026 highlights:
- Revenue $544.9 million vs S&P analysts’ consensus estimates of $547.8 million (3.6% year-on-year growth, 0.5% miss)
- EPS (GAAP) $0.21 vs analysts’ consensus estimates of -$0.10 (significant beat)
- Adjusted EBITDA $121.5 million vs analysts’ consensus estimates of $115.2 million (22.3% margin, 5.5% beat)
- Operating margin 12.3%, up from 7.2% in the same quarter last year
- Free cash flow -$11.61 million, down from $6.38 million in the same quarter last year
- Market capitalization $266.9 million
“The work underway reflects our priorities to improve our earnings trajectory, strengthen the balance sheet and best serve American media consumers. At the same time, we continue to evaluate accretive M&A opportunities with discipline, focusing on transactions that enhance our financial position and strategic flexibility within our current balance sheet.”
Revenue growth
Examining a company’s long-term performance can provide clues about its quality. Any business can have short-term success, but a top-tier one grows for years. E.W. Scripps’s demand was weak over the last five years as its revenue fell at a 1.3% annual rate. That outcome suggests poor business quality.
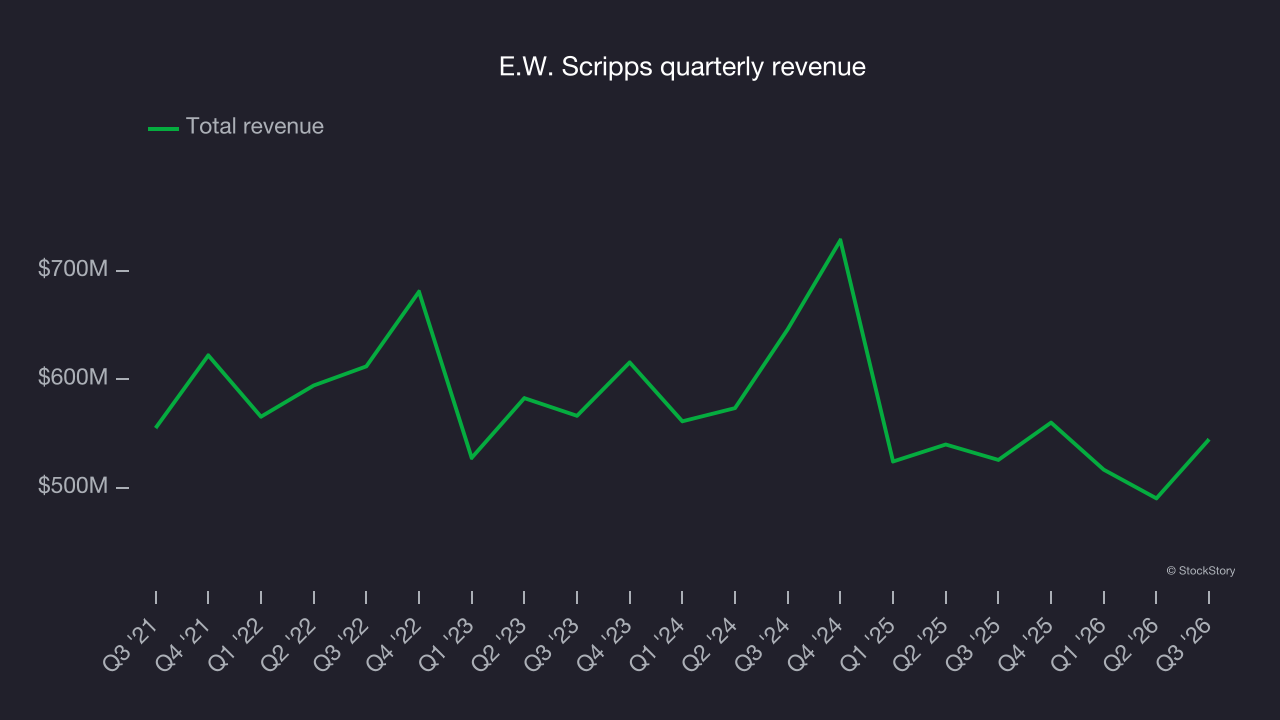
Long-term growth is the most important, but within consumer discretionary, product cycles are short and revenue can be hit-driven due to rapidly changing trends and consumer preferences. E.W. Scripps’s recent performance shows its demand remained suppressed as its revenue has declined by 6.1% annually over the last two years.
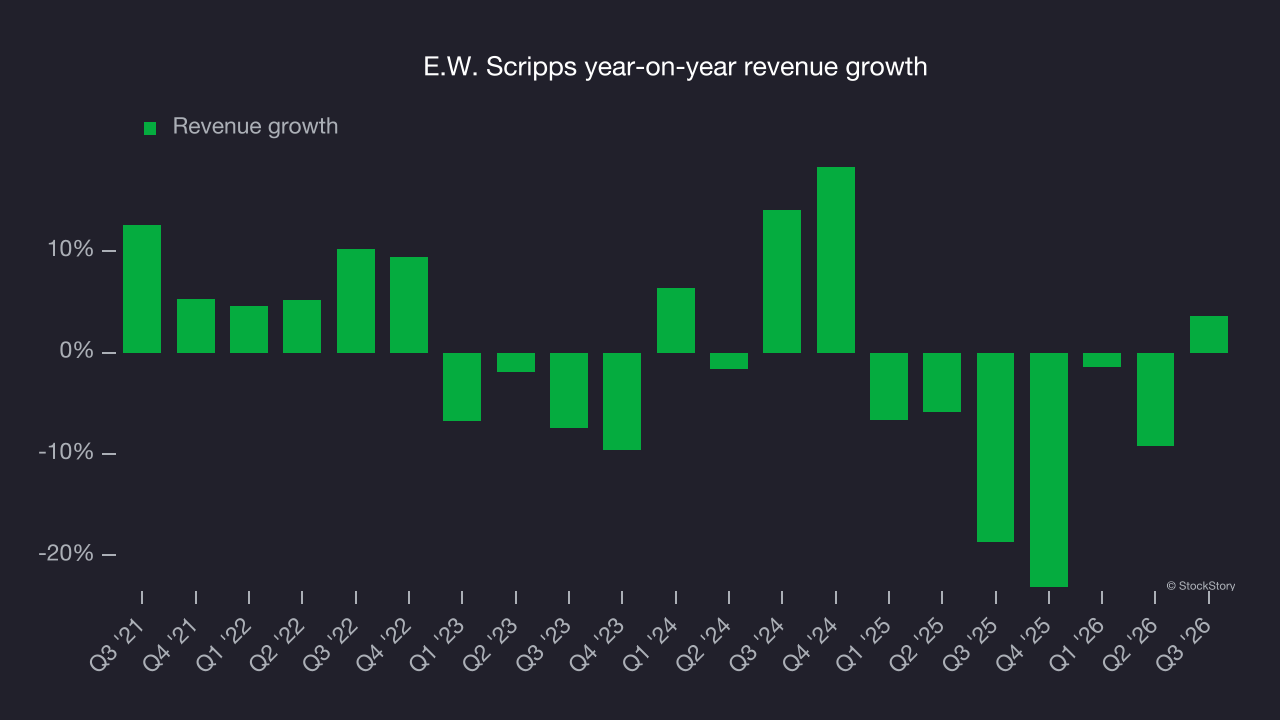
This quarter, E.W. Scripps’s revenue grew by 3.6% year on year to $544.9 million, falling short of Wall Street’s consensus estimates.
Looking ahead, sell-side analysts expect revenue to decline by 1.8% over the next 12 months, according to S&P. Although this projection is better than its two-year trend, the company’s demand difficulties remain a concern.
Operating margin
Operating margin is an important measure of profitability as it shows the portion of revenue left after accounting for all core expenses, from the cost of goods sold to advertising and wages. It’s also useful for comparing profitability across companies with different levels of debt and tax rates because it excludes interest and taxes.
E.W. Scripps’s operating margin has shrunk over the last 12 months and averaged negative 15.6% over the last two years. Unprofitable consumer discretionary companies with falling margins deserve extra scrutiny because they’re spending heavily to stay relevant, an unsustainable practice.
This quarter, E.W. Scripps generated an operating margin of 12.3%, up 5.2 percentage points year on year. The increase was a positive sign of improved efficiency.
Earnings per share
We track the long-term change in earnings per share (EPS) for the same reason as long-term revenue growth. Compared to revenue, however, EPS highlights whether a company’s growth is profitable.
E.W. Scripps’ EPS declined by 42.9% annually over the last five years, more than its revenue. This indicates the company struggled because its fixed cost base made it difficult to adjust to shrinking demand.
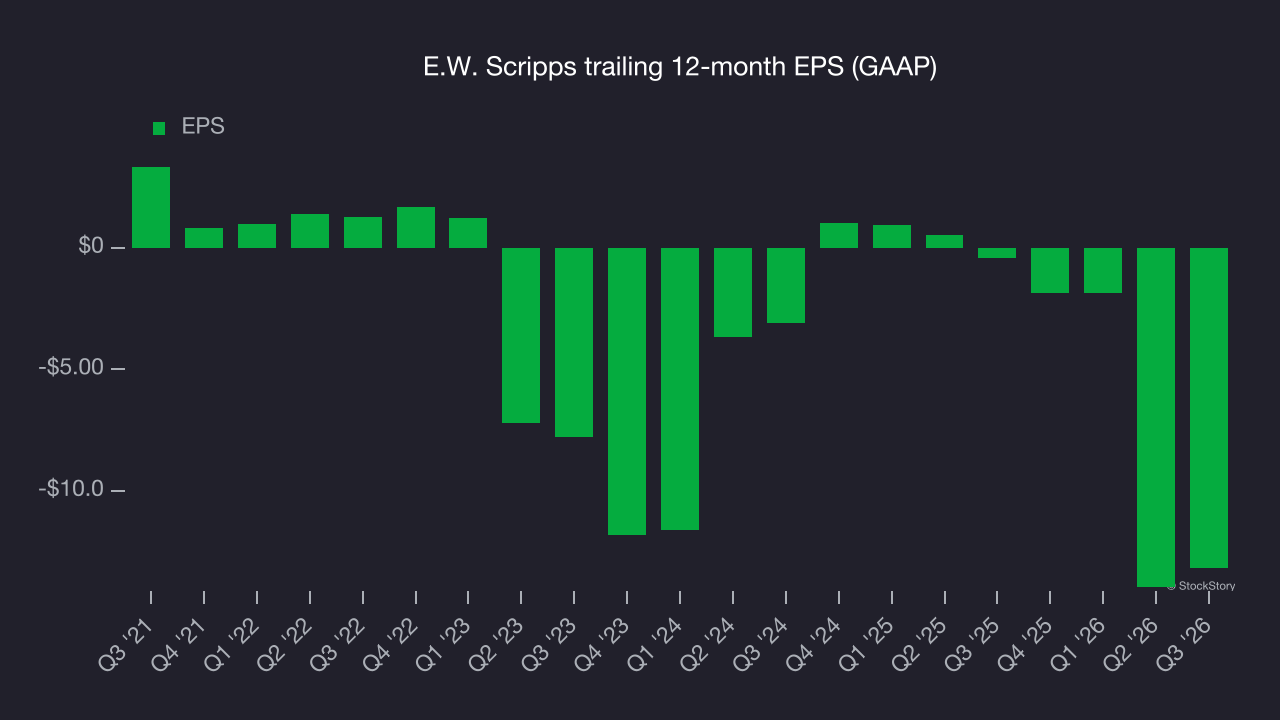
In Q3, E.W. Scripps reported EPS of $0.21, up from negative $0.55 in the same quarter last year. EPS came in well above analysts’ consensus estimates. Over the next 12 months, Wall Street expects E.W. Scripps to narrow its losses. Analysts forecast its full-year EPS will improve from negative $13.18 to negative $0.61, according to S&P.
Key takeaways from E.W. Scripps’s Q3 results
E.W. Scripps delivered a solid Q3, with EPS and EBITDA both topping analysts’ consensus estimates. Revenue, however, came in slightly below expectations. Shares surged 6.4% to $2.95 immediately after the results.
E.W. Scripps had a solid quarter, but one earnings result doesn’t necessarily make the stock a buy. What happened in the latest quarter matters, but not as much as longer-term business quality and valuation when deciding whether to invest in this stock. For more on those factors, read our full research report here (it’s free).