
Pop culture collectibles manufacturer Funko (NASDAQ: FNKO) reported revenue ahead of Wall Street’s expectations in Q3 2026, with revenue up 3% year on year to $258.3 million. Its non-GAAP profit of $0.16 per share was 60% above analysts’ consensus estimates.
For more on Funko, read our free full research report.
Funko (FNKO) Q3 2026 highlights:
- Revenue $258.3 million vs S&P analysts’ consensus estimates of $249.6 million (3% year-on-year growth, 3.5% beat)
- Adjusted EPS $0.16 vs S&P analysts’ consensus estimates of $0.10 (60% beat)
- Adjusted EBITDA $32.14 million vs analysts’ consensus estimates of $26.83 million (12.4% margin, 19.8% beat)
- EBITDA guidance $105 million at the midpoint for the full year, below analysts’ consensus estimates of $112.3 million
- Operating margin 5.8%, up from 2.6% in the same quarter last year
- Free cash flow margin 9.6%, up from 1.6% in the same quarter last year
- Market capitalization $367.3 million
Revenue growth
A company’s long-term revenue performance is one signal of its overall quality. Any business can have short-term success, but a top-tier one grows for years. Funko struggled to consistently increase demand as its $940.1 million in revenue for the trailing 12 months was close to its revenue five years ago. This was below our standards and is a sign of poor business quality.
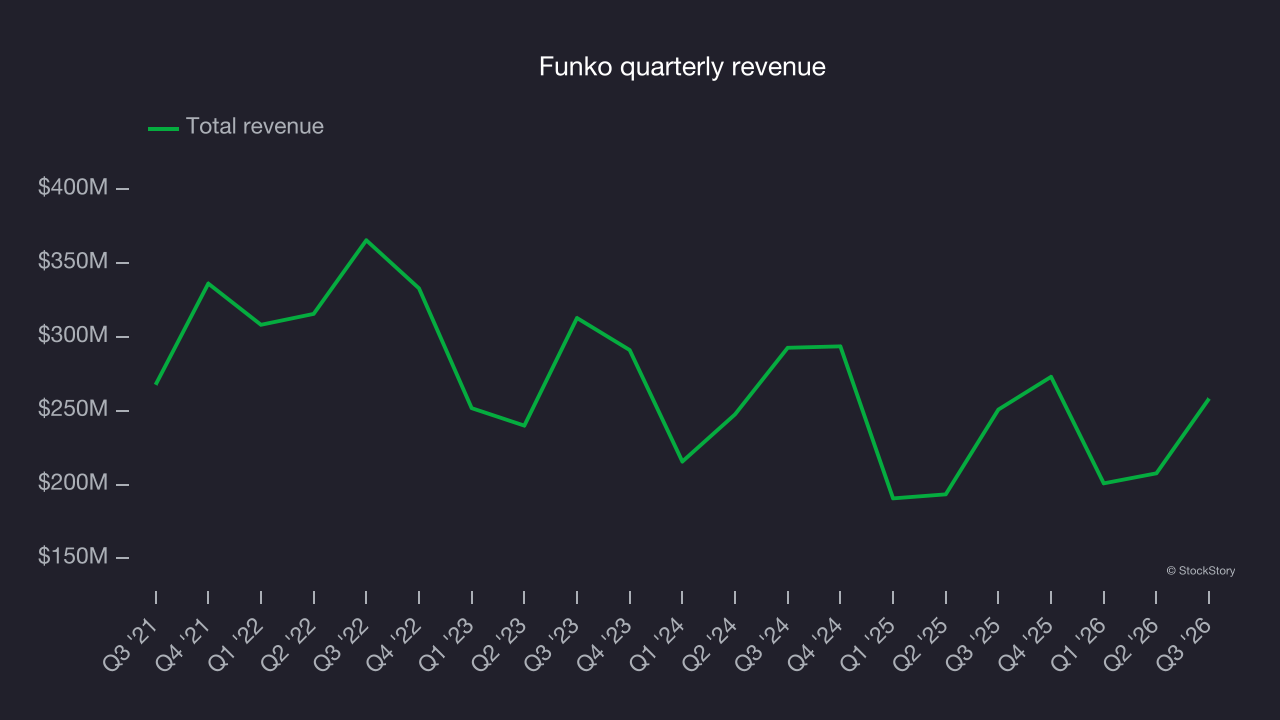
Long-term growth is the most important, but within consumer discretionary, product cycles are short and revenue can be hit-driven due to rapidly changing trends and consumer preferences. Funko’s recent performance shows its demand remained suppressed as its revenue has declined by 5.3% annually over the last two years. 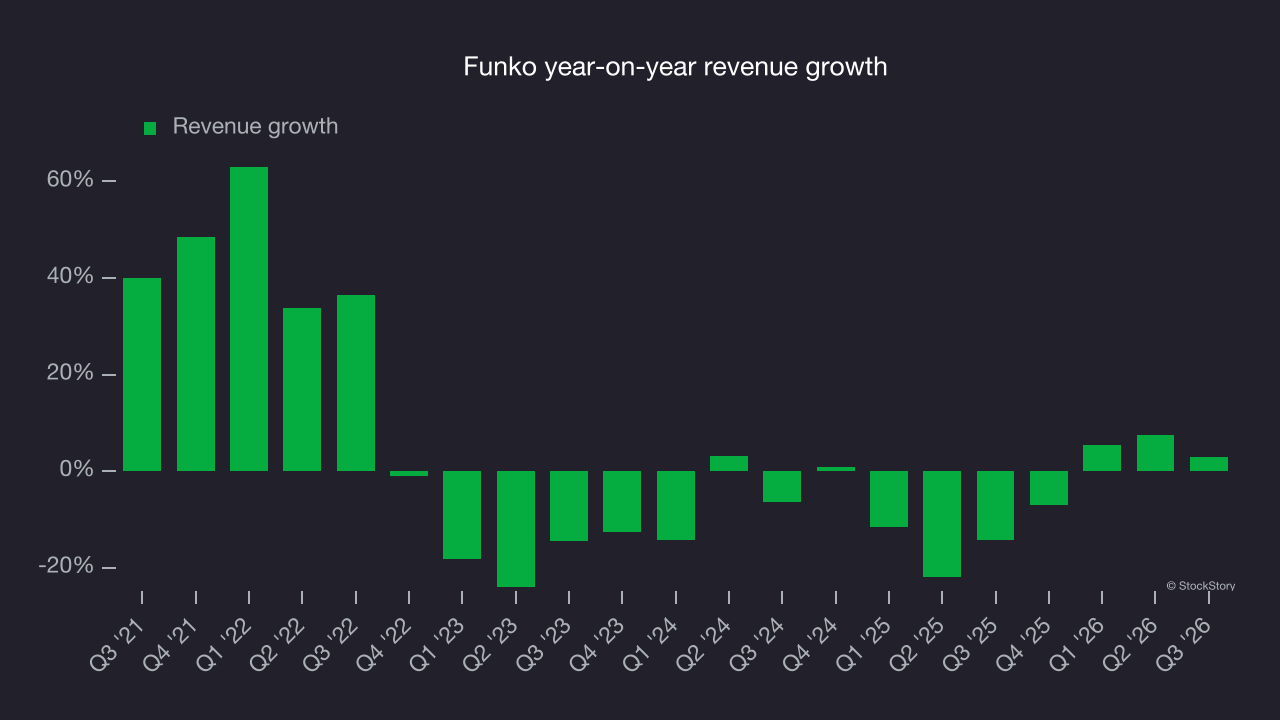
This quarter, Funko reported modest year-on-year revenue growth of 3% but beat Wall Street’s consensus estimates by 3.5%.
Looking ahead, sell-side analysts expect revenue to grow 3.8% over the next 12 months, according to S&P. While this projection indicates its newer products and services will fuel better top-line performance, it is still below the sector average.
Operating margin
Operating margin is an important measure of profitability as it shows the portion of revenue left after accounting for all core expenses, from the cost of goods sold to advertising and wages. It’s also useful for comparing profitability across companies with different levels of debt and tax rates because it excludes interest and taxes.
Funko’s operating margin has been trending up over the last 12 months, leading to break-even results over the last two years. However, its large expense base and inefficient cost structure mean it still has inadequate profitability for a consumer discretionary business.
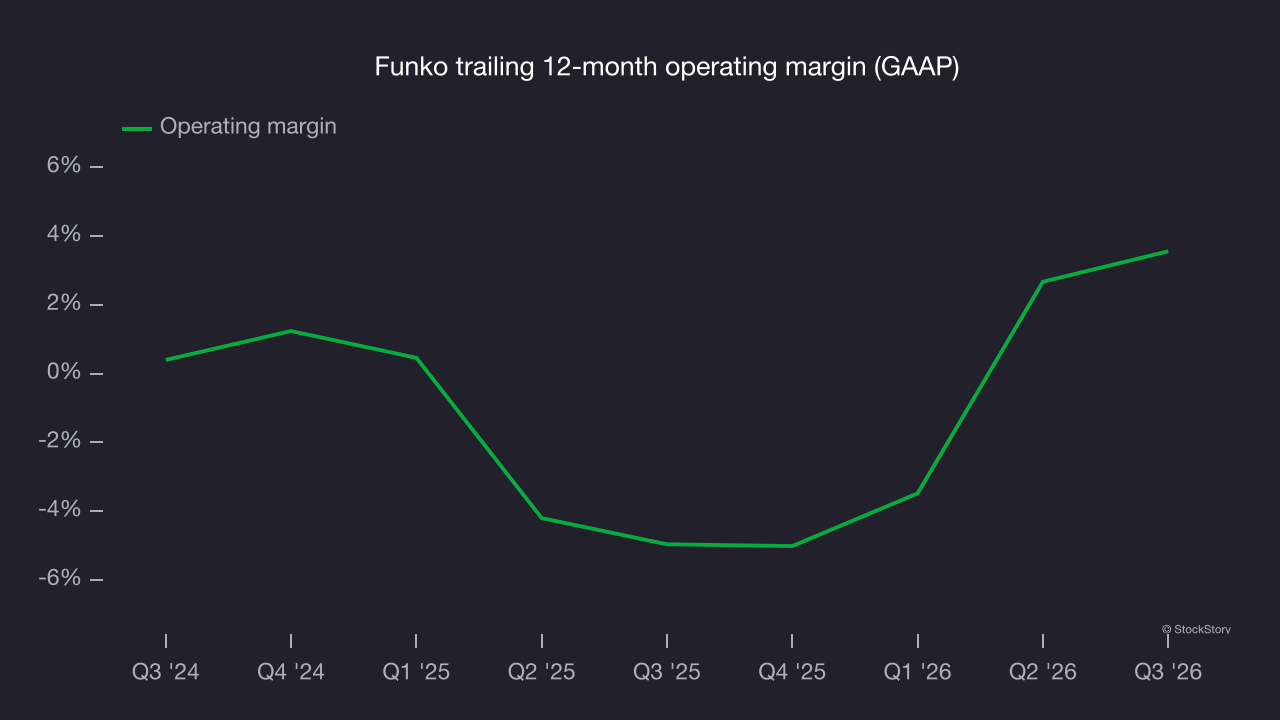
This quarter, Funko generated an operating margin of 5.8%, up 3.2 percentage points year on year. This increase was a positive development, reflecting greater efficiency.
Earnings per share
Long-term changes in earnings per share, or EPS, are worth tracking for the same reason as long-term revenue growth. Compared to revenue, however, EPS highlights whether a company’s growth is profitable.
Funko’s EPS declined by 22.9% annually over the last five years while its revenue was flat. This indicates the company struggled because its fixed cost base made it difficult to adjust to choppy demand.
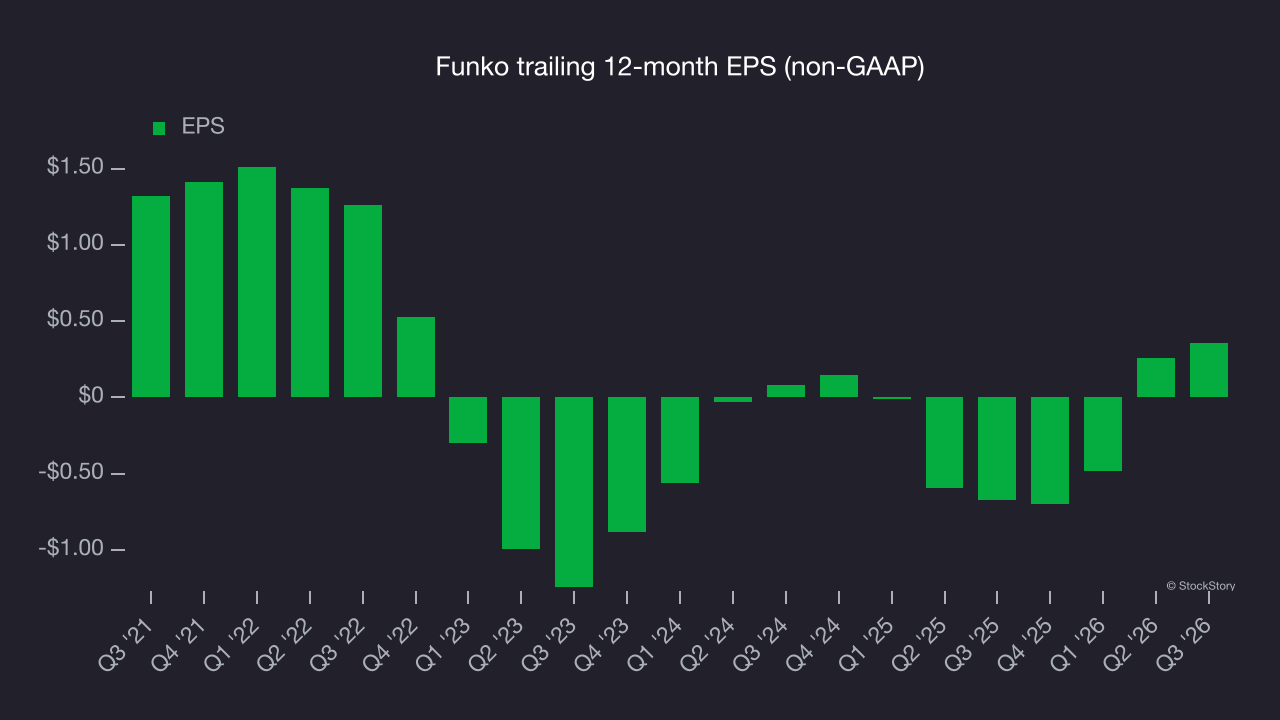
In Q3, Funko reported adjusted EPS of $0.16, up from $0.06 in the same quarter last year. This result easily beat analysts’ consensus estimates. Over the next 12 months, Wall Street expects Funko’s full-year EPS to grow 19.4% from $0.36 to $0.43, according to S&P.
Key takeaways from Funko’s Q3 results
Funko’s quarter had some key positives, with EPS and EBITDA both topping analysts’ consensus estimates. But its full-year EBITDA guidance fell short of expectations. Investors were likely hoping for more: Shares plunged 11.4% to $5.43 immediately after the results.
Should you invest in Funko? The latest quarter matters, but longer-term business quality and valuation are more important when deciding whether to invest in the stock. Read the full research report here for more on Funko’s business quality and valuation (it’s free).




