Professional consulting firm ICF International (NASDAQ: ICFI) fell short of the market’s revenue expectations in Q3 2026 as revenue rose only 1.1% year on year to $470.5 million. Its non-GAAP profit of $1.98 per share was 2.9% above analysts’ consensus estimates.
For more on ICF International, read our free full research report.
ICF International (ICFI) Q3 2026 highlights:
- Revenue $470.5 million vs S&P analysts’ consensus estimates of $490.9 million (1.1% year-on-year growth, 4.2% miss)
- Adjusted EPS $1.98 vs S&P analysts’ consensus estimates of $1.92 (2.9% beat)
- Adjusted EBITDA $54.17 million vs analysts’ consensus estimates of $55.96 million (11.5% margin, 3.2% miss)
- Operating margin 9.3%, up from 8.3% in the same quarter last year
- Free cash flow margin 6.3%, down from 9% in the same quarter last year
- Backlog $3.5 billion at quarter end, in line with the same quarter last year
- Market capitalization $1.74 billion
Revenue growth
Reviewing a company’s long-term revenue performance reveals insights into its quality. Even a weak business can perform well for one or two quarters, but a high-quality one grows for years.
With $1.83 billion in revenue over the past 12 months, ICF International is a mid-sized business services company, which sometimes brings disadvantages compared to larger competitors benefiting from better economies of scale.
ICF International’s revenue grew at a sluggish 2.7% compounded annual growth rate over the last five years. This shows it failed to generate significant demand.
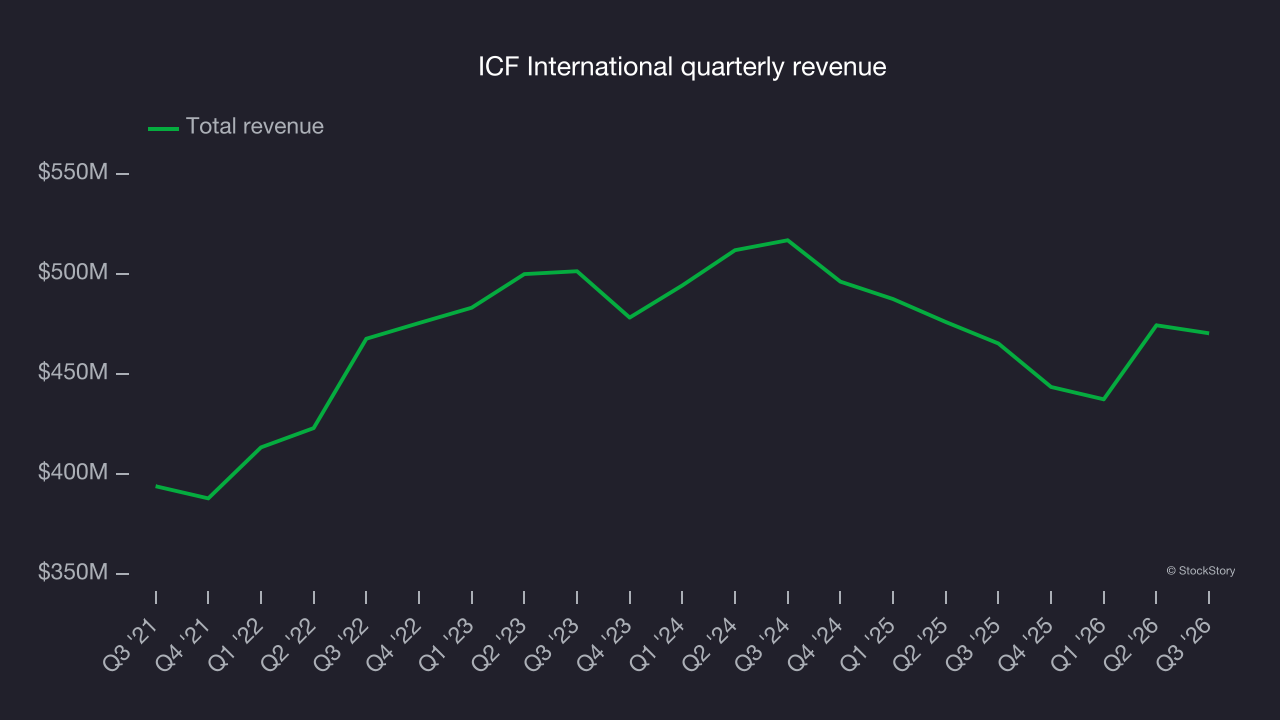
Long-term growth is the most important, but within business services, a half-decade historical view may miss new innovations or demand cycles. ICF International’s performance shows it grew in the past but relinquished its gains over the last two years, as its revenue fell by 4.5% annually. 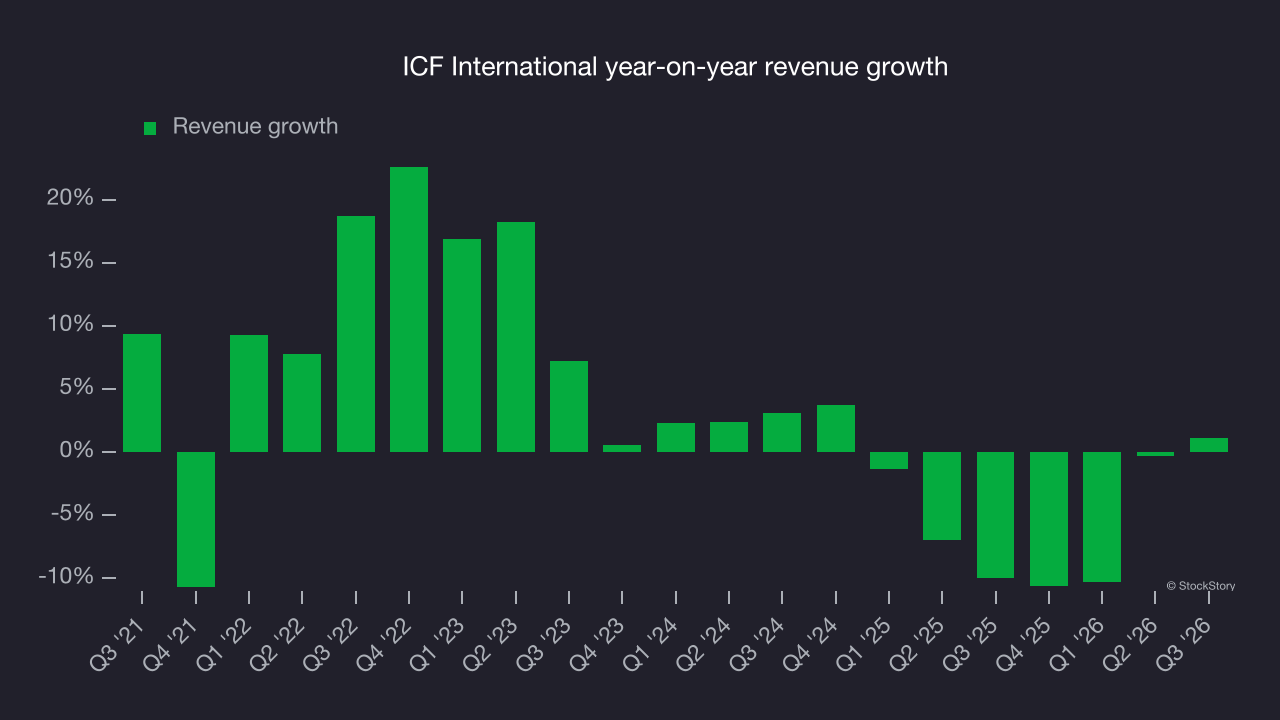
Analyzing the company’s backlog, or the value of its outstanding orders that have not yet been executed or delivered, helps explain its revenue dynamics. ICF International’s backlog reached $3.5 billion in the latest quarter and averaged 5% year-on-year declines over the last two years. This was in line with its revenue growth, indicating that the company effectively balanced its new order intake and fulfillment processes. 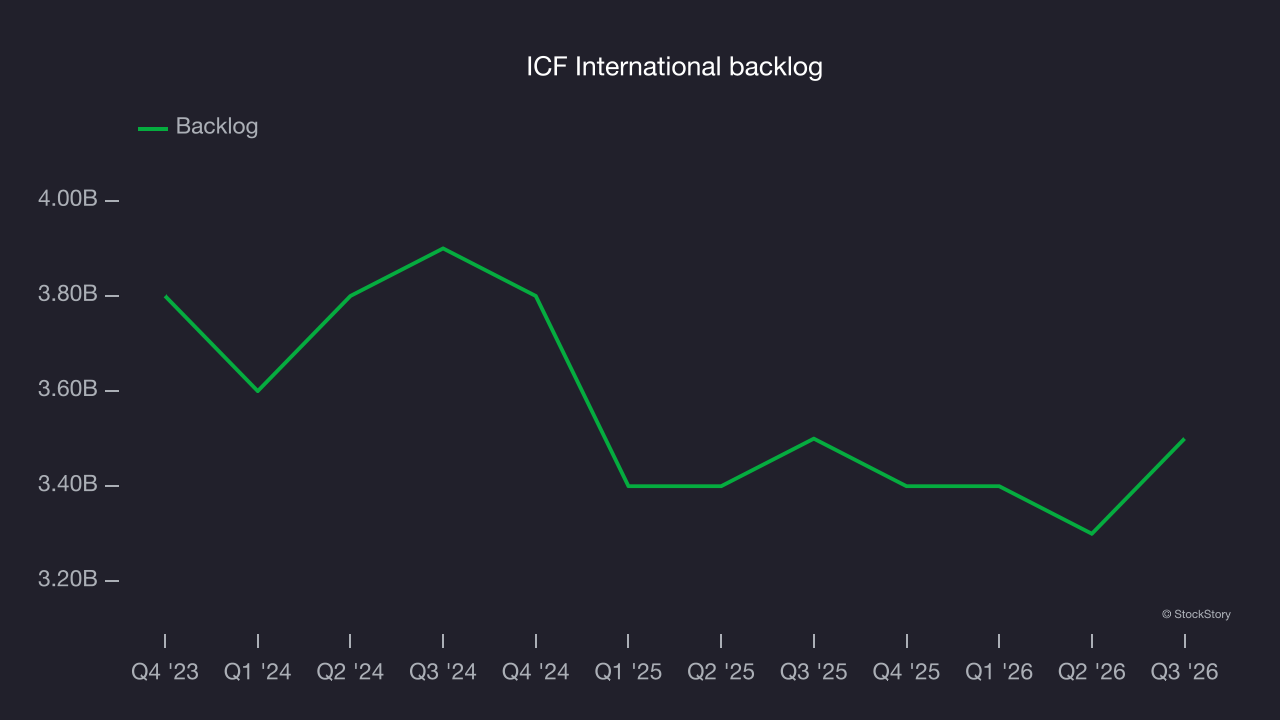
This quarter, ICF International’s revenue grew by 1.1% year on year to $470.5 million, falling short of Wall Street’s consensus estimates.
Looking ahead, sell-side analysts expect revenue to grow 9.6% over the next 12 months, according to S&P, an improvement versus the last two years. This projection is noteworthy and implies its newer products and services will drive better revenue performance.
Adjusted operating margin
ICF International’s adjusted operating margin has stayed roughly the same over the last 12 months, averaging 8.1% over the last five years. This mediocre profitability for a business services company reflected its suboptimal cost structure.
ICF International’s adjusted operating margin may have fluctuated slightly, but it has generally stayed the same over the last five years. This raises questions about the company’s expense base because its revenue growth should have given it leverage on its fixed costs, resulting in better economies of scale and profitability.
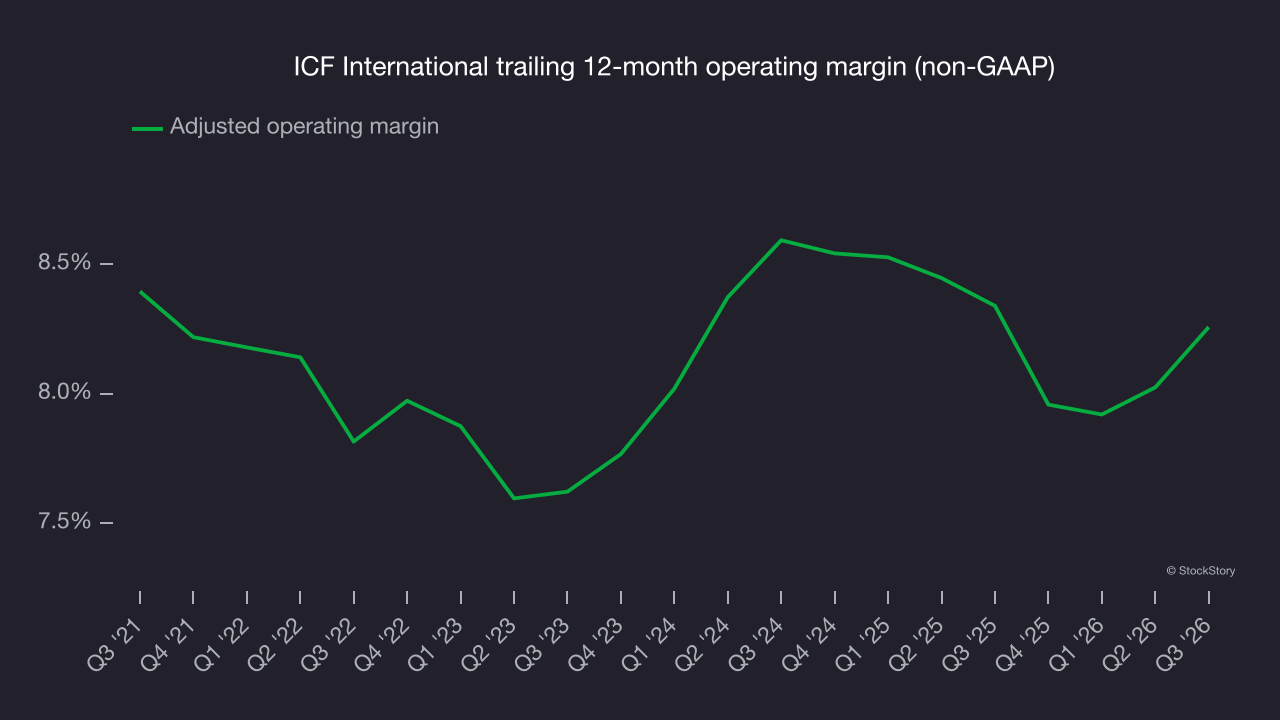
In Q3, ICF International generated an adjusted operating margin of 9.3%, in line with the same quarter last year. This indicates the company’s overall cost structure has been relatively stable.
Earnings per share
Long-term changes in earnings per share, or EPS, matter for the same reason as long-term revenue growth. Compared to revenue, however, EPS highlights whether a company’s growth is profitable.
ICF International’s EPS grew at a 6.4% compounded annual growth rate over the last five years. This performance was better than its revenue growth but reveals little about its business quality because its adjusted operating margin improvement lagged that of its peers.
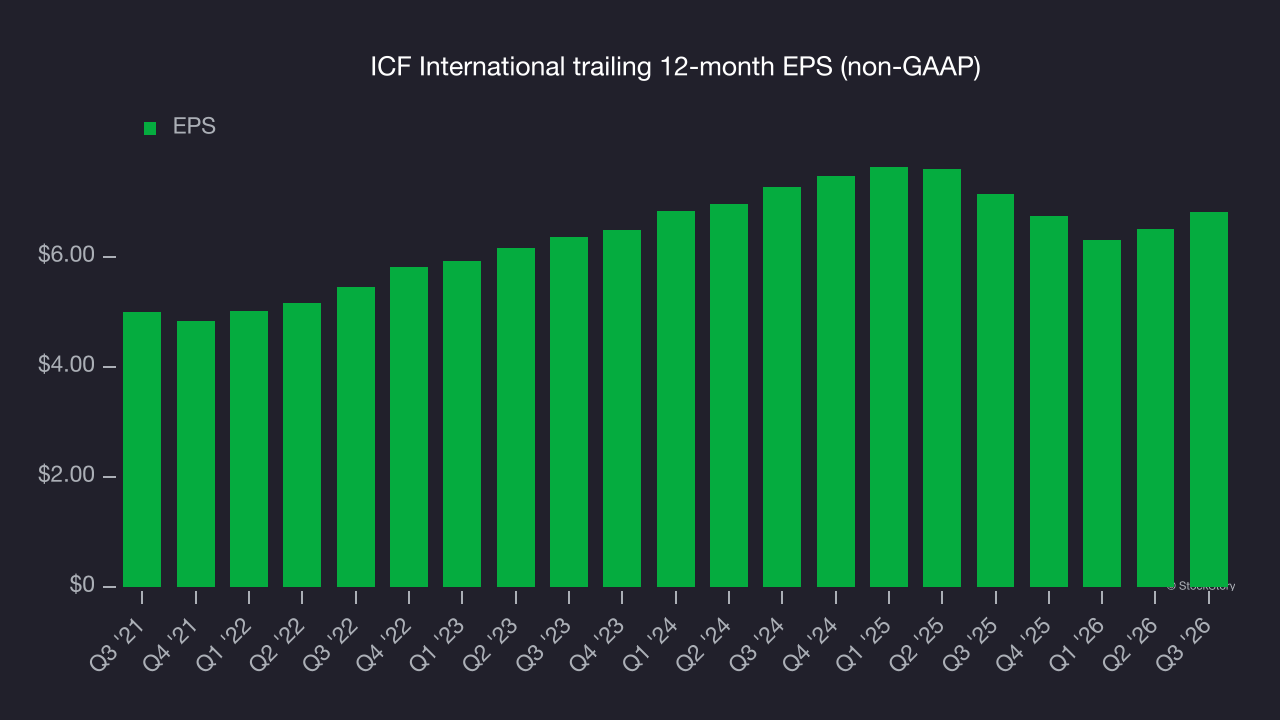
As with revenue, a shorter-term view of EPS can reveal changes in the business.
For ICF International, its two-year annual EPS declines of 3.2% show it’s continued to underperform. These were poor results.
In Q3, ICF International reported adjusted EPS of $1.98, up from $1.67 in the same quarter last year. This result beat analysts’ consensus estimates by 2.9%. Over the next 12 months, Wall Street expects ICF International’s full-year EPS to grow 11.5% from $6.81 to $7.60, according to S&P.
Key takeaways from ICF International’s Q3 results
ICF International’s Q3 results fell short overall: EPS beat analysts’ consensus estimates, but revenue missed. The quarter could have been better, and shares remained flat at $95.42 immediately after the release.
When deciding whether to buy the stock, consider the bigger picture of valuation, business quality and the latest earnings. Read the full research report here (it’s free).