Healthcare solutions provider Solventum (NYSE: SOLV) announced better-than-expected revenue in Q3 2026, but revenue fell by 7% year on year to $1.95 billion. Its non-GAAP profit of $1.45 per share was 7.9% above analysts’ consensus estimates.
For more on Solventum, read our full research report for free.
Solventum (SOLV) Q3 2026 highlights:
- Revenue $1.95 billion vs S&P analysts’ consensus estimates of $1.93 billion (7% year-on-year decline, 0.9% beat)
- Adjusted EPS $1.45 vs S&P analysts’ consensus estimates of $1.34 (7.9% beat)
- Adjusted EPS guidance Management raised its full-year adjusted EPS guidance to $7.25 at the midpoint, a 1.4% increase
- Operating margin 3.5%, down from 80.6% in the same quarter last year
- Free cash flow $97 million, up from -$21 million in the same quarter last year
- Organic revenue fell 2.8% year on year (miss)
- Market capitalization $15.21 billion
Revenue growth
A company’s long-term revenue performance can indicate its overall quality. Even a poor business can perform well for one or two quarters, but a high-quality one grows for years. Solventum struggled to consistently increase demand as its $8.16 billion in revenue for the trailing 12 months was close to its revenue four years ago. That underwhelming result suggests it is a low-quality business.
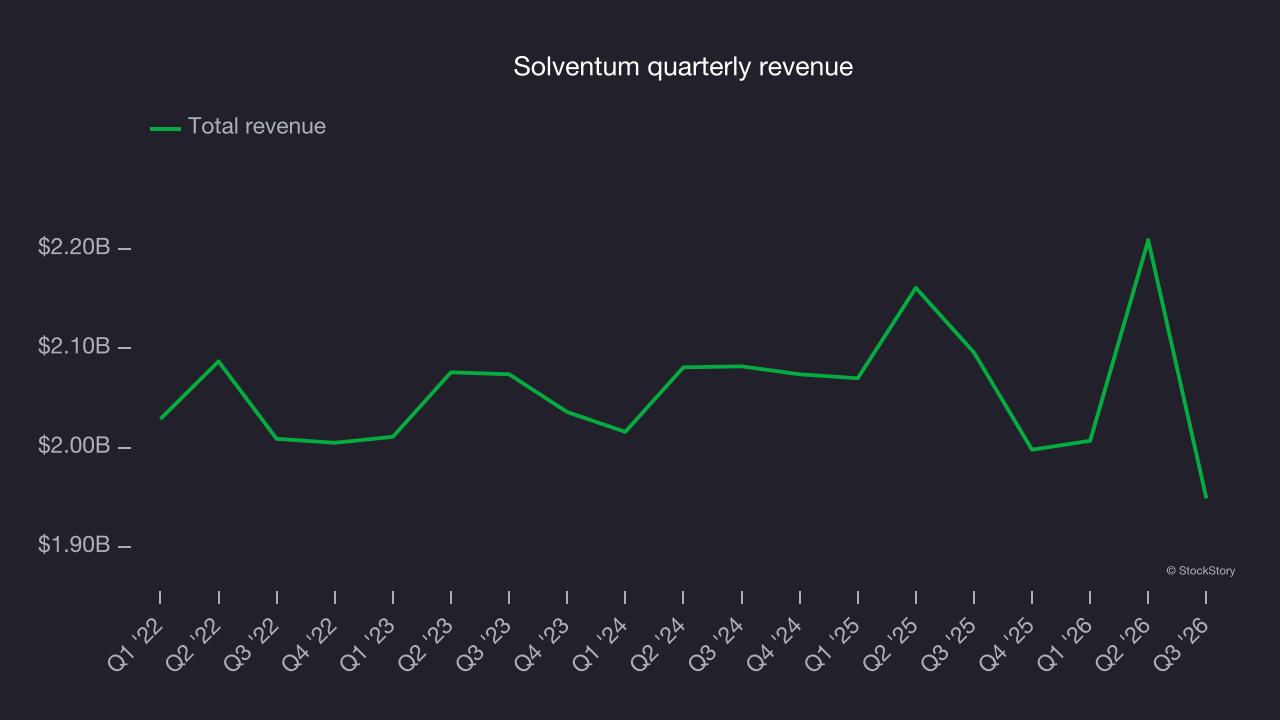
Long-term growth is the most important, but within healthcare, a stretched historical view may miss new innovations or demand cycles. Just like its four-year trend, Solventum’s revenue over the last two years was flat, suggesting it is in a slump. 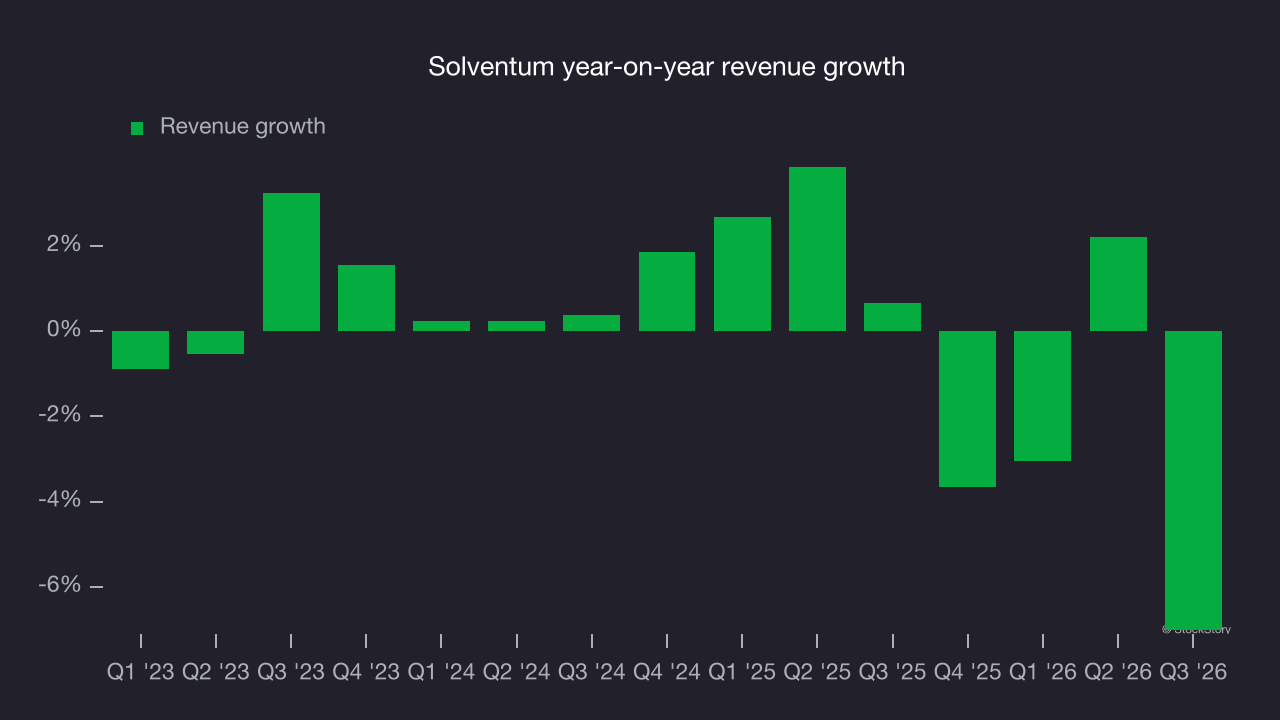
Solventum also reports organic revenue, which strips out one-time events like acquisitions and currency fluctuations that don’t accurately reflect its fundamentals. Over the last two years, Solventum’s organic revenue averaged 3.1% year-on-year growth. Organic growth outpaced its two-year revenue growth, indicating that some combination of divestitures and foreign exchange rates dampened its headline results. 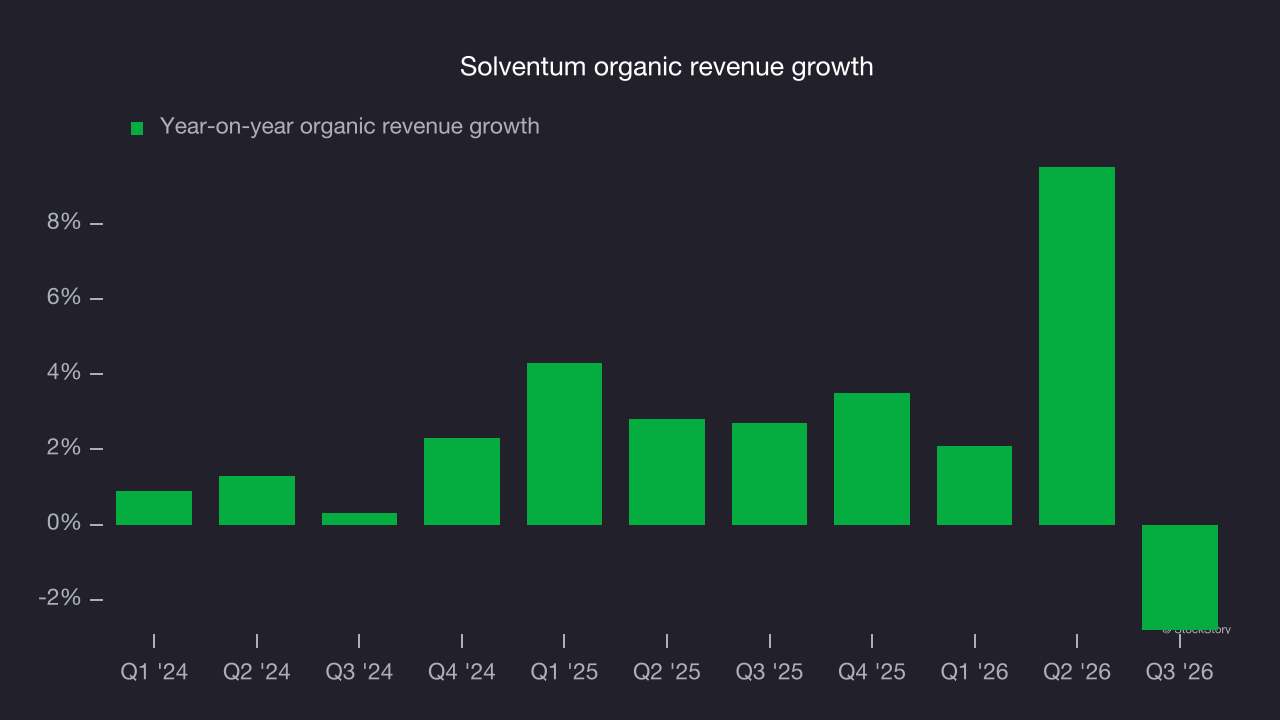
This quarter, Solventum’s revenue fell by 7% year on year to $1.95 billion but beat Wall Street’s consensus estimates by 0.9%.
Looking ahead, sell-side analysts expect revenue to grow 3.5% over the next 12 months, according to S&P. While this projection suggests its newer products and services will drive better top-line performance, it is still below average for the sector.
Adjusted operating margin
Solventum has been an efficient company over the last five years. It was one of the more profitable businesses in the healthcare sector, with an average adjusted operating margin of 22.5%.
Solventum’s adjusted operating margin decreased by 7.8 percentage points over the last five years. The company’s two-year trajectory also shows it failed to return profitability to its peak, as its margin fell by 4.6 percentage points. This was a poor performance, showing that expenses were rising and it couldn’t pass those costs on to its customers.
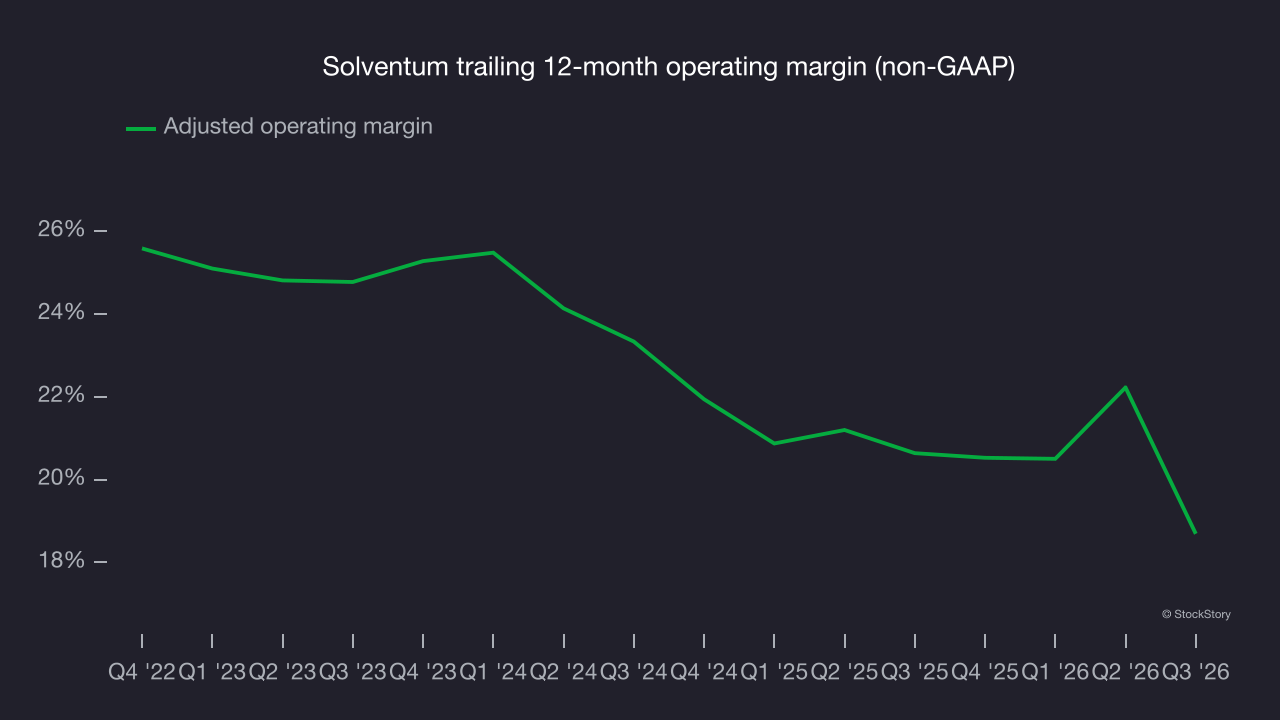
In Q3, Solventum reported an adjusted operating margin of 5.6%, down 14.9 percentage points year on year. This contraction shows it was less efficient because its expenses increased relative to its revenue.
Cash flow
Earnings are valuable for assessing company performance, but cash flow matters because accounting profits cannot pay the bills.
Solventum has shown impressive cash profitability, giving it the option to reinvest or return capital to investors. The company’s free cash flow margin averaged 11.7% over the last five years, better than the broader healthcare sector.
Solventum’s margin dropped by 29.9 percentage points during that time. If its declines continue, it could signal increasing investment needs and capital intensity.
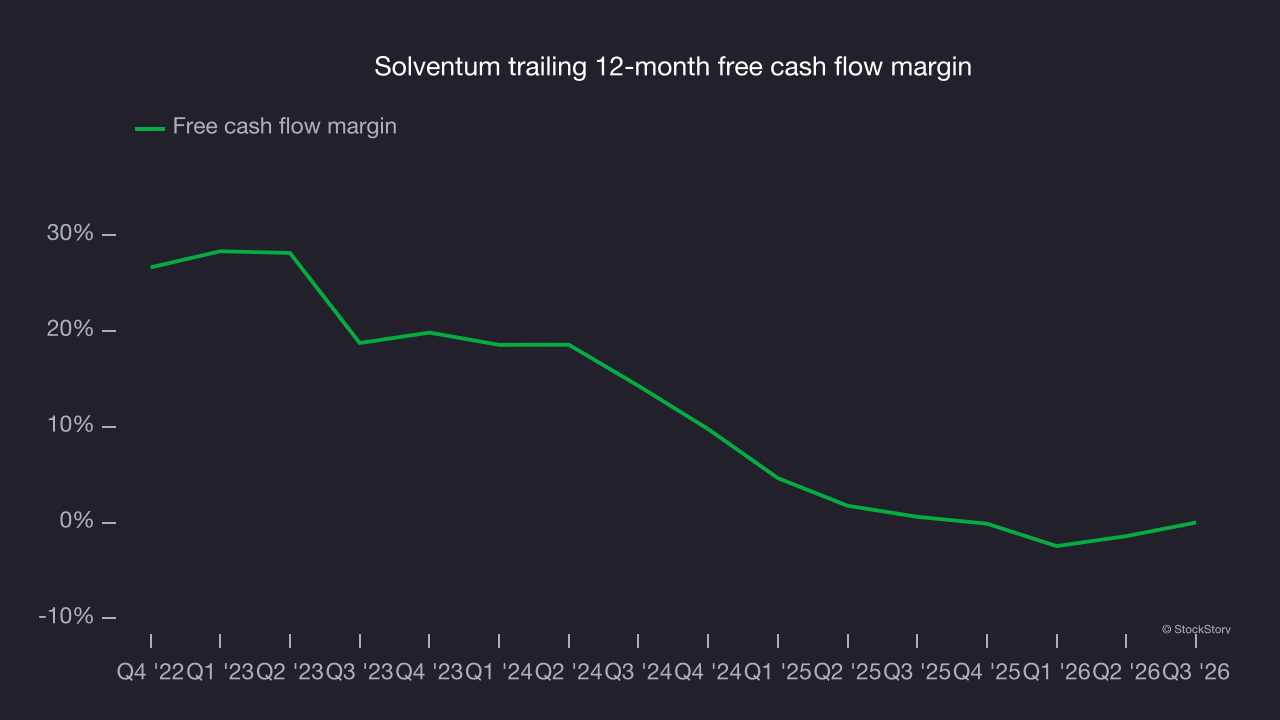
Solventum’s free cash flow totaled $97 million in Q3, equivalent to a 5% margin. Its cash flow turned positive after being negative in the same quarter last year, but short-term results warrant caution because investment needs can be seasonal, causing temporary swings. Long-term trends matter more than quarterly fluctuations.
Key takeaways from Solventum’s Q3 results
Solventum’s quarter could have been better: Organic revenue missed expectations, but EPS beat analysts’ consensus estimates and full-year EPS guidance came in narrowly ahead of Wall Street’s consensus. Shares edged higher 1.9% to $86.51 immediately after the results.
When evaluating Solventum at its current price, consider the bigger picture of valuation and business quality, as well as the latest earnings. For more on Solventum, read the full research report here (it’s free).