Casual salad chain Sweetgreen (NYSE: SG) reported revenue ahead of Wall Street’s expectations in Q3 2026, with revenue up 2.1% year on year to $176 million. Its GAAP loss of $0.26 per share was in line with analysts’ consensus estimates.
For more on Sweetgreen, read the full research report, available free.
Sweetgreen (SG) Q3 2026 highlights:
- Revenue $176 million vs S&P analysts’ consensus estimates of $170.1 million (2.1% year-on-year growth, 3.5% beat)
- EPS (GAAP) -$0.26 vs analysts’ consensus estimates of -$0.27 (in line)
- Adjusted EBITDA -$6.76 million (-3.8% margin, 55% year-on-year decline)
- EBITDA guidance -$21.5 million at the midpoint for the full year, above analysts’ consensus estimates of -$26.83 million
- Adjusted EBITDA margin -3.8%, down from -2.5% in the same quarter last year
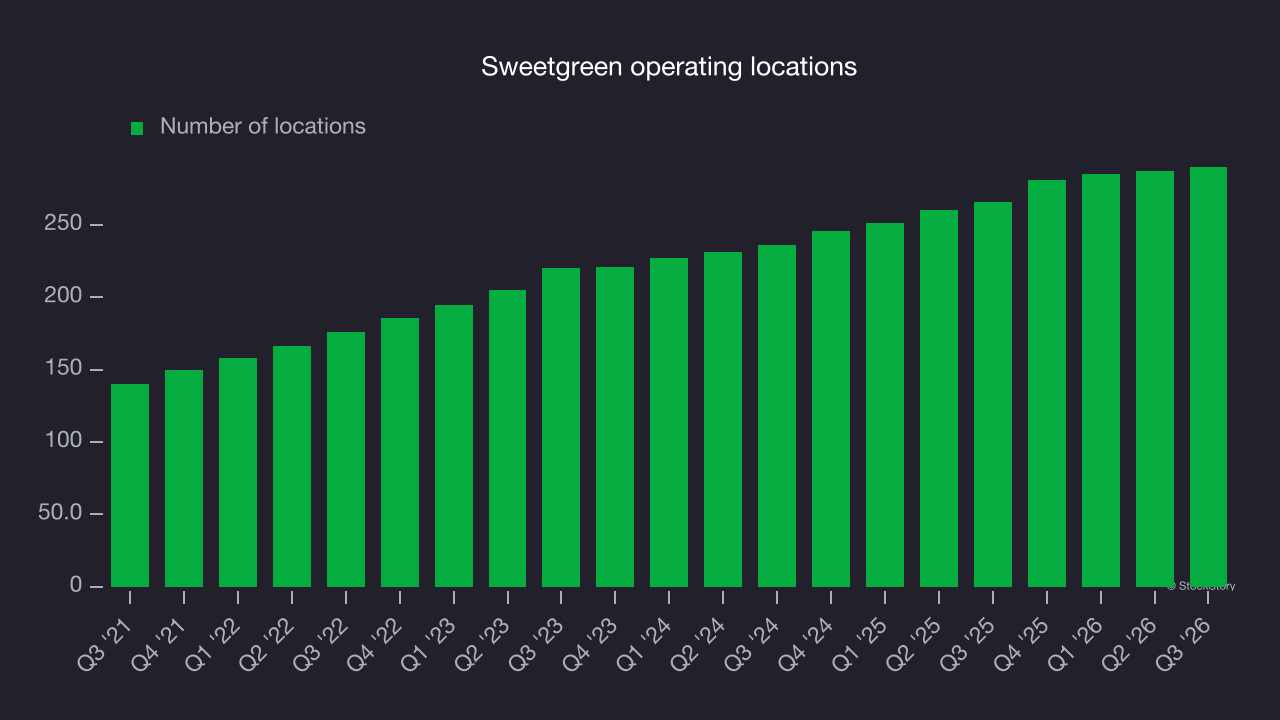
- Locations 290 at quarter end, up from 266 in the same quarter last year
- Same-store sales fell 6.4% year on year (-9.5% in the same quarter last year)
- Market capitalization $1.4 billion
“We believe our Sweet Growth Transformation Plan is beginning to take hold, with sales improving through the quarter and positive comparable sales in October, primarily driven by transaction growth,” said Jonathan Neman, Co-Founder and Chief Executive Officer. “We are confident in our plan to build on this progress by investing in our restaurant teams, delivering a consistently great customer experience and expanding our menu with bold, craveable food. Our focus is clear: bring more customers into sweetgreen and give them more reasons to come back.”
Revenue growth
Reviewing a company’s long-term revenue performance reveals insights into its quality. Any business can have short-term success, but a top-tier one grows for years.
With $685.4 million in revenue over the past 12 months, Sweetgreen is a small restaurant chain, which sometimes brings disadvantages compared to larger competitors benefiting from better brand awareness and economies of scale. On the positive side, it can grow faster because it has more room to build new restaurants.
Sweetgreen’s 14.6% annualized revenue growth over the last seven years was impressive as it opened new restaurants and expanded its reach.
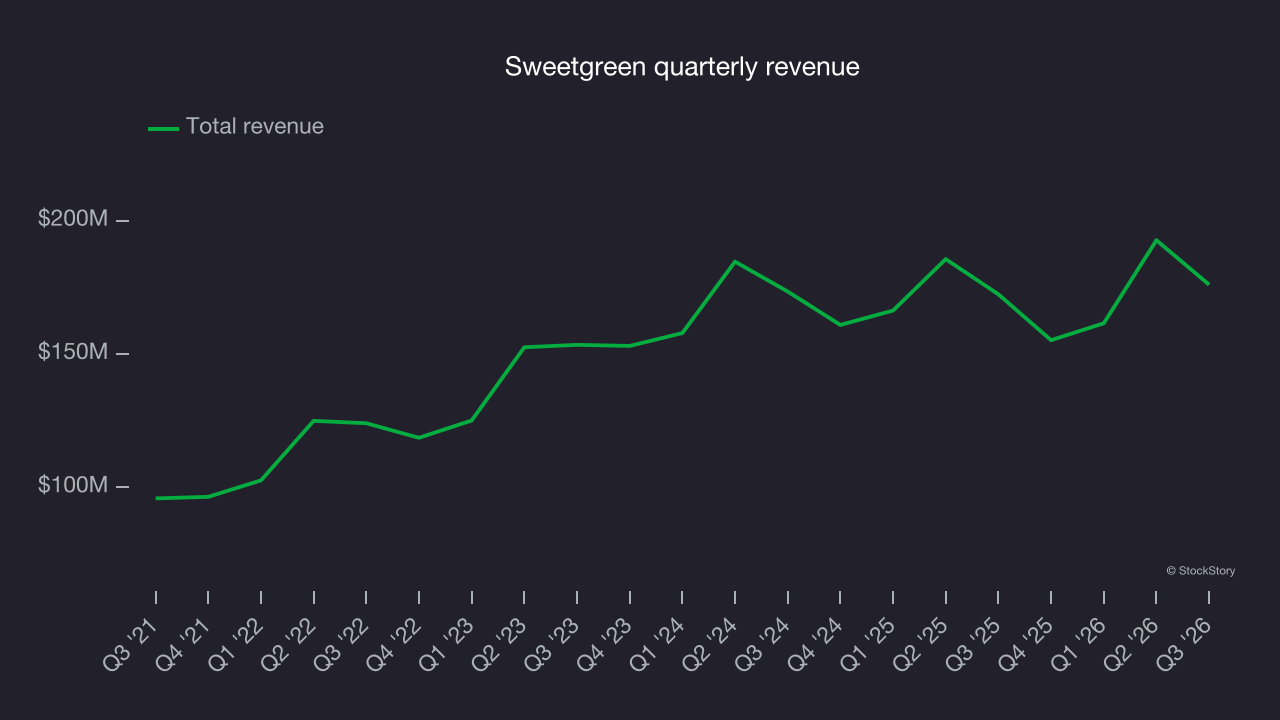
This quarter, Sweetgreen reported modest year-on-year revenue growth of 2.1% but beat Wall Street’s consensus estimates by 3.5%.
Looking ahead, sell-side analysts expect revenue to grow 6.8% over the next 12 months, according to S&P, a deceleration versus the last seven years. This underwhelming projection implies its menu offerings will face some demand headwinds.
Restaurant performance
Number of restaurants
A restaurant chain’s total number of dining locations often determines how much revenue it can generate.
Sweetgreen operated 290 locations in the latest quarter. It has opened new restaurants at a rapid pace over the last two years, averaging 11.8% annual growth, much faster than the broader restaurant sector. This gives it a chance to scale into a mid-sized business over time.
When a chain opens new restaurants, it usually means it’s investing for growth because there’s healthy demand for its meals and there are markets where its concepts have few or no locations.
Same-store sales
A company’s restaurant base only paints one part of the picture. When demand is high, it makes sense to open more. But when demand is low, it’s prudent to close some locations and use the money in other ways. Same-store sales offer insight into this topic because they measure organic growth at restaurants open for at least a year.
Sweetgreen’s demand has been shrinking over the last two years as its same-store sales have averaged 6.6% annual declines. This performance is concerning: it shows Sweetgreen is boosting revenue through new restaurant openings rather than growth at existing locations. Same-store sales should rise before a company takes on the costly, capital-intensive endeavor of expanding its restaurant base.
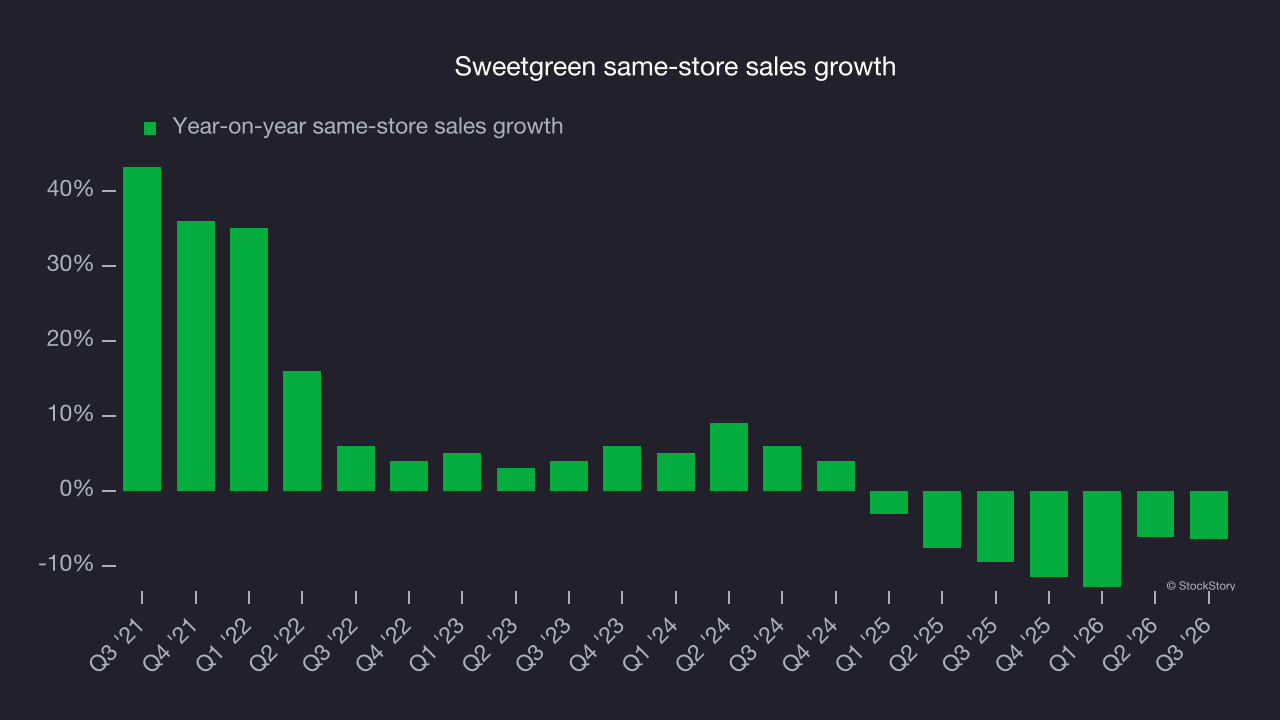
In the latest quarter, Sweetgreen’s same-store sales fell by 6.4% year on year. This performance was more or less in line with its historical levels.
Key takeaways from Sweetgreen’s Q3 results
Sweetgreen delivered sizable beats on both EBITDA and revenue this quarter, with each coming in well above analysts’ consensus estimates. Those results gave the quarter some important positives. Shares remained flat at $11.62 immediately after the release.
Sweetgreen may have had a good quarter, but does that make the stock a good investment? The latest quarter matters, but not nearly as much as longer-term fundamentals and valuation when deciding whether to buy the stock. For more on Sweetgreen, read our full research report here (it’s free).