
Hercules Capital currently trades at $16.35 per share and has shown little upside over the past six months, posting a small loss of 0.6%. The stock also fell short of the S&P 500’s 4.5% gain during that period.
Is there a buying opportunity in Hercules Capital, or does it present a risk to your portfolio? Dive into our full research report to see our analyst team’s opinion, it’s free.
Why is Hercules Capital not exciting?
We’re sitting this one out for now. Here are three reasons we avoid HTGC, plus one stock we’d rather own.
1. Lackluster revenue growth
We at StockStory place the most emphasis on long-term growth, but within financials, a stretched historical view may miss recent interest rate changes, market returns, and industry trends. Hercules Capital’s recent performance shows its demand has slowed significantly as its annualized revenue growth of 7.2% over the last two years was well below its five-year trend. 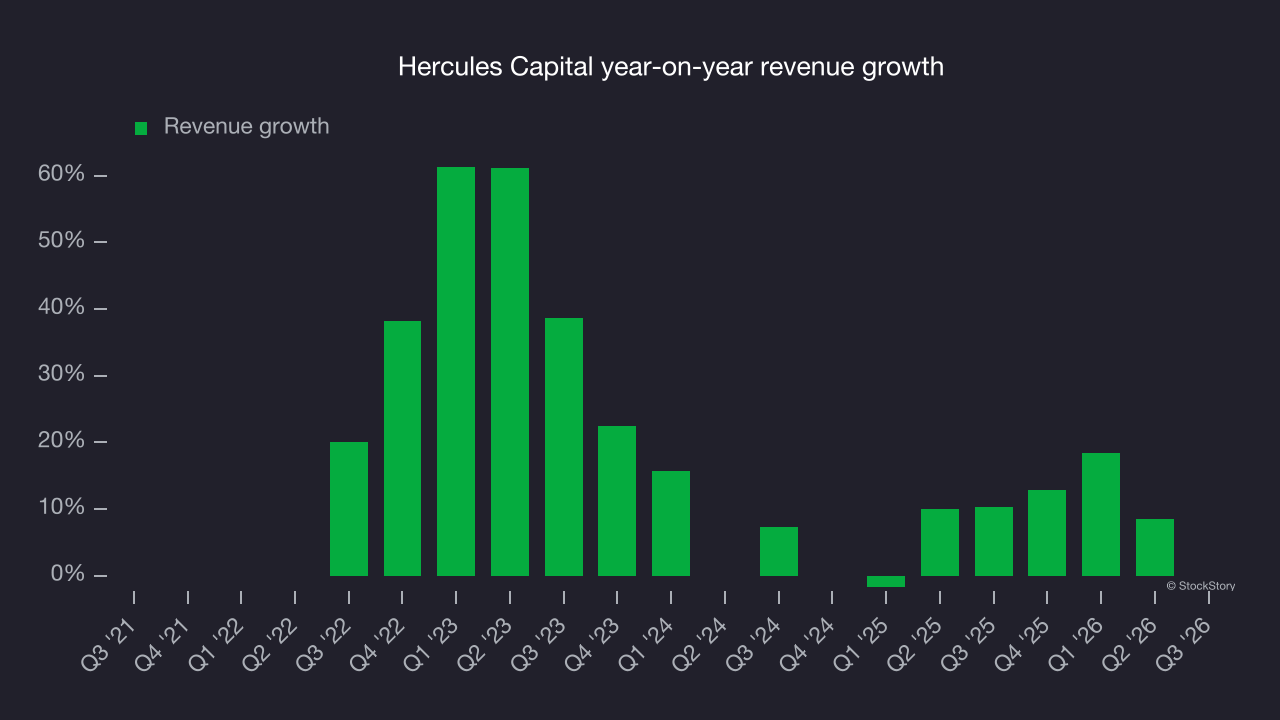 Note: Quarters not shown were determined to be outliers because they were impacted by outsized investment gains/losses that are not indicative of the recurring fundamentals of the business.
2. EPS barely growing
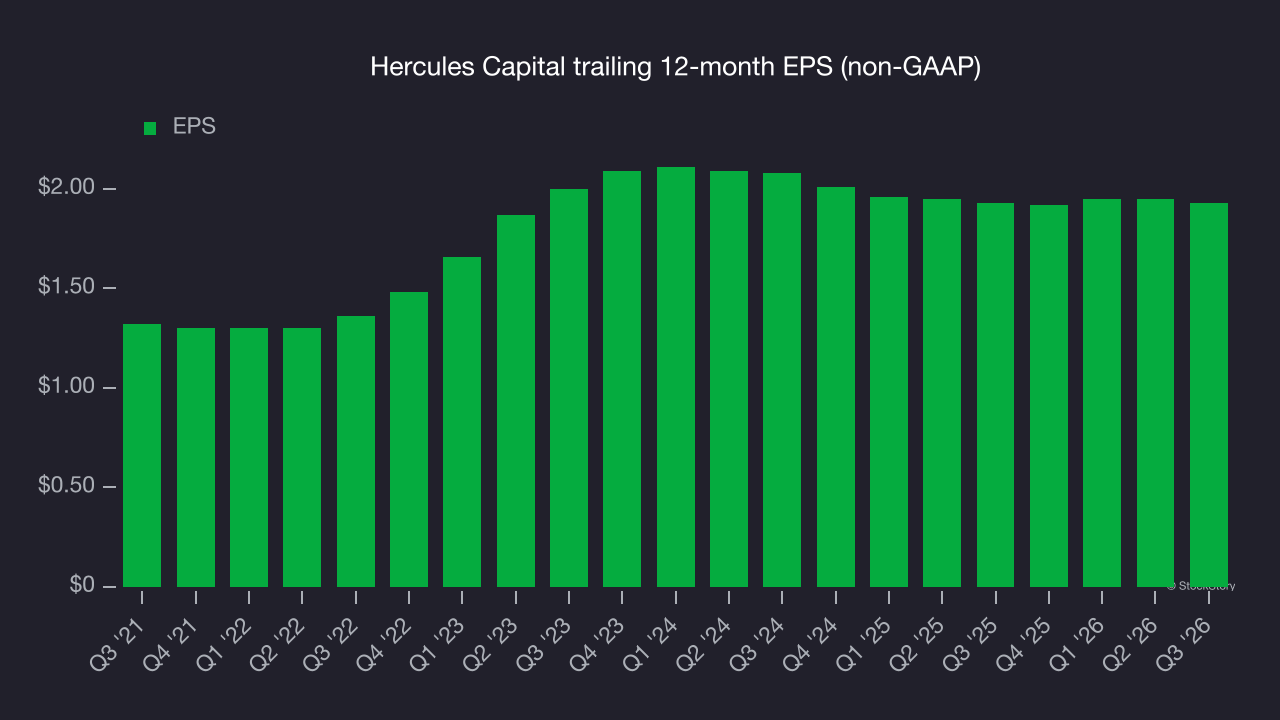
We track the long-term change in earnings per share (EPS) because it highlights whether a company’s growth is profitable.
Hercules Capital’s EPS grew at an unimpressive 7.9% compounded annual growth rate over the last five years, lower than its 14.9% annualized revenue growth. This tells us the company became less profitable on a per-share basis as it expanded.
3. High debt levels increase risk
Hercules Capital reported $50.56 million of cash and $2.57 billion of debt on its balance sheet in the most recent quarter.
As investors in high-quality companies, we primarily focus on whether a company’s profits can support its debt.
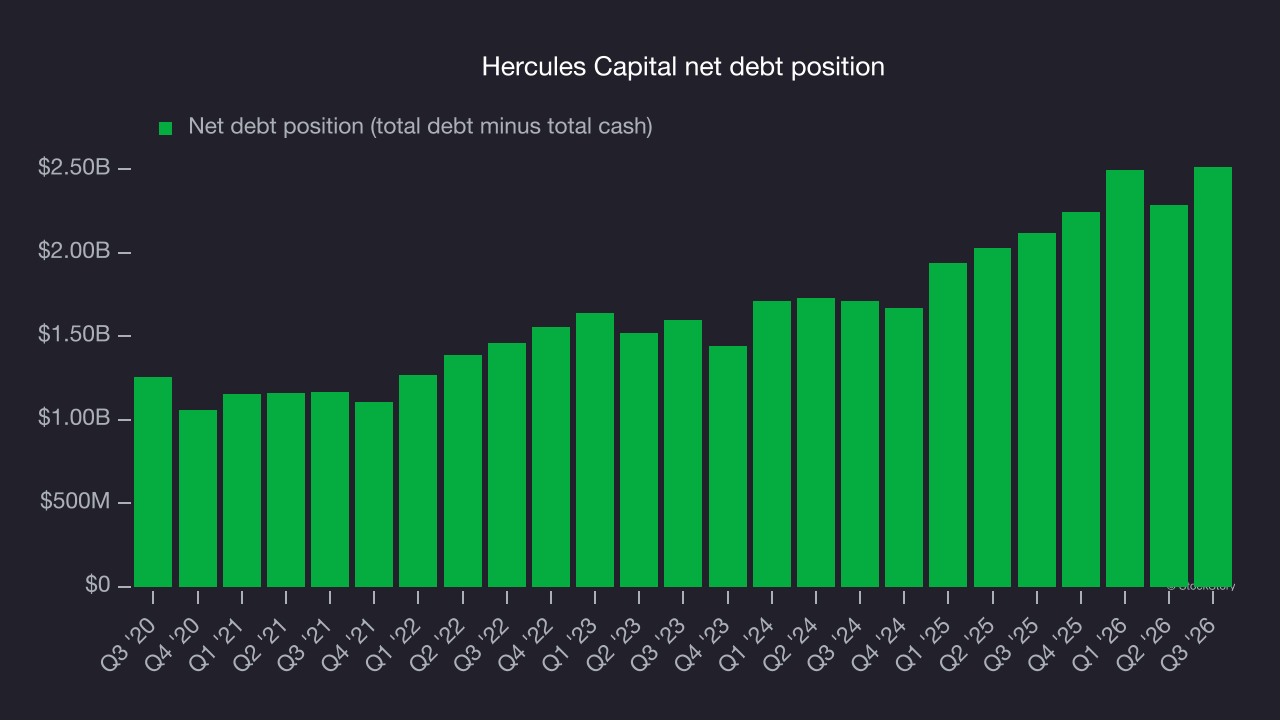
With $371.6 million of EBITDA over the last 12 months, we view Hercules Capital’s 6.8× net-debt-to-EBITDA ratio as inadequate. The company’s lacking profits relative to its borrowings give it little breathing room, raising red flags.
Final judgment
Hercules Capital isn’t a terrible business, but it isn’t one of our picks. With its shares underperforming the market lately, the stock trades at 8.6× forward P/E (or $16.35 per share). While this valuation is optically cheap, the potential downside is big given its shaky fundamentals. We’re fairly confident there are better investments elsewhere. We’d recommend looking at a dominant aerospace business that has perfected its M&A strategy.
Stocks we would buy instead of Hercules Capital
ALSO WORTH WATCHING: Top 5 Momentum Stocks. The best time to own a great stock is when the market is finally noticing it. These aren’t just high-quality businesses. Something is happening with them right now. Elite fundamentals meet near-term momentum — both boxes checked at the same time.
Find out which stocks our AI platform is flagging this week. See this week’s Strong Momentum stocks — FREE. Get Our Strong Momentum Stocks for Free HERE.
Stocks that have made our list include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-micro-cap company Kadant (+214% between June 2020 and June 2025). Find your next big winner with StockStory today.




