Silgan Holdings has been treading water for the past six months, recording a small return of 2.8% while holding steady at $41.64.
Is now the time to buy Silgan Holdings, or should you be careful about including it in your portfolio? Check out our in-depth research report to see what our analysts have to say, it’s free.
Why do we think Silgan Holdings will underperform?
We’re cautious about Silgan Holdings. Here are three reasons we avoid SLGN, plus one stock we’d rather own.
1. Long-term revenue growth disappoints
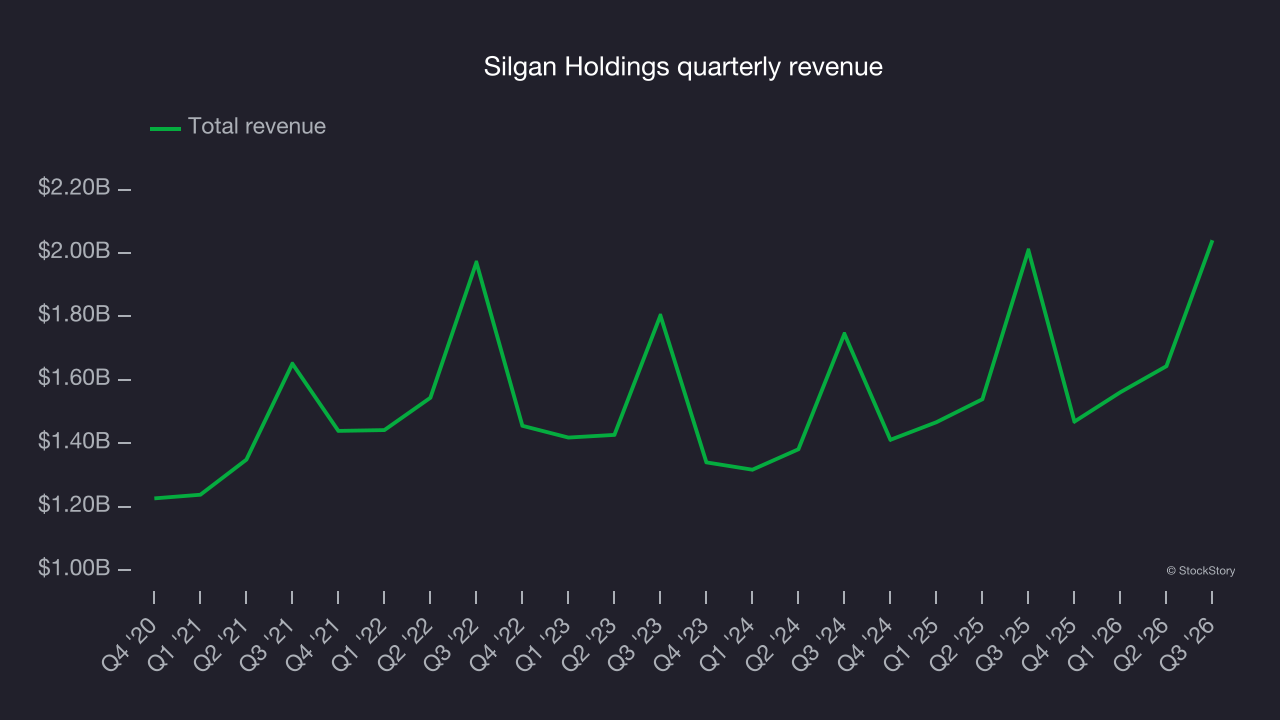
A company’s long-term performance is an indicator of its overall quality. Any business can have short-term success, but a top-tier one grows for years. Unfortunately, Silgan Holdings’s 4.2% annualized revenue growth over the last five years was sluggish. This fell short of our benchmark for the industrials sector.
2. Low gross margin reveals weak structural profitability
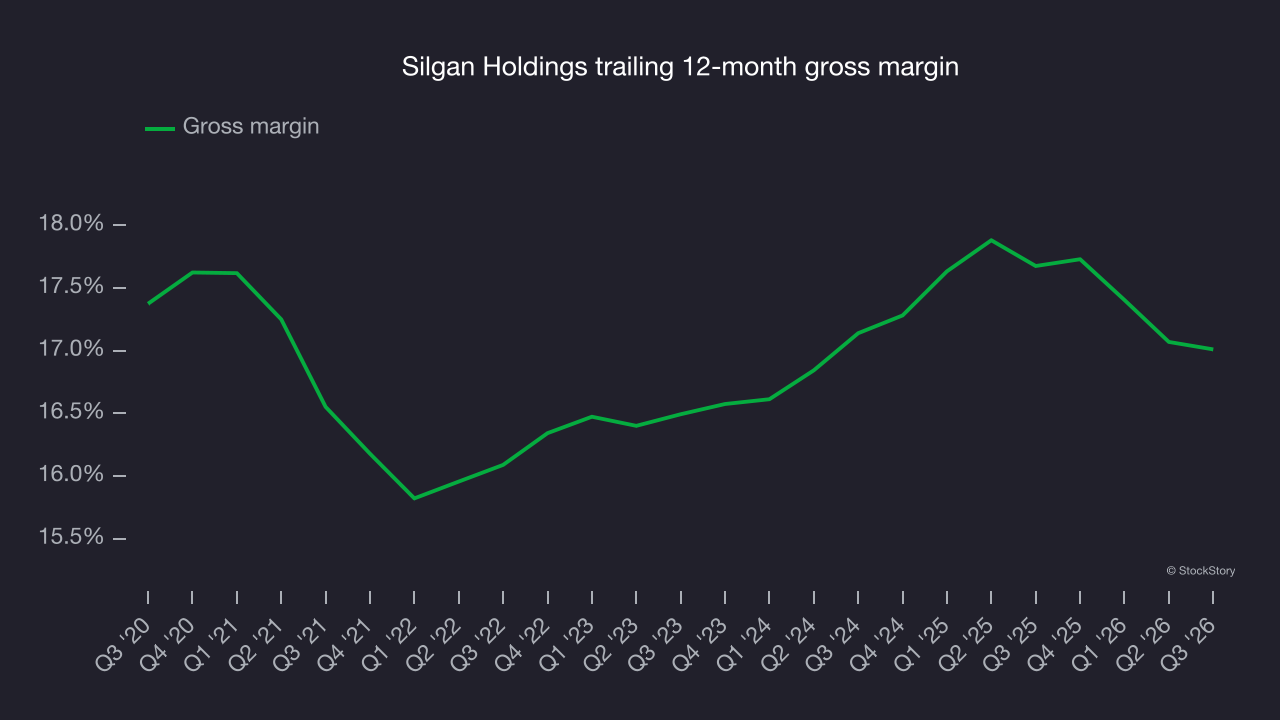
At StockStory, we prefer high gross margin businesses because they indicate the company has pricing power or differentiated products, giving it a chance to generate higher operating profits.
Silgan Holdings has bad unit economics for an industrials business, signaling it operates in a competitive market. As you can see below, it averaged a 16.9% gross margin over the last five years. That means Silgan Holdings paid its suppliers a lot of money ($83.12 for every $100 in revenue) to run its business.
3. High debt levels increase risk
As long-term investors, the risk we care about most is the permanent loss of capital, which can happen when a company goes bankrupt or raises money from a disadvantaged position. This is separate from short-term stock price volatility, something we are much less bothered by.
Silgan Holdings’s $6.57 billion of debt exceeds the $325 million of cash on its balance sheet. Furthermore, its 6× net-debt-to-EBITDA ratio (based on its EBITDA of $990.8 million over the last 12 months) shows the company is overleveraged.
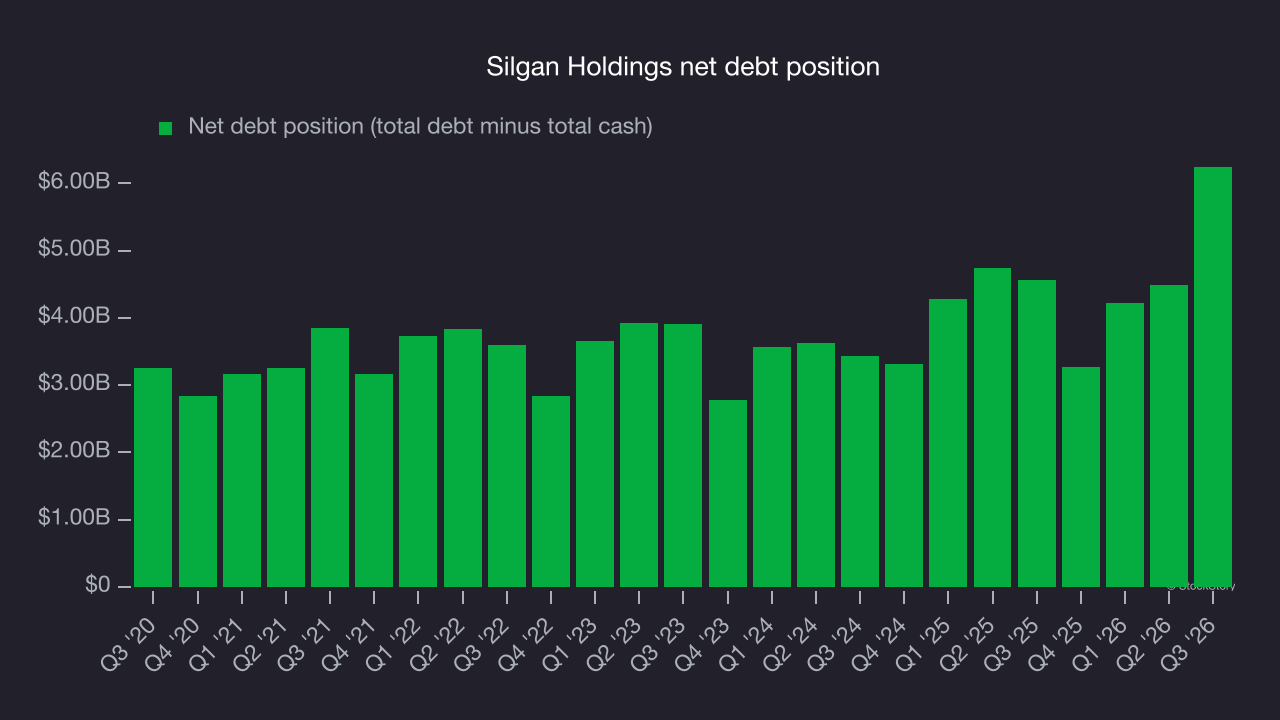
At this level of debt, incremental borrowing becomes increasingly expensive and credit agencies could downgrade the company’s rating if profitability falls. Silgan Holdings could also be backed into a corner if the market turns unexpectedly – a situation we seek to avoid as investors in high-quality companies.
We hope Silgan Holdings can improve its balance sheet and remain cautious until it increases its profitability or pays down its debt.
Final judgment
Silgan Holdings doesn’t pass our quality test. That said, the stock currently trades at 10.6× forward P/E (or $41.64 per share). This valuation multiple is fair, but we don’t have much confidence in the company. There are superior stocks to buy right now. Let us point you toward the Amazon and PayPal of Latin America.
Stocks we would buy instead of Silgan Holdings
WHILE YOU’RE HERE: Top 9 Market-Beating Stocks. The best stocks don’t just beat the market once. They do it again. And again. Robust revenue growth, rising free cash flow, returns on capital that leave their competition in the dust. The market has already rewarded these businesses.
But our AI platform says the party isn’t over. Find out which 9 stocks made the cut this week — FREE. Get Our Top 9 Market-Beating Stocks for Free HERE.
Stocks that have made our list include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-micro-cap company Tecnoglass (+1,552% between June 2020 and June 2025). Find your next big winner with StockStory today.