Since May 2026, Zions Bancorporation has been in a holding pattern, posting a small return of 1.6% while floating around $64.95.
Is now the time to buy Zions Bancorporation, or should you be careful about including it in your portfolio? Get the full breakdown from our expert analysts, it’s free.
Why is Zions Bancorporation not exciting?
We don’t have much confidence in Zions Bancorporation. Here are three reasons why ZION doesn’t excite us, plus one stock we’d rather own.
1. Net interest income points to soft demand
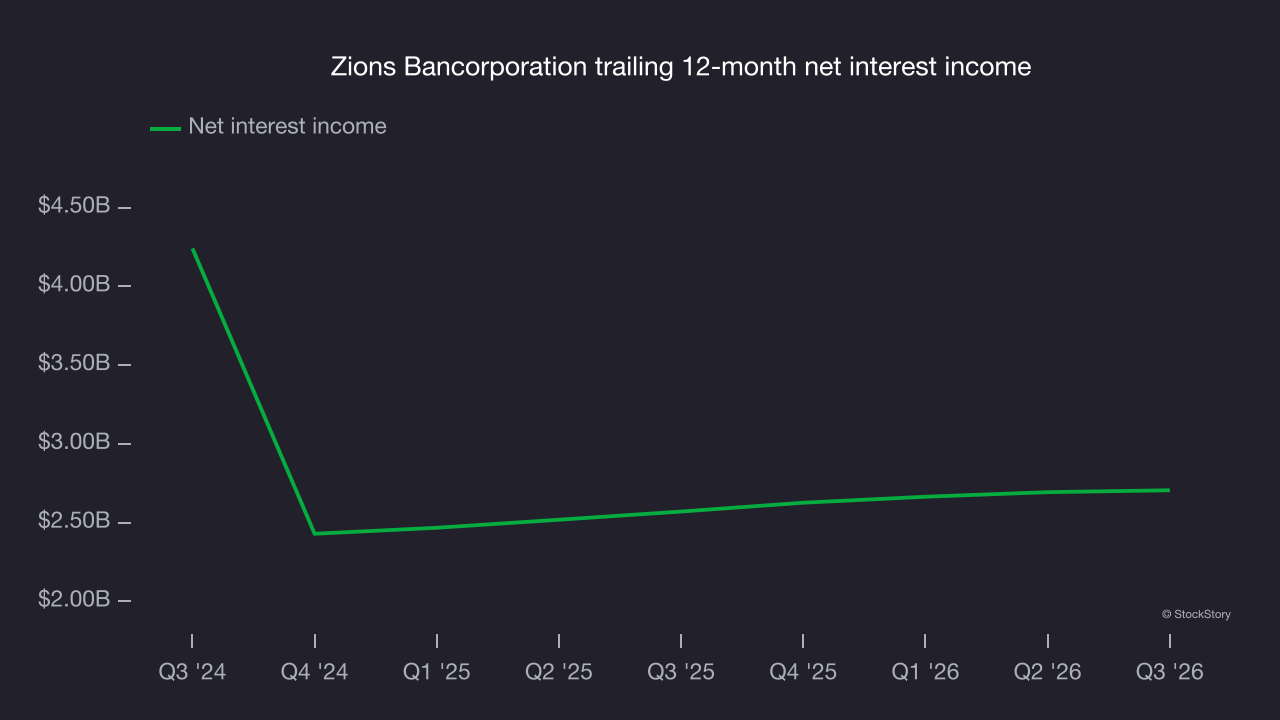
Our experience and research show the market cares primarily about a bank’s net interest income growth as one-time fees are considered a lower-quality and non-recurring revenue source.
Zions Bancorporation’s net interest income has grown at a 4.2% annualized rate over the last five years, much worse than the broader banking industry and in line with its total revenue. Its growth was driven by an increase in its net interest margin, which represents how much a bank earns in relation to its outstanding loans, as its loan book shrank throughout that period.
2. EPS growth has stalled
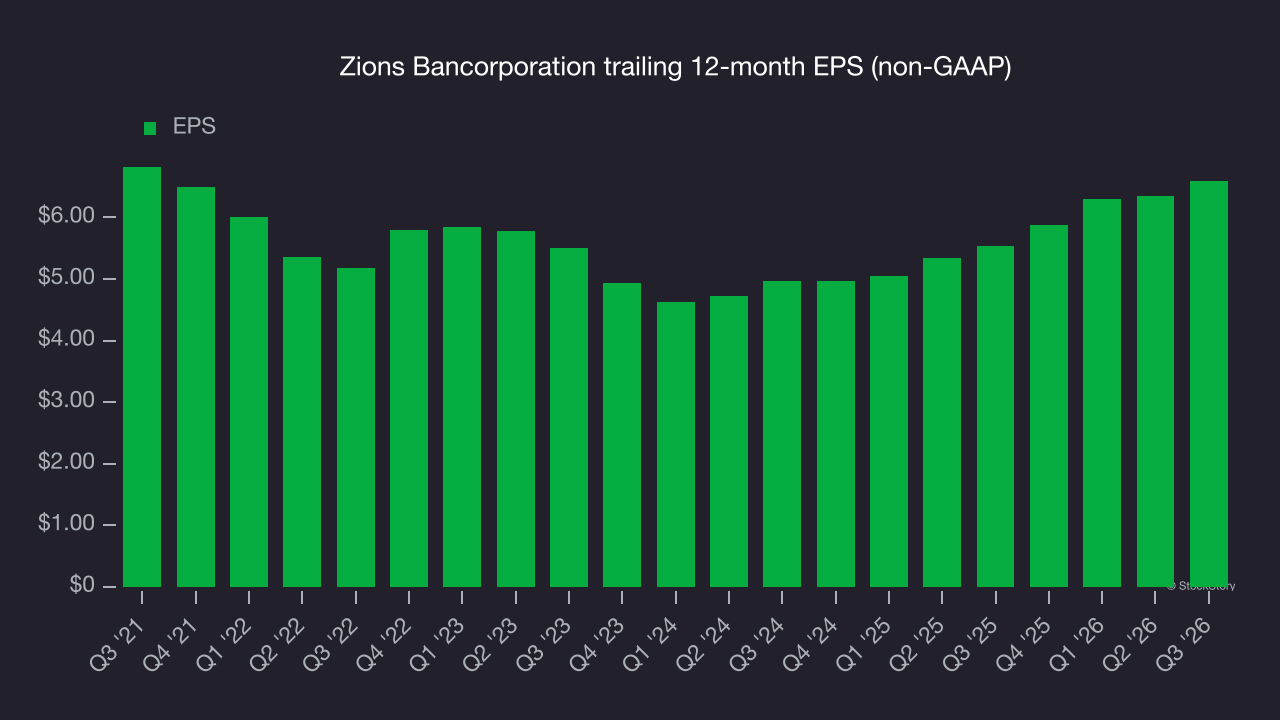
Analyzing the long-term change in earnings per share (EPS) shows whether a company’s incremental sales were profitable — for example, revenue could be inflated through excessive spending on advertising and promotions.
Zions Bancorporation’s flat EPS over the last five years was below its 4.4% annualized revenue growth. This tells us the company became less profitable on a per-share basis as it expanded.
3. Growing TBVPS reflects strong asset base
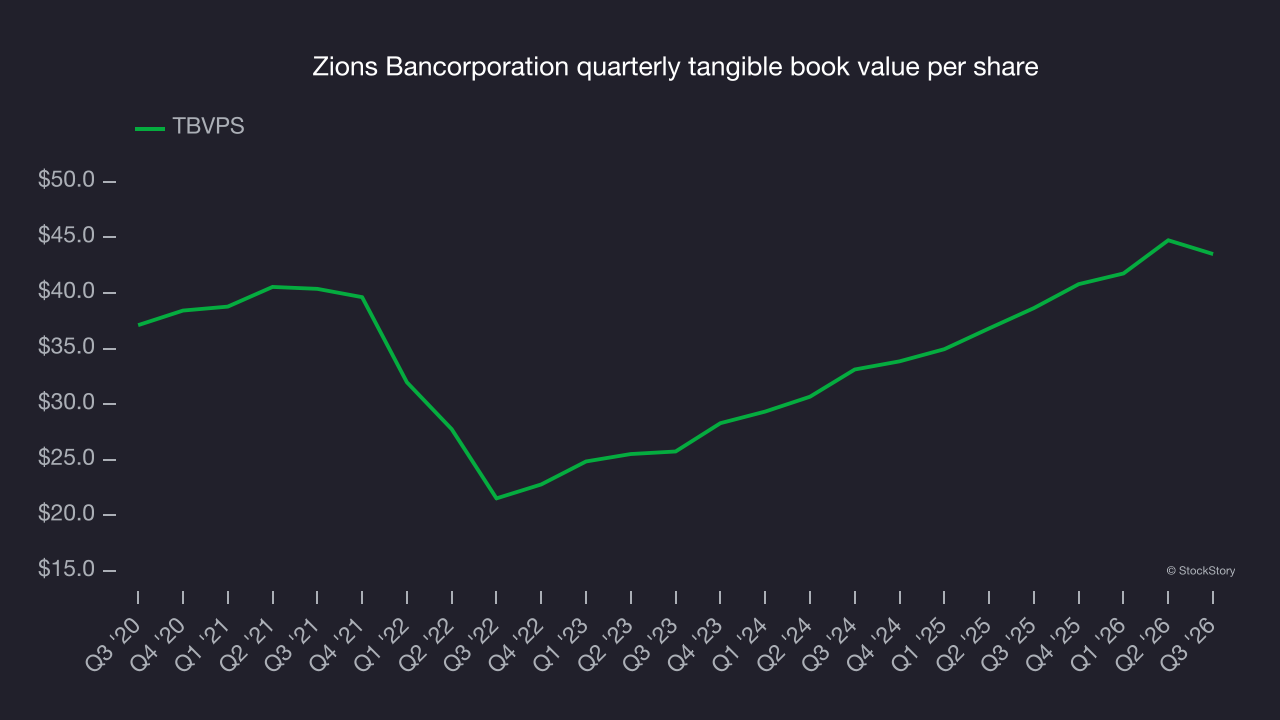
We consider tangible book value per share (TBVPS) the most important metric to track for banks. TBVPS represents the real, liquid net worth per share of a bank, excluding intangible assets that have debatable value upon liquidation.
Although Zions Bancorporation’s TBVPS increased by a meager 1.5% annually over the last five years, the good news is that its growth has recently accelerated as TBVPS grew at an impressive 14.6% annual clip over the past two years (from $33.12 to $43.50 per share).
Final judgment
Zions Bancorporation’s business quality ultimately falls short of our standards. That said, the stock currently trades at 1.2× forward P/B (or $64.95 per share). This valuation multiple is fair, but we don’t have much faith in the company. We’re pretty confident there are superior stocks to buy right now. Let us point you toward an all-weather company that owns household favorite Taco Bell.
Stocks we like more than Zions Bancorporation
ONE MORE THING: Top 6 Stocks for This Week. This market is separating quality stocks from expensive ones fast. AI is taking down whole sectors with no warning. In a rotation this fast, you need more than a list of good companies.
Our AI system flagged Palantir before it ran 1,662% between October 2022 and February 2026. AppLovin before it ran 753% between February 2024 and February 2026. Nvidia before it ran 1,178% between January 2023 and February 2026. Each week it produces 6 new names that pass the same tests. Get Our Top 6 Stocks for Free HERE.
Stocks that have made our list include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-micro-cap company Kadant (+214% between June 2020 and June 2025). Find your next big winner with StockStory today.