Real estate technology company AGNT (NASDAQ: AGNT) met Wall Street’s revenue expectations in Q3 2026, with revenue up 5.8% year on year to $1.39 billion. On the other hand, next quarter’s revenue guidance of $1.1 billion was less impressive, coming in 10.7% below analysts’ consensus estimates. Its GAAP loss of $0.03 per share was $0.02 below analysts’ consensus estimates.
For more on AGNT, read our full research report for free.
AGNT (AGNT) Q3 2026 highlights:
- Revenue $1.39 billion vs analysts’ consensus estimates of $1.39 billion, according to S&P (5.8% year-on-year growth, in line)
- EPS (GAAP) -$0.03 vs analysts’ consensus estimates of -$0.01 ($0.02 miss)
- Adjusted EBITDA $17.14 million vs analysts’ consensus estimates of $17.87 million (1.2% margin, 4.1% miss)
- Revenue guidance $1.1 billion at the midpoint for Q4 2026, below analysts’ consensus estimates of $1.23 billion
- EBITDA guidance $43.5 million at the midpoint for the full year, below analysts’ consensus estimates of $53.88 million
- Operating margin 0.2%, in line with the same quarter last year
- Free cash flow margin 1.3%, similar to the same quarter last year
- Market capitalization $650.1 million
“It is a privilege to lead AGNT into its next chapter as Chief Executive Officer. AGNT’s third-quarter results reflect a business with more agents, and more productive agents, than a year ago, and a financial position that we believe leaves us well-positioned to lead the industry through challenging times,” said Leo Pareja, CEO of AGNT, Inc. “Our results are driven by the simple belief that when we put agents first, the business gets stronger. I’m excited about what’s ahead, with a platform that gives agents more ways to grow, a team that executes with discipline, and a culture that has never been afraid to move first. We’re embracing the AI shift that’s reshaping this business, and we’re doing it in a way that works for agents. Whatever the market does next, we intend for AGNT to remain the company the rest of the industry is following.”
Revenue growth
Examining a company’s long-term performance can provide clues about its quality. Any business can experience short-term success, but top-performing ones sustain growth for years. AGNT’s revenue grew at a weak 8.8% compounded annual growth rate over the last five years, falling short of the consumer discretionary sector benchmark.
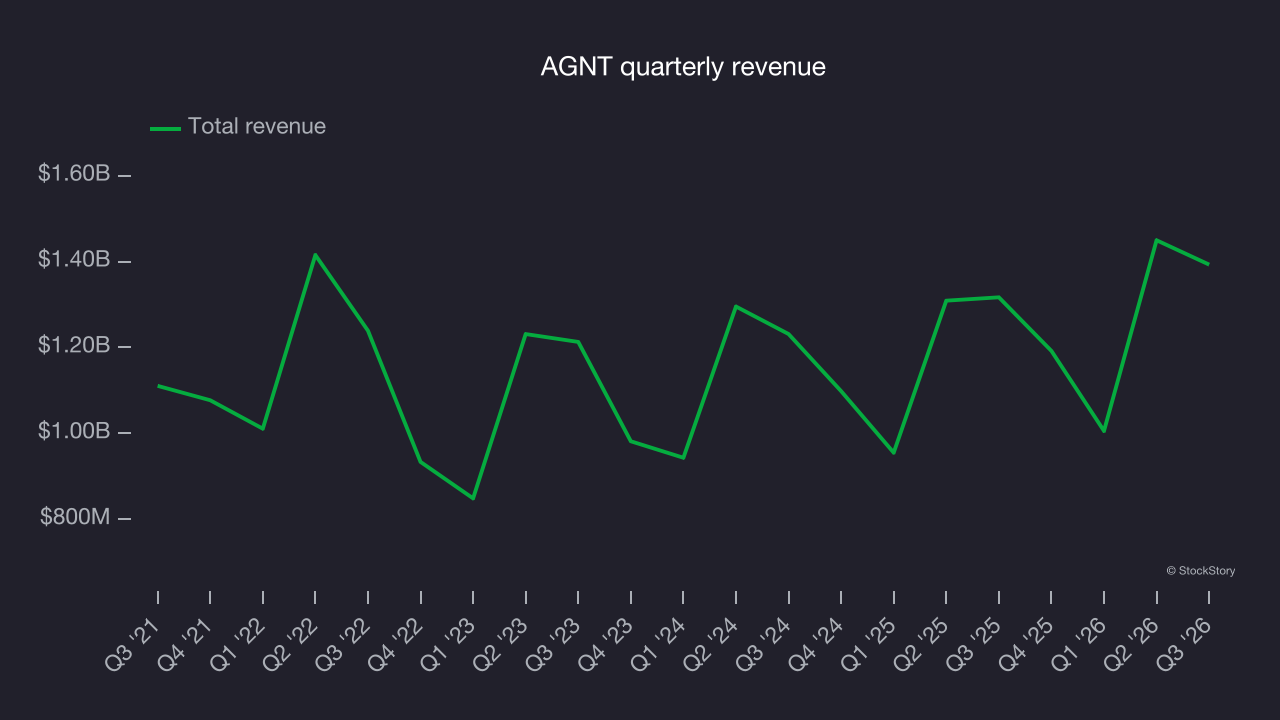
Long-term growth is the most important, but within consumer discretionary, product cycles are short and revenue can be hit-driven due to rapidly changing trends and consumer preferences. AGNT’s recent performance shows its demand has slowed as its annualized revenue growth of 6.4% over the last two years was below its five-year trend. Decelerating revenue growth in the sector warrants caution, as it could signal changing consumer tastes aided by low switching costs. 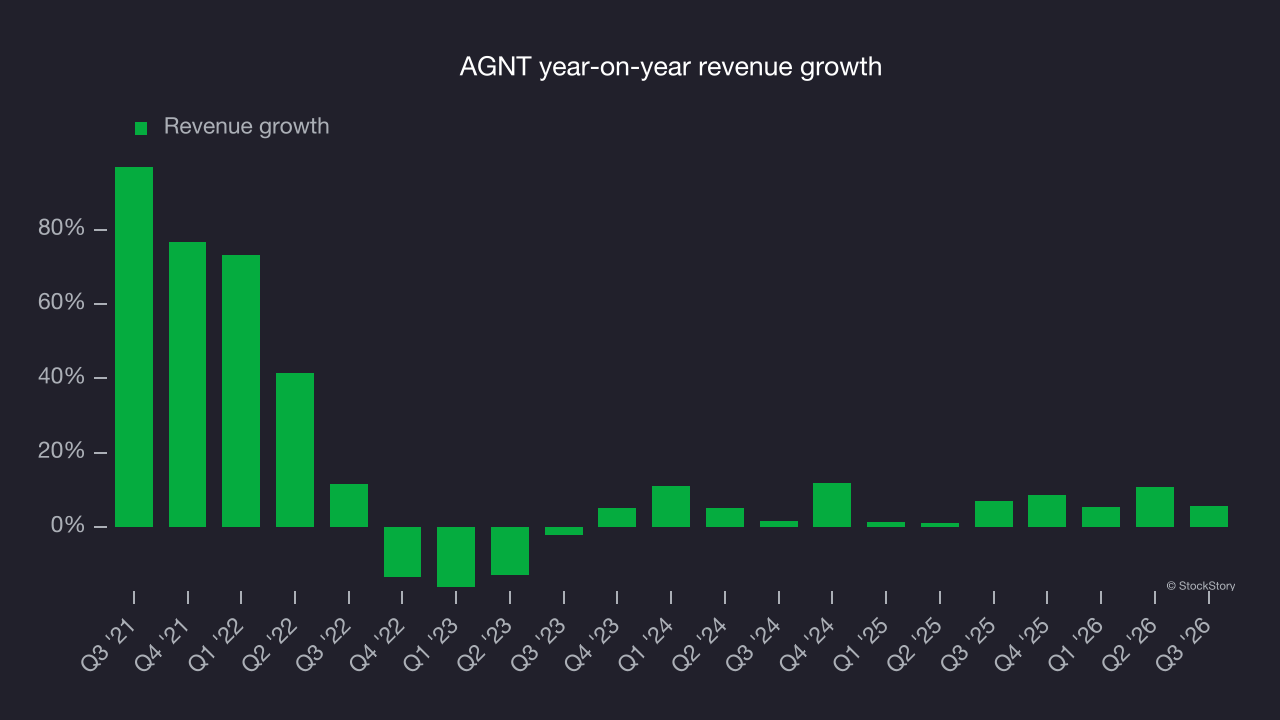
This quarter, AGNT grew its revenue by 5.8% year on year, and its $1.39 billion of revenue was in line with Wall Street’s consensus estimates. Company management is currently guiding for a 7.7% year-on-year decline in revenue next quarter.
Looking further ahead, sell-side analysts expect revenue to grow 4.9% over the next 12 months, according to S&P, a slight deceleration versus the last two years. This uninspiring projection implies its products and services will face some demand challenges.
Operating margin
AGNT’s operating margin has generally stayed the same over the last 12 months. The company broke even over the last two years, an inadequate result for a consumer discretionary business. Its large expense base and inefficient cost structure were the main reasons for this performance.
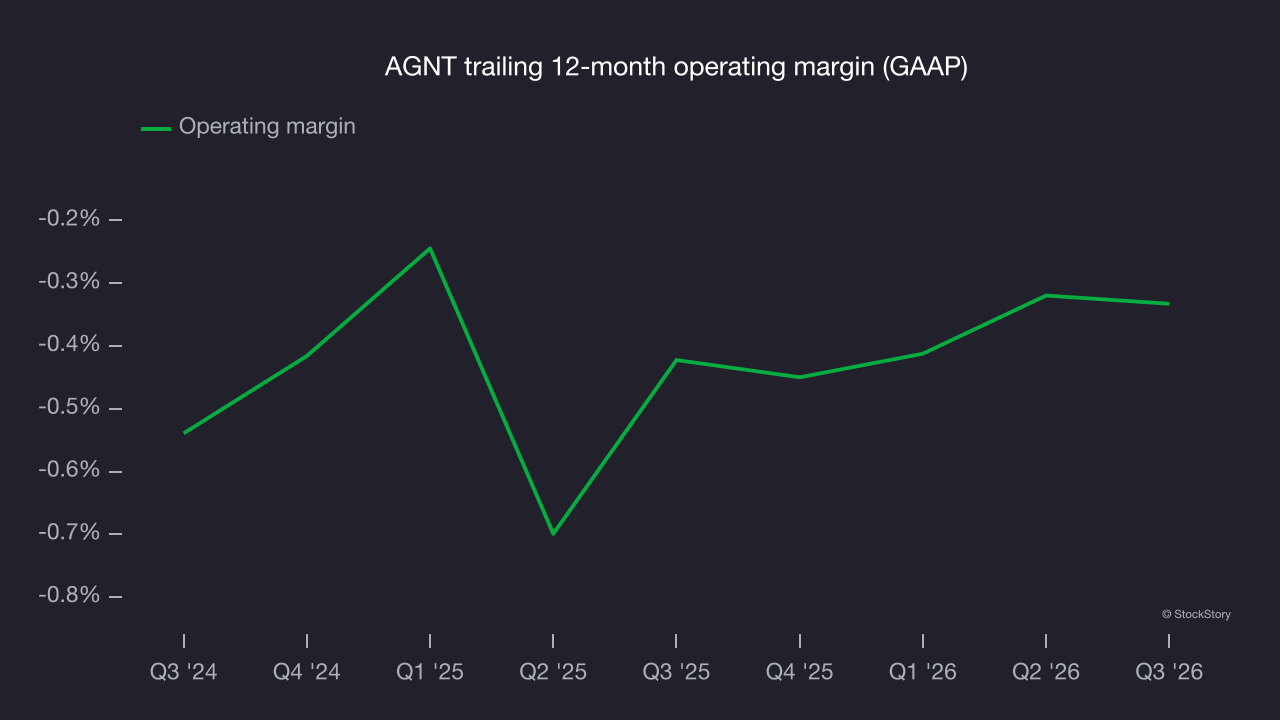
In Q3, AGNT’s breakeven margin was 0.2%, in line with the same quarter last year. This indicates the company’s overall cost structure has been relatively stable.
Earnings per share
Revenue trends explain a company’s historical growth, but the long-term change in earnings per share (EPS) points to the profitability of that growth – for example, a company could inflate its revenue through excessive spending on advertising and promotions.
AGNT’s EPS declined by 18.5% annually over the last five years while its revenue grew by 8.8%. However, its operating margin didn’t change during this time, indicating that non-fundamental factors such as interest and taxes affected its ultimate earnings.
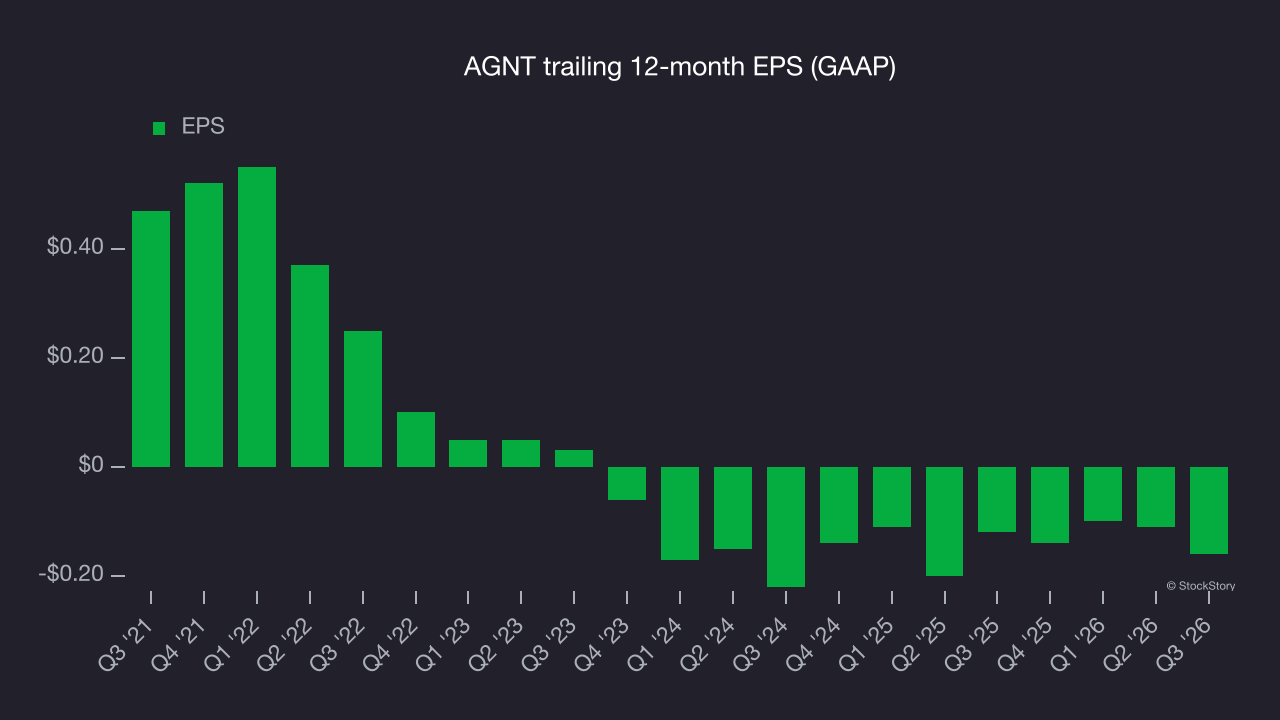
In Q3, AGNT reported EPS of negative $0.03, down from $0.02 in the same quarter last year. This result missed analysts’ consensus estimates. There is insufficient data to assess expected EPS growth based on Wall Street analysts’ consensus projections.
Key takeaways from AGNT’s Q3 results
AGNT’s outlook offered little to like: Full-year EBITDA guidance missed expectations, and revenue guidance for next quarter fell short of Wall Street’s consensus estimates. That made for a weaker quarter overall. Shares remained flat at $3.64 immediately after the report.
When deciding whether to buy the stock, it’s important to consider its valuation, business quality and latest quarterly results. Read the full research report here for more on those factors (it’s free).