Griffon currently trades at $93.14 and has been a dream stock for shareholders. It’s returned 276% since October 2021, blowing past the S&P 500’s 77.9% gain. The company has also beaten the index over the past six months as its stock price is up 30.4% thanks to its solid quarterly results.
Is there a buying opportunity in Griffon, or does it present a risk to your portfolio? Get the full stock story straight from our expert analysts, it’s free.
Why Is Griffon Not Exciting?
We’re happy investors have made money, but we’re cautious about Griffon. Here are three reasons why there are better opportunities than GFF, plus one stock we’d rather own.
1. Revenue Spiraling Downwards
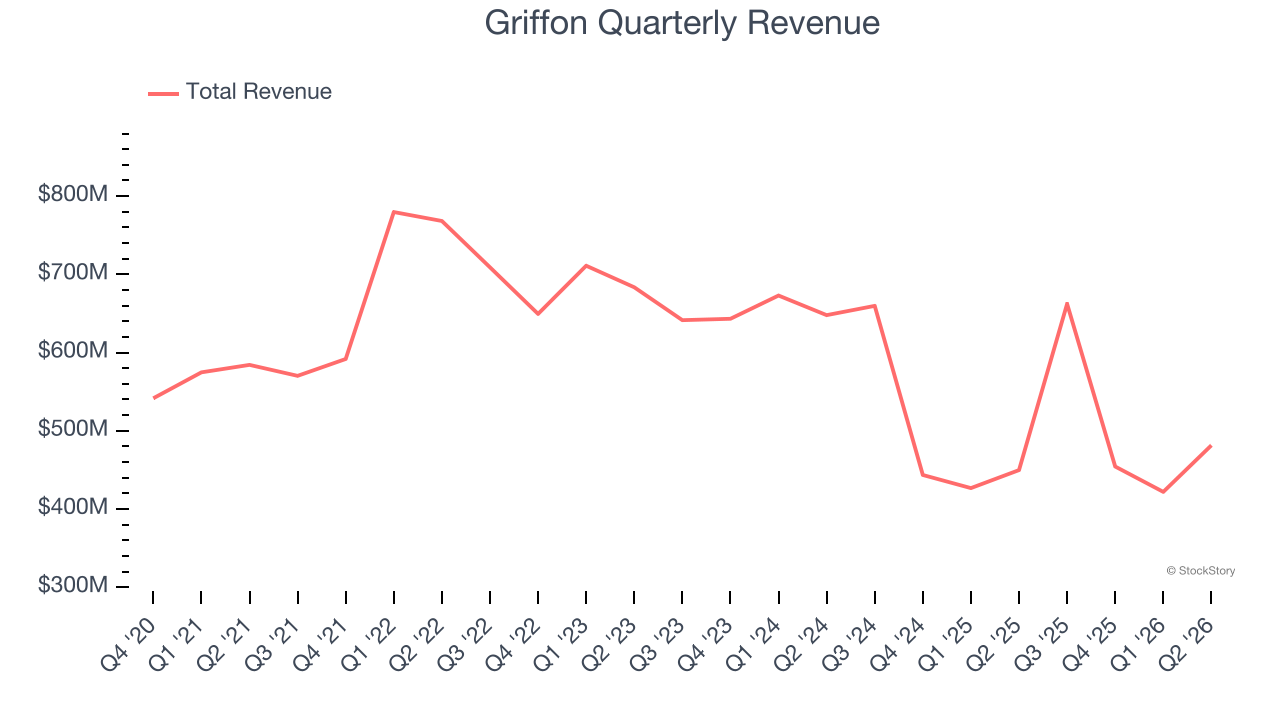
Examining a company’s long-term performance can provide clues about its quality. Any business can have short-term success, but a top-tier one grows for years. Over the last five years, Griffon’s demand was weak and its revenue declined by 4.4% per year. This wasn’t a great result and signals it’s a lower quality business.
2. Revenue Projections Show Stormy Skies Ahead
Forecasted revenues by Wall Street analysts signal a company’s potential. Predictions may not always be accurate, but accelerating growth typically boosts valuation multiples and stock prices while slowing growth does the opposite.
Over the next 12 months, sell-side analysts expect Griffon’s revenue to drop by 6.7%. Although this projection is better than its two-year trend, it’s tough to feel optimistic about a company facing demand difficulties.
3. Recent EPS Growth Below Our Standards
While long-term earnings trends give us the big picture, we also track EPS over a shorter period because it can provide insight into an emerging theme or development for the business.
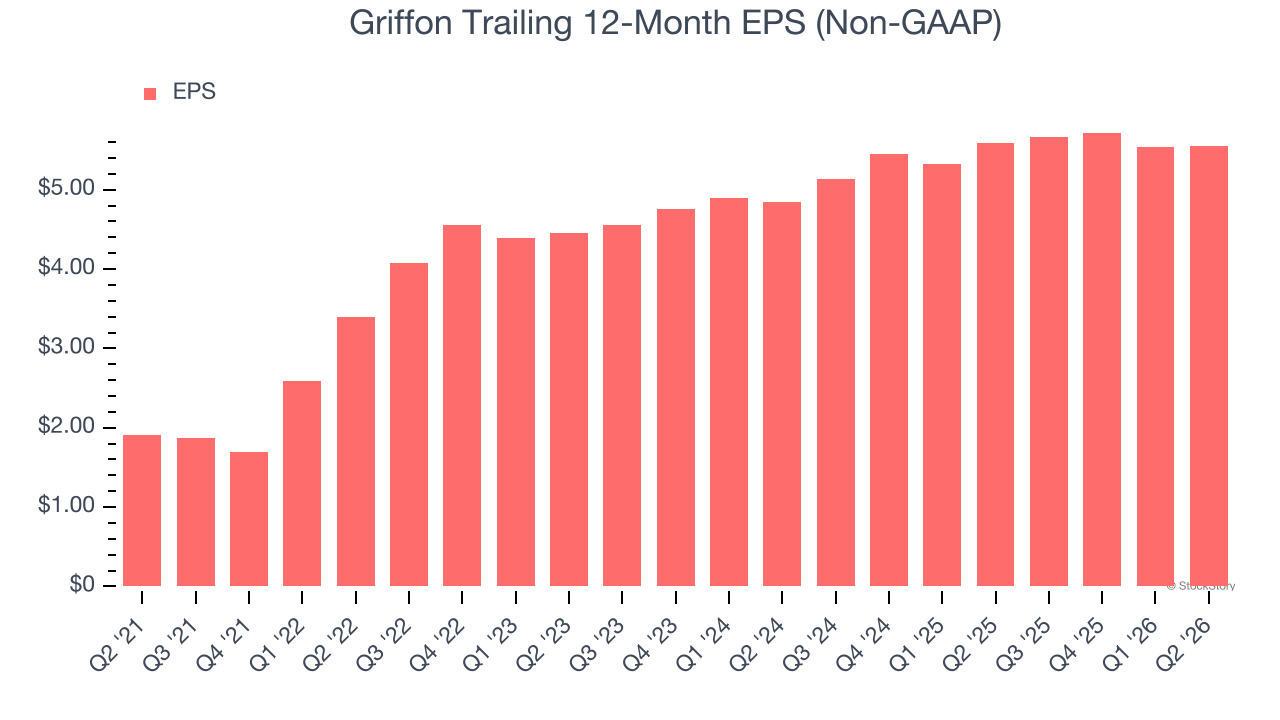
Griffon’s EPS grew at an unimpressive 7% compounded annual growth rate over the last two years. On the bright side, this performance was higher than its 12% annualized revenue declines and tells us management adapted its cost structure in response to a challenging demand environment.
Final Judgment
Griffon’s business quality ultimately falls short of our standards. With its shares topping the market in recent months, the stock trades at 15.6× forward P/E (or $93.14 per share). While this valuation is reasonable, we don’t really see a big opportunity at the moment. We’re fairly confident there are better investments elsewhere. We’d recommend looking at one of our all-time favorite software stocks.
Stocks We Would Buy Instead of Griffon
ALSO WORTH WATCHING: Top 5 Momentum Stocks. The best time to own a great stock is when the market is finally noticing it. These aren’t just high-quality businesses. Something is happening with them right now. Elite fundamentals meet near-term momentum — both boxes checked at the same time.
Find out which stocks our AI platform is flagging this week. See this week’s Strong Momentum stocks — FREE. Get Our Strong Momentum Stocks for Free HERE.
Stocks that have made our list include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-micro-cap company Tecnoglass (+1,552% between June 2020 and June 2025). Find your next big winner with StockStory today.