Wrapping up Q2 earnings, we look at the numbers and key takeaways for the consumer discretionary - home furnishings stocks, including Somnigroup (NYSE: SGI) and its peers.
The Consumer Discretionary sector, by definition, is made up of companies selling non-essential goods and services. When economic conditions deteriorate or tastes shift, consumers can easily cut back or eliminate these purchases. For long-term investors with five-year holding periods, this creates a structural challenge: the sector is inherently hit-driven, with low switching costs and fickle customers. As a result, only a handful of companies can reliably grow demand and compound earnings over long periods, which is why our bar is high and High Quality ratings are rare. Home furnishings companies design, manufacture, and sell furniture, décor, bedding, and related household products for residential and commercial spaces. Tailwinds include e-commerce expansion enabling broader distribution, continued remote-work trends sustaining home improvement interest, and premiumization as consumers invest in living spaces. However, headwinds are considerable: demand is closely tied to housing market activity, and rising mortgage rates have slowed home sales—a key purchase trigger. Bulky products carry high shipping costs and complex logistics. Intense competition from low-cost imports and mass-market retailers compresses margins, while consumer spending on furnishings is among the first categories deferred during economic downturns.
The 4 consumer discretionary - home furnishings stocks we track reported a mixed Q2. As a group, revenues were in line with analysts’ consensus estimates while next quarter’s revenue guidance was 7.8% below.
Amidst this news, share prices of the companies have had a rough stretch. On average, they are down 22% since the latest earnings results.
Somnigroup (NYSE: SGI)
Established through the merger of Tempur-Pedic and Sealy in 2012, Somnigroup (NYSE: SGI) is a bedding manufacturer known for its innovative memory foam mattresses and sleep products
Somnigroup reported revenues of $1.82 billion, down 3% year on year. This print fell short of analysts’ expectations by 3.1%. Overall, it was a slower quarter for the company with full-year EPS guidance missing analysts’ expectations and a slight miss of analysts’ EBITDA estimates.
Company Chairman and CEO Scott Thompson commented, "Our second-quarter performance demonstrates our global team's ability to execute in a dynamic environment. We delivered solid results while continuing to fully invest in our iconic brands, advancing our international growth strategy, preparing for the North American launch of our new Stearns & Foster collection and strengthening our multiple distribution platforms. The progress we are making across the business reinforces our confidence in our long-term strategy and our ability to create sustainable value."
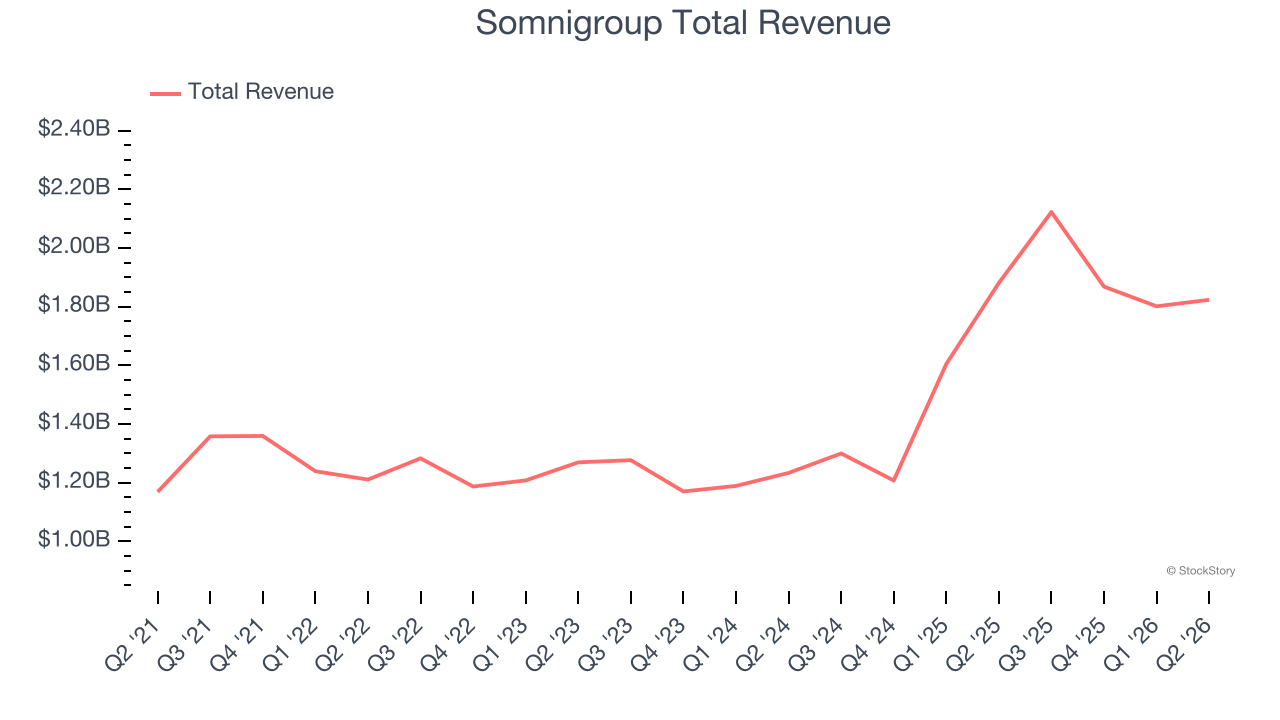
The market seems disappointed with the results as the stock is down 9.8% since reporting and currently trades at $62.74.
Read our full report on Somnigroup here, it’s free.
Best Q2: Mohawk Industries (NYSE: MHK)
Established in 1878, Mohawk Industries (NYSE: MHK) is a leading producer of floor-covering products for both residential and commercial applications.
Mohawk Industries reported revenues of $2.99 billion, up 6.8% year on year, outperforming analysts’ expectations by 7.2%. The business had an incredible quarter with EPS guidance for next quarter exceeding analysts’ expectations and a beat of analysts’ EPS estimates.
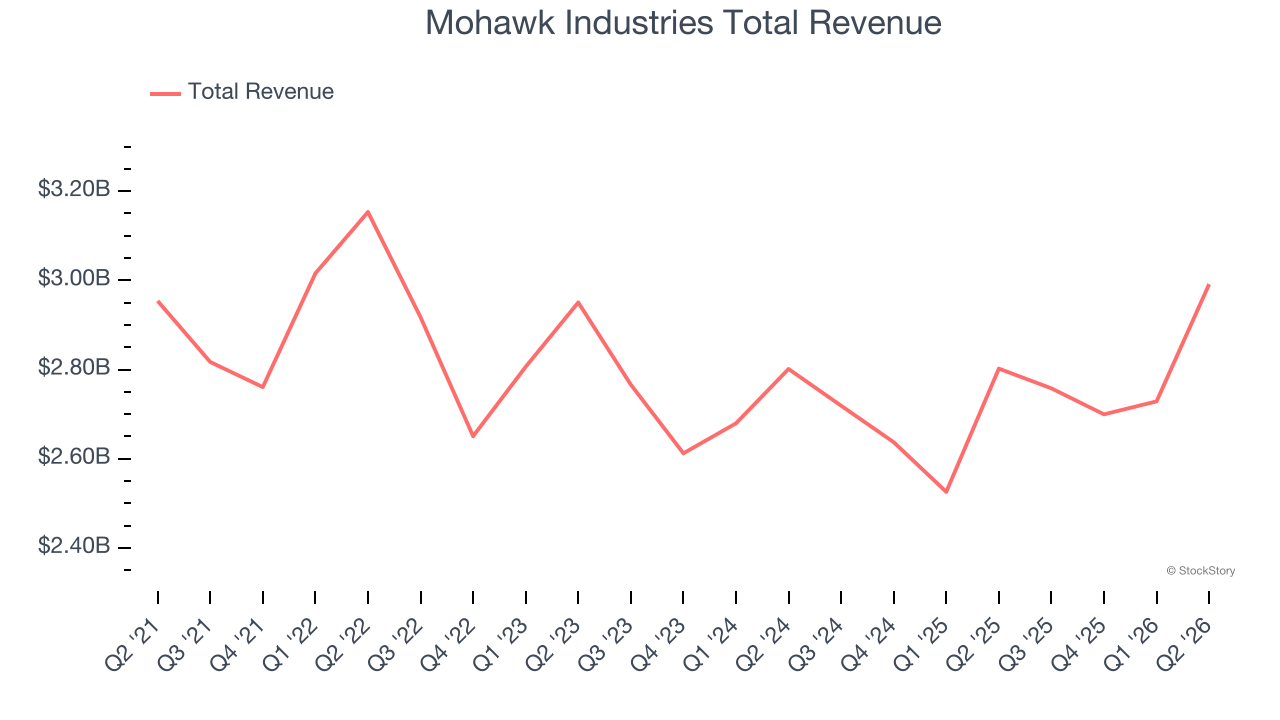
Mohawk Industries delivered the biggest analyst estimate beat and fastest revenue growth in the group. The market seems content with the results as the stock is up 4.7% since reporting. It currently trades at $125.18.
Is now the time to buy Mohawk Industries? Access our full analysis of the earnings results here, it’s free.
Weakest Q2: Lovesac (NASDAQ: LOVE)
Known for its oversized, premium beanbags, Lovesac (NASDAQ: LOVE) is a specialty furniture brand selling modular furniture.
Lovesac reported revenues of $161.2 million, flat year on year, in line with analysts’ expectations. It was a softer quarter as it posted full-year EBITDA guidance missing analysts’ expectations.
As expected, the stock is down 6.3% since the results and currently trades at $15.02.
Read our full analysis of Lovesac’s results here.
Purple (NASDAQ: PRPL)
Founded by two brothers, Purple (NASDAQ: PRPL) creates sleep and home comfort products such as mattresses, pillows, and bedding accessories.
Purple reported revenues of $98.27 million, down 6.5% year on year. This result missed analysts’ expectations by 4.1%. Taking a step back, it was a mixed quarter as it also logged a beat of analysts’ EPS estimates but full-year revenue guidance missing analysts’ expectations.
Purple had the weakest performance against analyst estimates, slowest revenue growth, and weakest full-year guidance update among its peers. The stock is down 76.5% since reporting and currently trades at $2.14.
Read our full, actionable report on Purple here, it’s free.
Market Update
Over the past year, investors have been forced to repeatedly answer the same question: what is the market’s biggest risk? The answer has changed several times, and each shift has reshaped market leadership.
Late in 2025 and early 2026, artificial intelligence became the market’s primary uncertainty. Investors questioned whether AI would erode software pricing power and weaken competitive moats as AI made it easier to replicate once-differentiated products.
By the spring, technology took a back seat to geopolitics. The U.S. conflict with Iran briefly became the market’s dominant narrative, raising concerns about oil prices, inflation, and global growth. But as energy markets remained orderly and fears of a prolonged supply disruption faded, investors quickly turned their focus back to fundamentals.
Want to invest in winners with rock-solid fundamentals? Check out our 9 Best Market-Beating Stocks and add them to your watchlist. These companies are poised for growth regardless of the political or macroeconomic climate.