The end of an earnings season can be a great time to discover new stocks and assess how companies are handling the current business environment. Let’s take a look at how PNC Financial Services Group (NYSE: PNC) and the rest of the diversified banks stocks fared in Q3.
At their core, diversified banks take in deposits and engage in various forms of lending, which means revenue is generated through interest rate spreads (difference between loan and deposit rates) and fees. Other revenue comes from adjacent services such as wealth management, card and account fees, and products such as annuities. These institutions benefit from rising interest rates that improve NIMs (net interest margins), digital transformation reducing operational costs, and expanding wealth management services as populations age. However, they face headwinds including fintech competition disrupting traditional models (how disruptive is crypto?), stringent regulatory requirements increasing compliance costs, and cybersecurity threats requiring substantial technology investments. Economic downturns also pose risks through potential loan defaults and compressed margins during accommodative monetary policy periods.
The 7 diversified banks stocks we track reported a slower Q3. As a group, revenues missed analysts’ consensus estimates by 0.7%.
In light of this news, share prices of the companies have held steady. On average, they are relatively unchanged since the latest earnings results.
PNC Financial Services Group (NYSE: PNC)
Tracing its roots back to 1852 when Pittsburgh's industrial boom demanded stronger financial institutions, PNC (NYSE: PNC) is a diversified financial institution that provides retail banking, corporate banking, and asset management services through a coast-to-coast branch network.
PNC Financial Services Group reported revenues of $6.62 billion, up 10.7% year on year. This print was in line with analysts’ expectations, but overall, it was a mixed quarter for the company with an impressive beat of analysts’ tangible book value per share estimates but a slight miss of analysts’ net interest income estimates.
From Bill Demchak, PNC Chairman and Chief Executive Officer:"Our strategy continues to drive growth across our businesses, as we deepen our presence in key markets and expand our reach nationally. During the third quarter, we continued to build on the strong momentum we delivered in the first half of the year, and we generated an 18.3% return on average tangible common equity. We are well positioned, and remain confident in our long-term outlook."
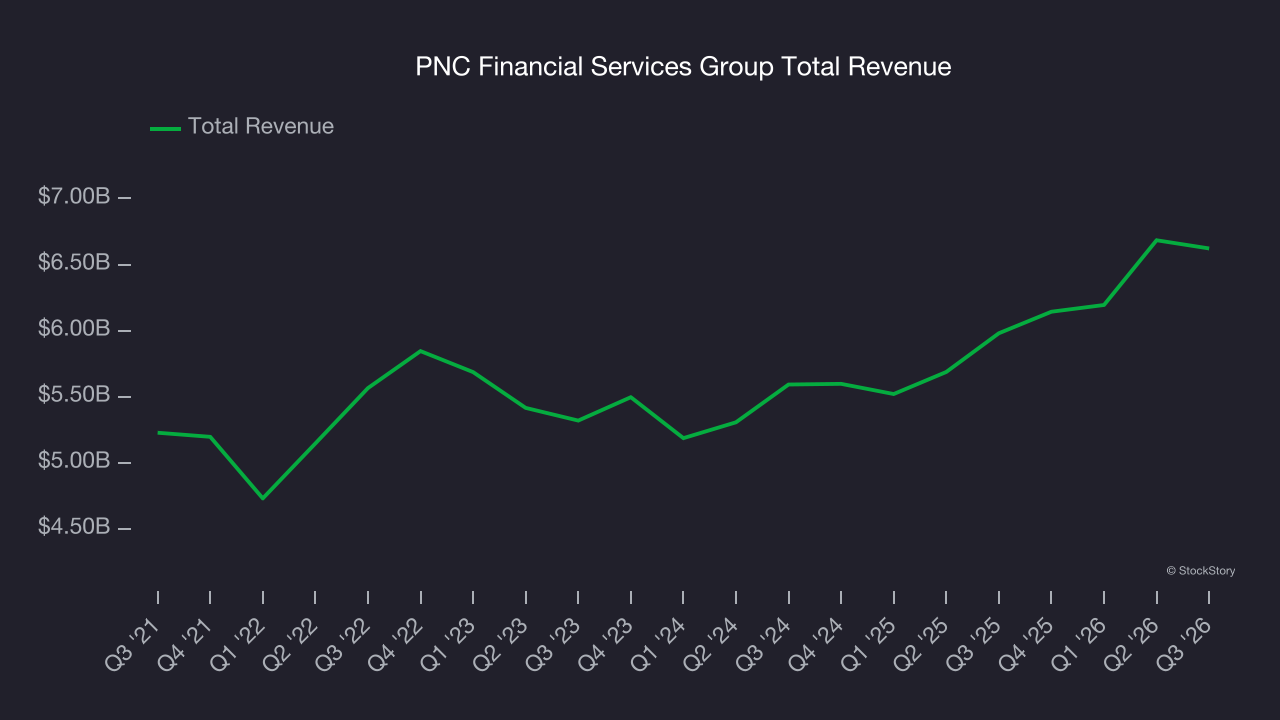
PNC Financial Services Group achieved the fastest revenue growth among its peers. Unsurprisingly, the stock is up 3.3% since reporting and currently trades at $223.
Is now the time to buy PNC Financial Services Group? Access our full analysis of the earnings results here, it’s free.
Best Q3: Citigroup (NYSE: C)
With operations in nearly 160 countries and a history dating back to 1812, Citigroup (NYSE: C) is a global financial services company that provides banking, investment, wealth management, and payment solutions to consumers, corporations, and governments.
Citigroup reported revenues of $23.87 billion, up 7.9% year on year, outperforming analysts’ expectations by 0.6%. The business had a strong quarter with a solid beat of analysts’ net interest income estimates and a beat of analysts’ EPS estimates.
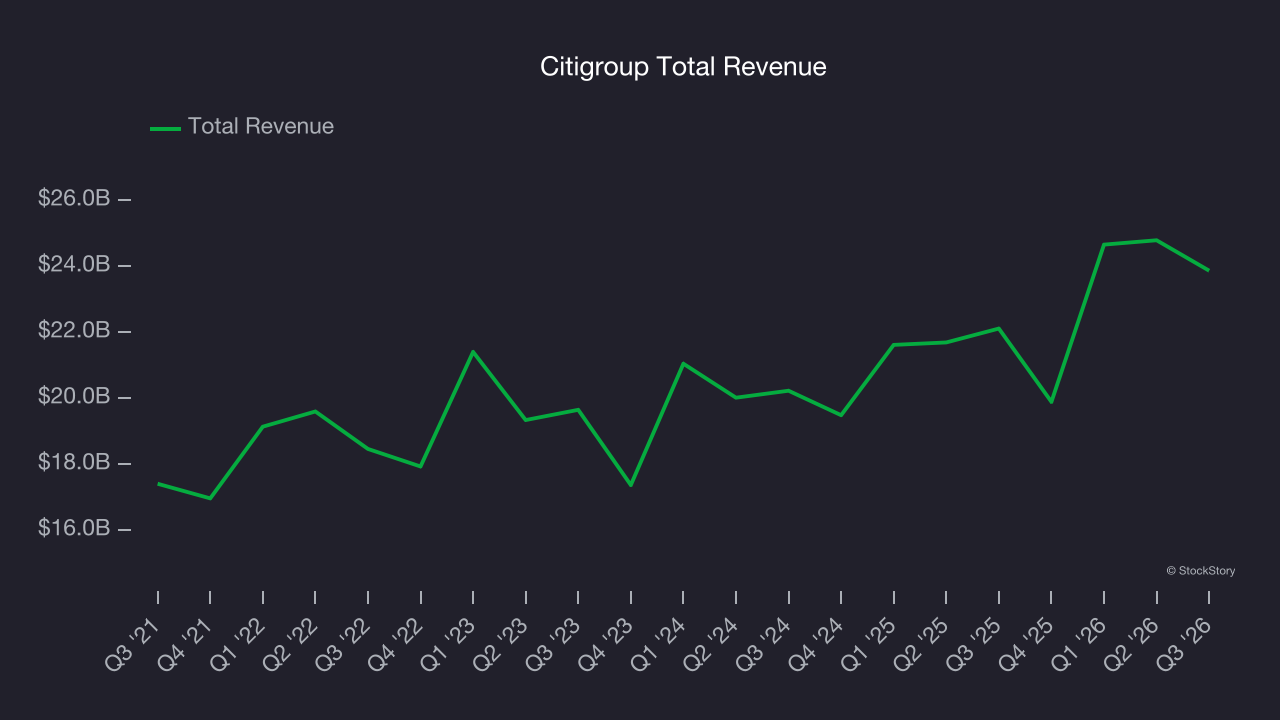
Citigroup pulled off the biggest analyst estimate beat of the whole group. Although it had a fine quarter compared to its peers, the market seems unhappy with the results as the stock is down 6.5% since reporting. It currently trades at $123.30.
Is now the time to buy Citigroup? Access our full analysis of the earnings results here, it’s free.
Weakest Q3: Wells Fargo (NYSE: WFC)
Founded during the California Gold Rush in 1852 to provide banking and express delivery services to miners and merchants, Wells Fargo (NYSE: WFC) is a diversified financial services company that provides banking, lending, investment, and wealth management services to individuals and businesses.
Wells Fargo reported revenues of $21.94 billion, up 2% year on year, falling short of analysts’ expectations by 1.7%. It was a softer quarter as it posted a miss of analysts’ tangible book value per share estimates and a miss of analysts’ EPS estimates.
Wells Fargo delivered the weakest performance against analyst estimates in the group. As expected, the stock is down 1.3% since the results and currently trades at $82.25.
Read our full analysis of Wells Fargo’s results here.
U.S. Bancorp (NYSE: USB)
With roots dating back to 1863 and a presence across 26 states primarily in the Midwest and West, U.S. Bancorp (NYSE: USB) is one of America's largest banks providing lending, deposit services, wealth management, payment processing, and merchant services to individuals and businesses.
U.S. Bancorp reported revenues of $8.04 billion, up 9.5% year on year. This result was in line with analysts’ expectations. More broadly, it was a slower quarter as it logged a significant miss of analysts’ tangible book value per share estimates and net interest income in line with analysts’ estimates.
The stock is up 4.9% since reporting and currently trades at $59.01.
Read our full, actionable report on U.S. Bancorp here, it’s free.
Bank of America (NYSE: BAC)
Tracing its roots back to 1784 and now serving approximately 67 million consumer and small business clients, Bank of America (NYSE: BAC) is a global financial institution that provides banking, investing, asset management, and risk management products and services to individuals, businesses, and governments.
Bank of America reported revenues of $30.1 billion, up 3.1% year on year. This print lagged analysts’ expectations by 1.5%. Overall, it was a softer quarter as it also recorded a significant miss of analysts’ EPS estimates and a slight miss of analysts’ tangible book value per share estimates.
The stock is down 6.1% since reporting and currently trades at $50.68.
Read our full, actionable report on Bank of America here, it’s free.
Market update
Over the past year, investors have been forced to repeatedly answer the same question: what is the market’s biggest risk? The answer has changed several times, and each shift has reshaped market leadership.
Late in 2025 and early 2026, artificial intelligence became the market’s primary uncertainty. Investors questioned whether AI would erode software pricing power and weaken competitive moats as AI made it easier to replicate once-differentiated products.
By the spring, technology took a back seat to geopolitics. The U.S. conflict with Iran briefly became the market’s dominant narrative, raising concerns about oil prices, inflation, and global growth. But as energy markets remained orderly and fears of a prolonged supply disruption faded, investors quickly turned their focus back to fundamentals.
Want to invest in winners with rock-solid fundamentals? Check out our 9 Best Market-Beating Stocks and add them to your watchlist. These companies are poised for growth regardless of the political or macroeconomic climate.