Over the last six months, Lattice Semiconductor’s shares have sunk to $95.86, producing a disappointing 18.8% loss - a stark contrast to the S&P 500’s 9.1% gain. This may have investors wondering how to approach the situation.
Is there a buying opportunity in Lattice Semiconductor, or does it present a risk to your portfolio? Get the full stock story straight from our expert analysts, it’s free.
Why is Lattice Semiconductor not exciting?
Even though the stock has become cheaper, we don’t have much confidence in Lattice Semiconductor. Here are three reasons we avoid LSCC, plus one stock we’d rather own.
1. Lackluster revenue growth
Long-term growth is the most important, but short-term results matter for semiconductors because the rapid pace of technological innovation (Moore’s Law) could make yesterday’s hit product obsolete today. Lattice Semiconductor’s recent performance shows its demand has slowed as its annualized revenue growth of 1.9% over the last two years was below its five-year trend. We’re wary when companies in the sector see decelerations in revenue growth, as it could signal changing consumer tastes aided by low switching costs. 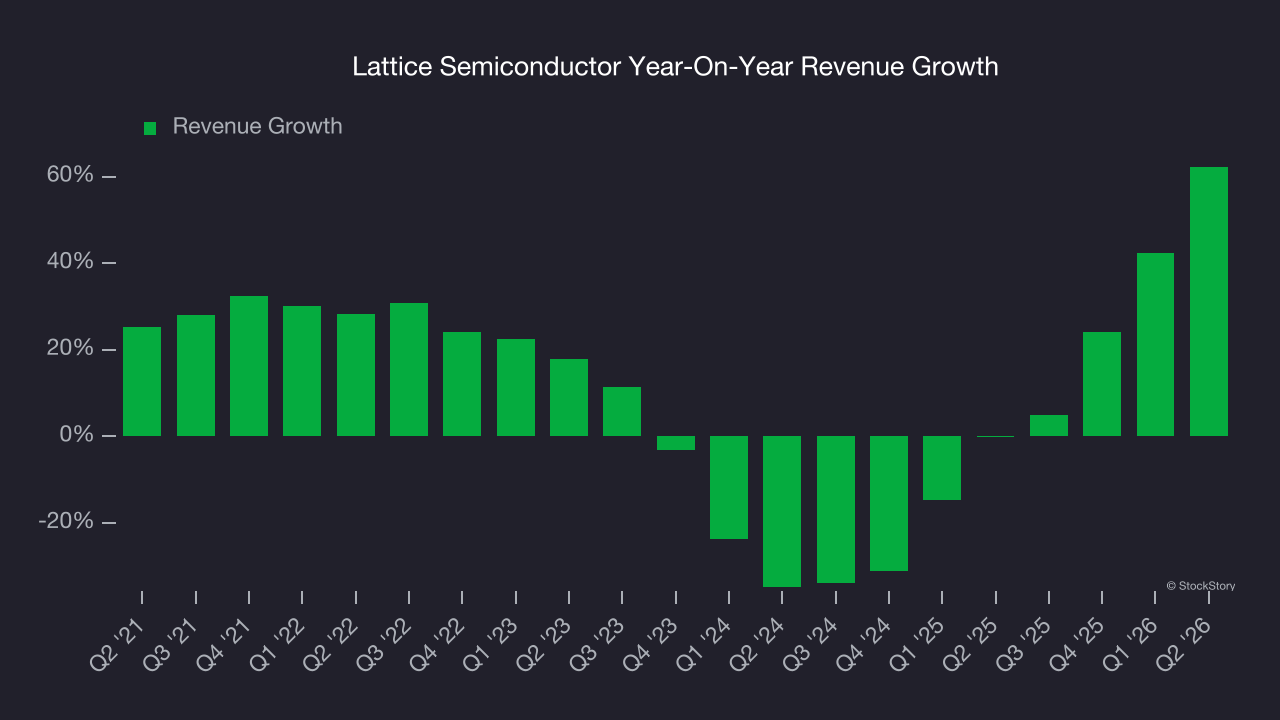
2. Shrinking operating margin
Operating margin is one of the best measures of profitability because it tells us how much money a company takes home after procuring and manufacturing its products, marketing and selling those products, and most importantly, keeping them relevant through research and development.
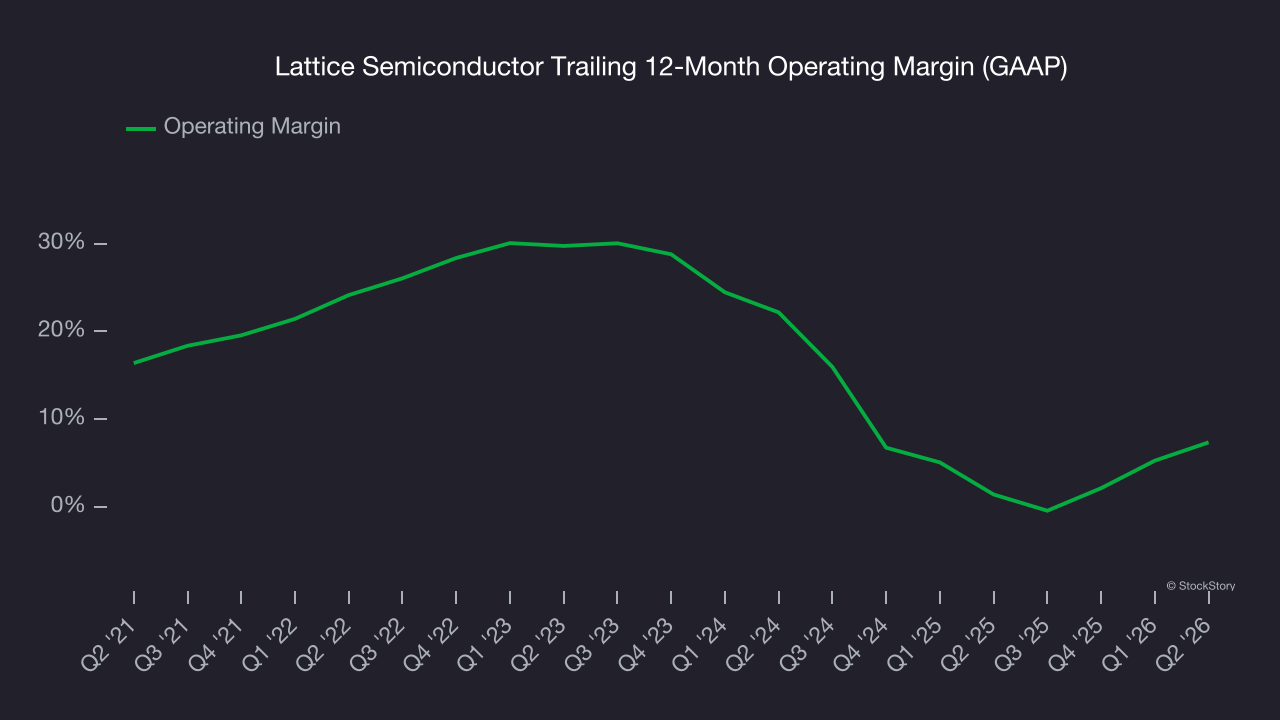
Analyzing the trend in its profitability, Lattice Semiconductor’s operating margin decreased by 16.8 percentage points over the last five years. This raises questions about the company’s expense base because its revenue growth should have given it leverage on its fixed costs, resulting in better economies of scale and profitability. Lattice Semiconductor’s performance was poor no matter how you look at it - it shows that costs were rising and it couldn’t pass them onto its customers. Its operating margin for the trailing 12 months was 7.4%.
3. Free cash flow margin stuck in neutral
If you’ve followed StockStory for a while, you know we emphasize free cash flow. Why, you ask? We believe that in the end, cash is king, and you can’t use accounting profits to pay the bills.
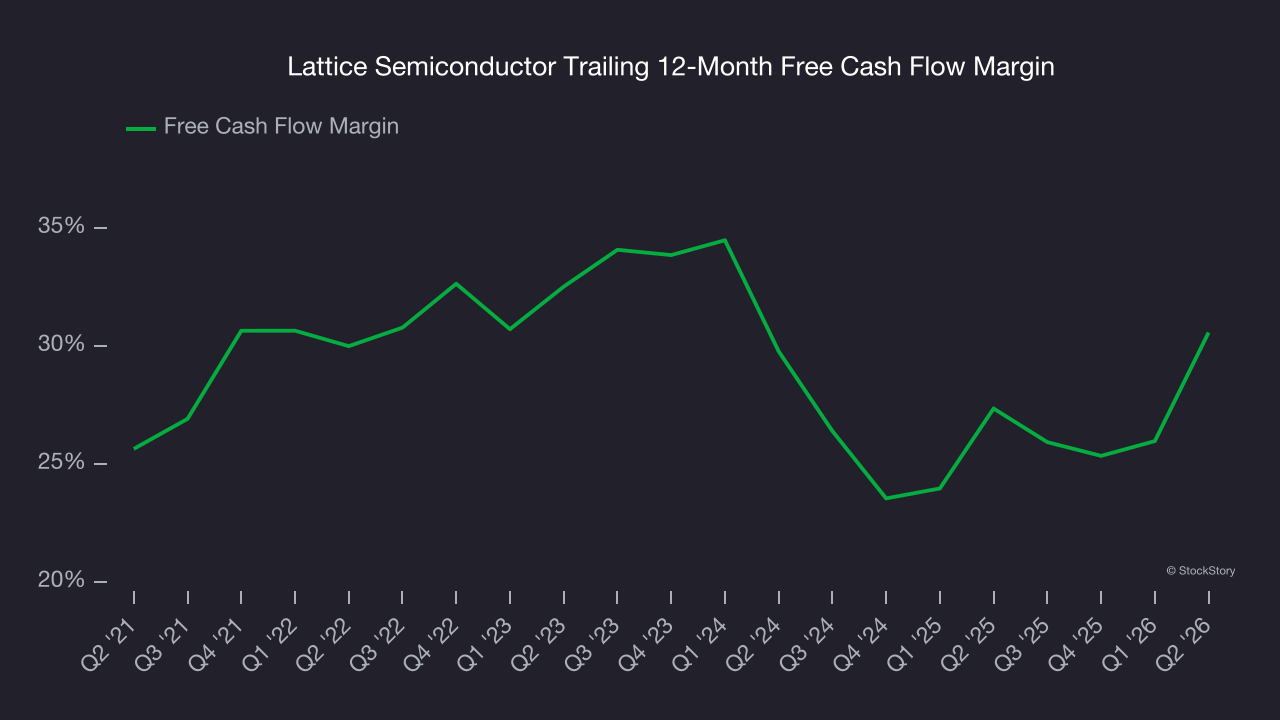
As you can see below, Lattice Semiconductor’s margin was unchanged over the last five years, showing it couldn’t improve. Its free cash flow margin for the trailing 12 months was 30.6%.
Final judgment
Lattice Semiconductor isn’t a terrible business, but it doesn’t pass our quality test. Following the recent decline, the stock trades at 40.2× forward P/E (or $95.86 per share). While this valuation is fair, the upside isn’t great compared to the potential downside. We’re pretty confident there are more exciting stocks to buy at the moment. Let us point you toward the Amazon and PayPal of Latin America.
High-quality stocks for all market conditions
ONE MORE THING: Top 5 Growth Stocks. The biggest stock winners almost always had one thing in common before they ran. Revenue growing like crazy. Meta. CrowdStrike. Broadcom. Our AI flagged all three. They returned 315%, 314%, and 455%, respectively.
Find out which 5 stocks it’s flagging this month — FREE. Get Our Top 5 Growth Stocks for Free HERE.
Stocks that have made our list include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-micro-cap company Kadant (+214% between June 2020 and June 2025). Find your next big winner with StockStory today.