Carnival’s 16.8% return over the past six months has outpaced the S&P 500 by 11.6%, and its stock price has climbed to $30.00 per share. This performance may have investors wondering how to approach the situation.
Is now the time to buy Carnival, or should you be careful about including it in your portfolio? Get the full breakdown from our expert analysts, it’s free.
Why do we think Carnival will underperform?
Despite the momentum, we’re sitting this one out for now. Here are three reasons we avoid CCL, plus one stock we’d rather own.
1. Weak growth in passenger cruise days points to soft demand
Revenue growth can be broken down into changes in price and volume (for companies like Carnival, our preferred volume metric is passenger cruise days). While both are important, the latter is the most critical to analyze because prices have a ceiling.
Carnival’s passenger cruise days came in at 27.9 million in the latest quarter, and over the last two years, averaged 1.3% year-on-year growth. This performance was underwhelming and suggests it might have to lower prices or invest in product improvements to accelerate growth, factors that can hinder near-term profitability. 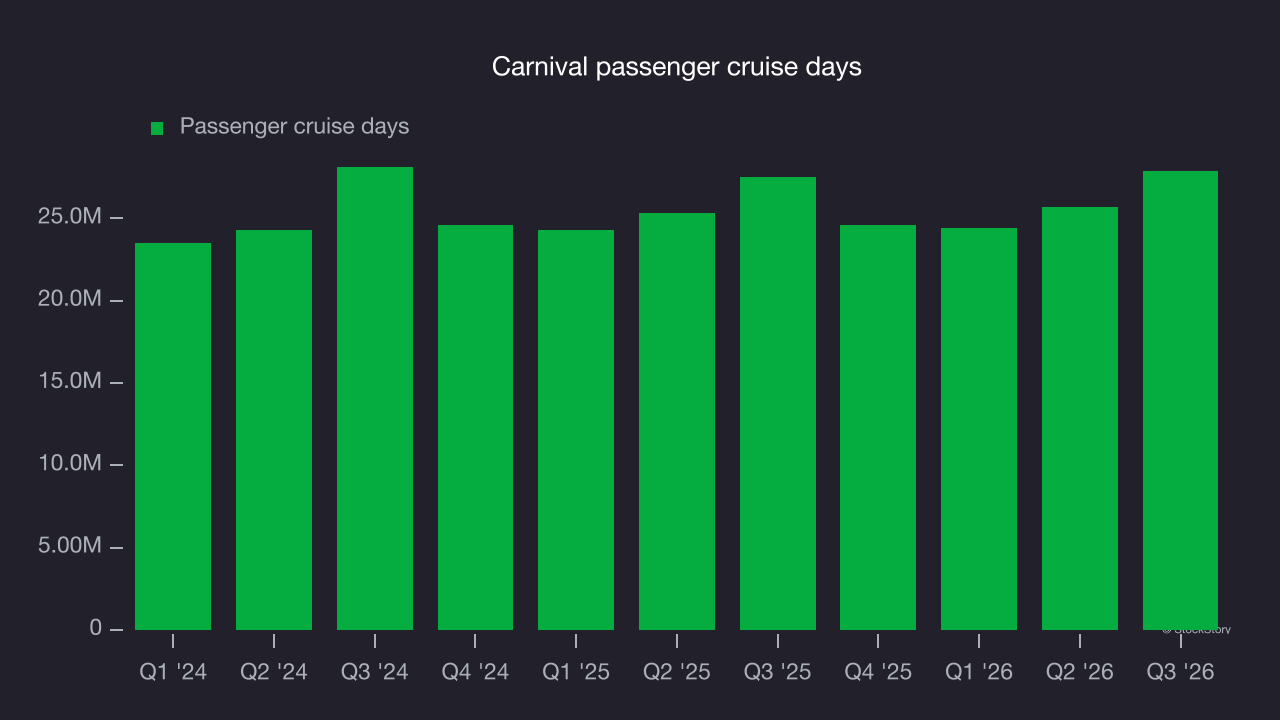
2. Cash flow margin set to decline
Free cash flow isn’t a prominently featured metric in company financials and earnings releases, but we think it’s telling because it accounts for all operating and capital expenses, making it tough to manipulate. Cash is king.
Over the next year, analysts predict Carnival’s cash conversion will slightly fall. Their consensus estimates, according to S&P, imply its free cash flow margin of 11.5% for the last 12 months will decrease to 10.6%.
3. Previous growth initiatives haven’t impressed
Growth gives us insight into a company’s long-term potential, but how capital-efficient was that growth? Enter ROIC, a metric showing how much operating profit a company generates relative to the money it has raised (debt and equity).
Carnival historically did a mediocre job investing in profitable growth initiatives. Its five-year average ROIC was 3.7%, lower than the typical cost of capital (how much it costs to raise money) for consumer discretionary companies.
Final judgment
Carnival doesn’t pass our quality test. With its shares topping the market in recent months, the stock trades at 12.1× forward P/E (or $30.00 per share). This valuation is reasonable, but the company’s shaky fundamentals present too much downside risk. There are better stocks to buy right now. We’d recommend looking at a top digital advertising platform riding the creator economy.
Stocks we like more than Carnival
ALSO WORTH WATCHING: Top 5 Momentum Stocks. The best time to own a great stock is when the market is finally noticing it. These aren’t just high-quality businesses. Something is happening with them right now. Elite fundamentals meet near-term momentum — both boxes checked at the same time.
Find out which stocks our AI platform is flagging this week. See this week’s Strong Momentum stocks — FREE. Get Our Strong Momentum Stocks for Free HERE.
Stocks that have made our list include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-small-cap company Exlservice (+271% between June 2020 and June 2025). Find your next big winner with StockStory today.