Over the past six months, Chemed has been a great trade, beating the S&P 500 by 21.8%. Its stock price has climbed to $536.01, representing a healthy 26.3% increase. This was partly thanks to its solid quarterly results, and the run-up might have investors contemplating their next move.
Is now the time to buy Chemed, or should you be careful about including it in your portfolio? Get the full stock story straight from our expert analysts, it’s free.
Why is Chemed not exciting?
We’re glad investors have benefited from the price increase, but we’re passing on Chemed for now. Here are three reasons you should be careful with CHE, plus one stock we’d rather own.
1. Long-term revenue growth disappoints
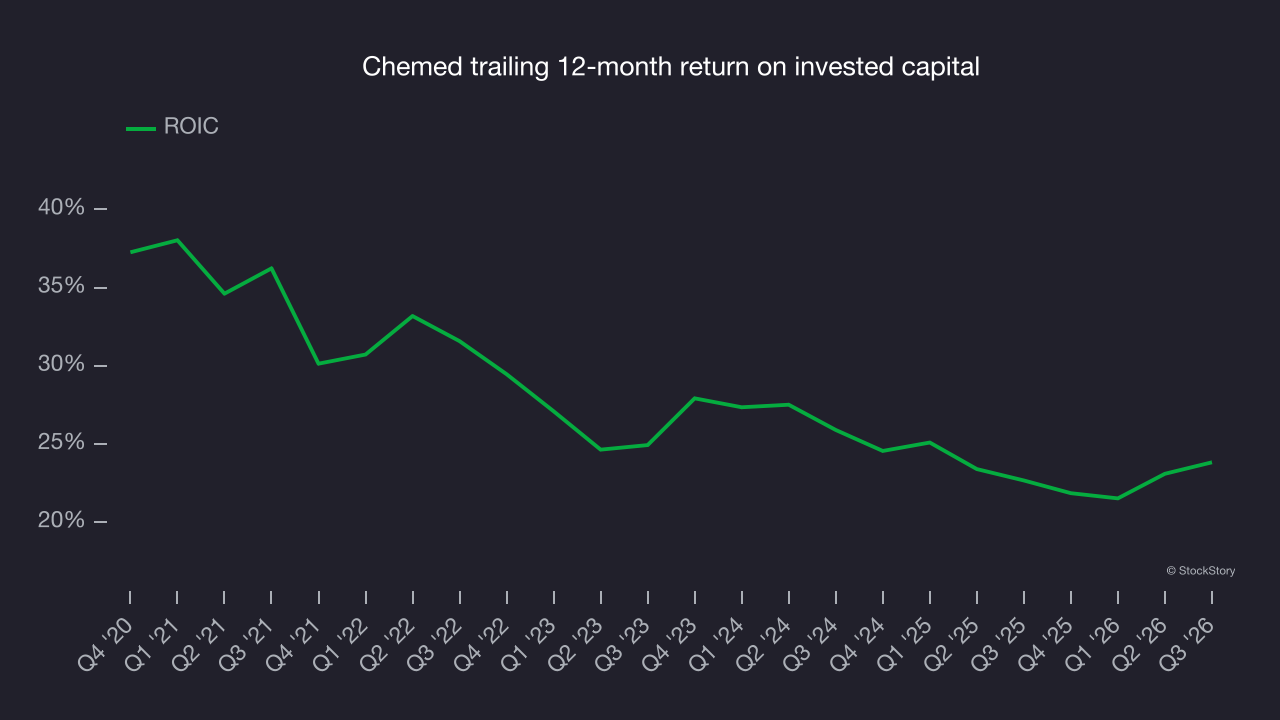
A company’s long-term sales performance can indicate its overall quality. Any business can experience short-term success, but top-performing ones enjoy sustained growth for years. Unfortunately, Chemed’s 4.5% annualized revenue growth over the last five years was mediocre. This fell short of our benchmark for the healthcare sector.
2. Shrinking adjusted operating margin
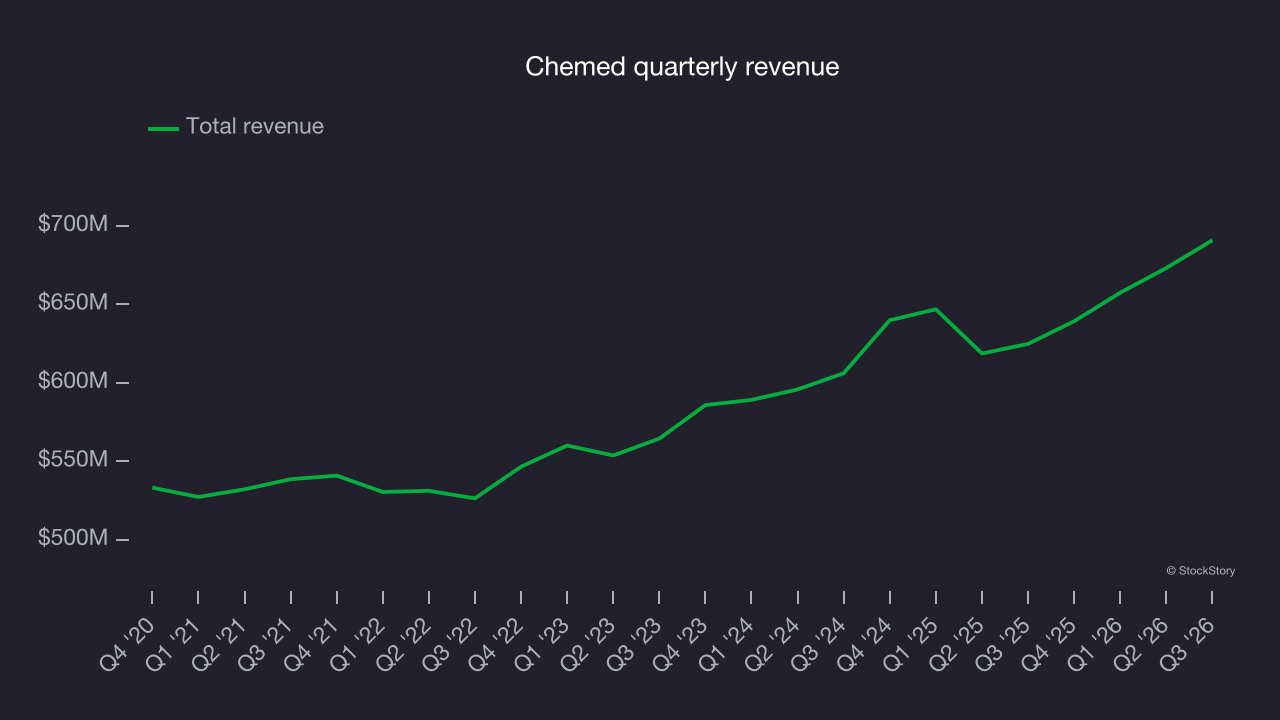
Adjusted operating margin is one of the best measures of profitability because it tells us how much money a company takes home after subtracting all core expenses, like marketing and R&D. It also removes various one-time costs to paint a better picture of normalized profits.
Analyzing the trend in its profitability, Chemed’s adjusted operating margin decreased by 3 percentage points over the last five years. This raises questions about the company’s expense base because its revenue growth should have given it leverage on its fixed costs, resulting in better economies of scale and profitability. Its adjusted operating margin for the trailing 12 months was 13.9%.
3. New investments fail to bear fruit as ROIC declines
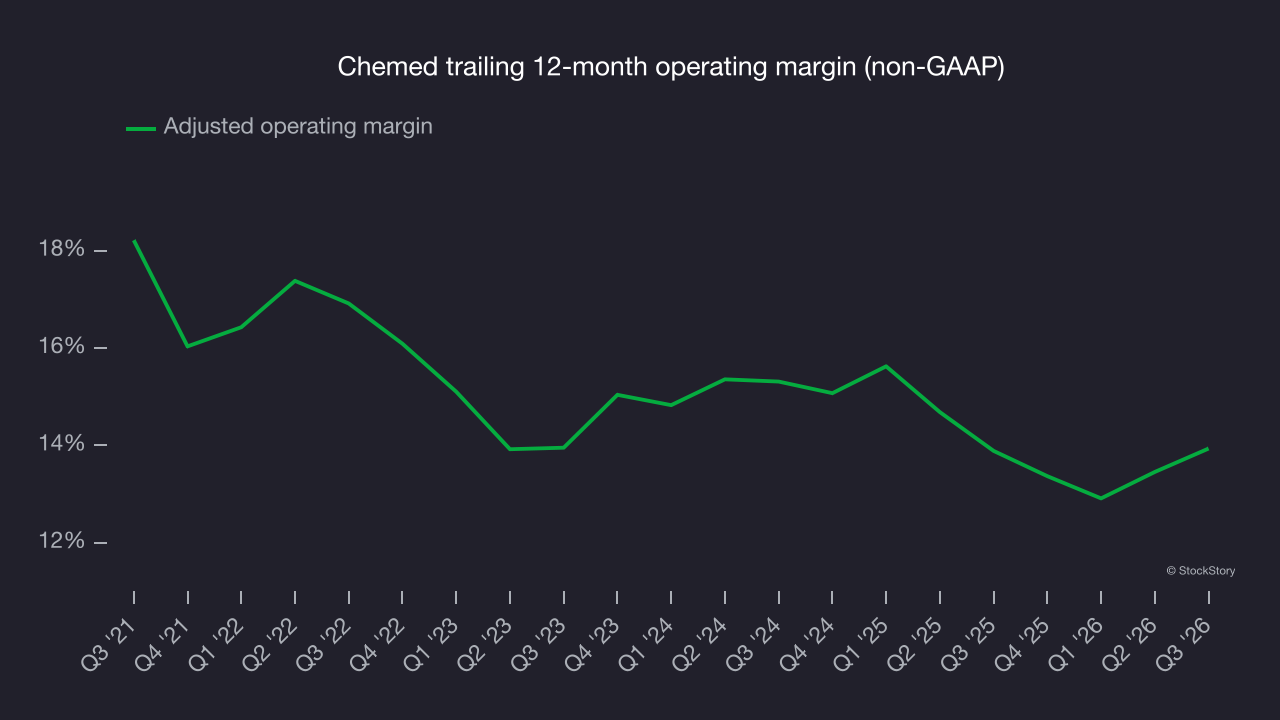
We like to invest in businesses with high returns, but the trend in a company’s ROIC can also be an early indicator of future business quality.
Over the last few years, Chemed’s ROIC has unfortunately decreased. We like what management has done in the past, but its declining returns are perhaps a symptom of fewer profitable growth opportunities.
Final judgment
Chemed isn’t a terrible business, but it doesn’t pass our bar. With its shares beating the market recently, the stock trades at 20.3× forward P/E (or $536.01 per share). While this valuation is fair, the upside isn’t great compared to the potential downside. We’re pretty confident there are superior stocks to buy right now. We’d recommend looking at a safe-and-steady industrials business benefiting from an upgrade cycle.
Stocks we like more than Chemed
ONE MORE THING: Top 5 Growth Stocks. The biggest stock winners almost always had one thing in common before they ran. Revenue growing like crazy. Meta. CrowdStrike. Broadcom. Our AI flagged all three. They returned 315%, 314%, and 455%, respectively.
Find out which 5 stocks it’s flagging this month — FREE. Get Our Top 5 Growth Stocks for Free HERE.
Stocks that have made our list include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-small-cap company Exlservice (+271% between June 2020 and June 2025). Find your next big winner with StockStory today.