Jacobs Solutions’s 15.2% return over the past six months has outpaced the S&P 500 by 10.7%, and its stock price has climbed to $145.83 per share. This run-up might have investors contemplating their next move.
Is now the time to buy Jacobs Solutions, or should you be careful about including it in your portfolio? Get the full stock story straight from our expert analysts, it’s free.
Why do we think Jacobs Solutions will underperform?
We’re glad investors have benefited from the price increase, but we’re passing on Jacobs Solutions for now. Here are three reasons we avoid J, plus one stock we’d rather own.
1. Revenue spiraling downwards
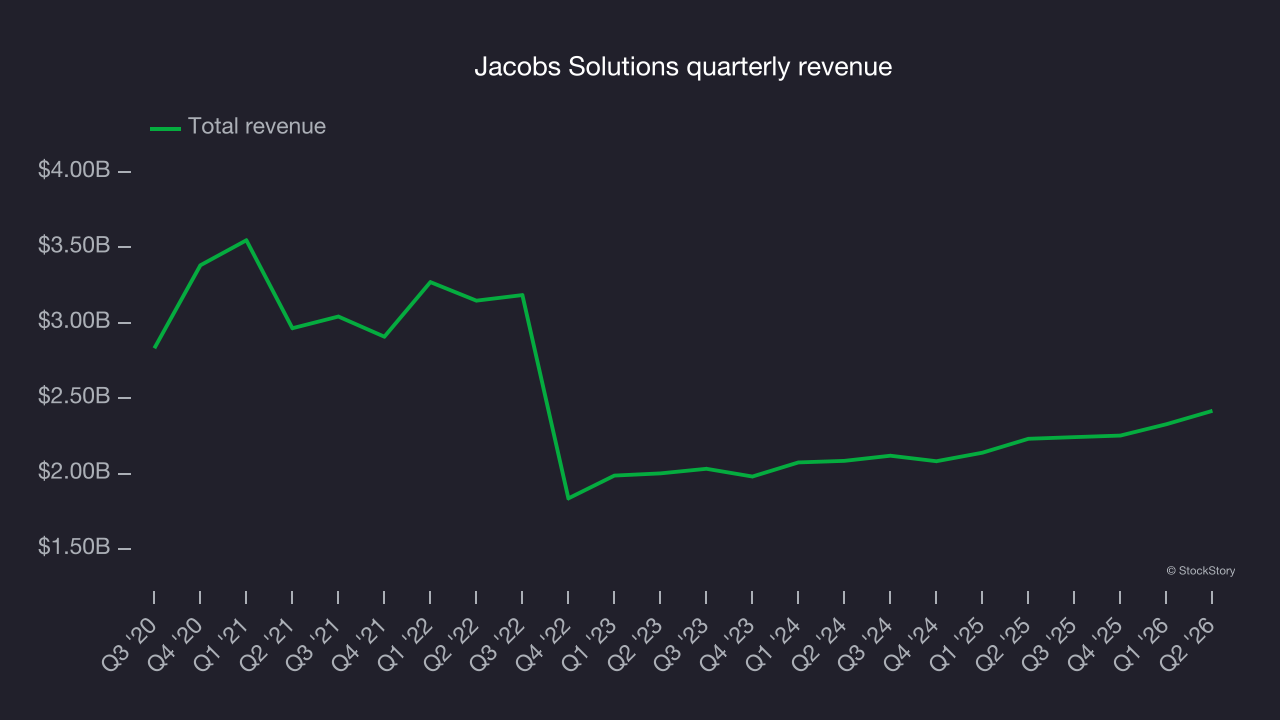
A company’s long-term performance is an indicator of its overall quality. Any business can put up a good quarter or two, but the best consistently grow over the long haul. Over the last five years, Jacobs Solutions’s demand was weak and its revenue declined by 6.2% per year. This wasn’t a great result and signals it’s a low quality business.
2. EPS barely growing
Analyzing the long-term change in earnings per share (EPS) shows whether a company’s incremental sales were profitable — for example, revenue could be inflated through excessive spending on advertising and promotions.
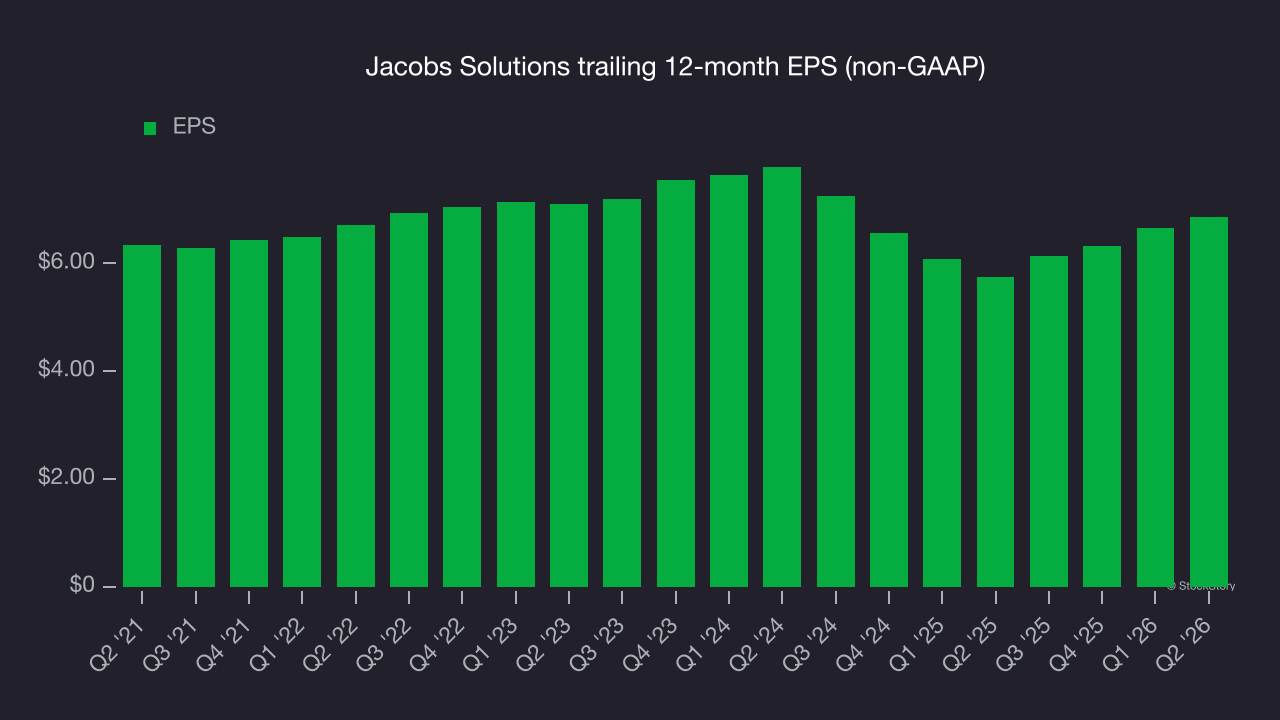
Jacobs Solutions’s EPS grew at 1.6% compounded annual growth rate over the last five years. On the bright side, this performance was better than its 6.2% annualized revenue declines and tells us management adapted its cost structure in response to a challenging demand environment.
3. Previous growth initiatives haven’t impressed
Growth gives us insight into a company’s long-term potential, but how capital-efficient was that growth? Enter ROIC, a metric showing how much operating profit a company generates relative to the money it has raised (debt and equity).
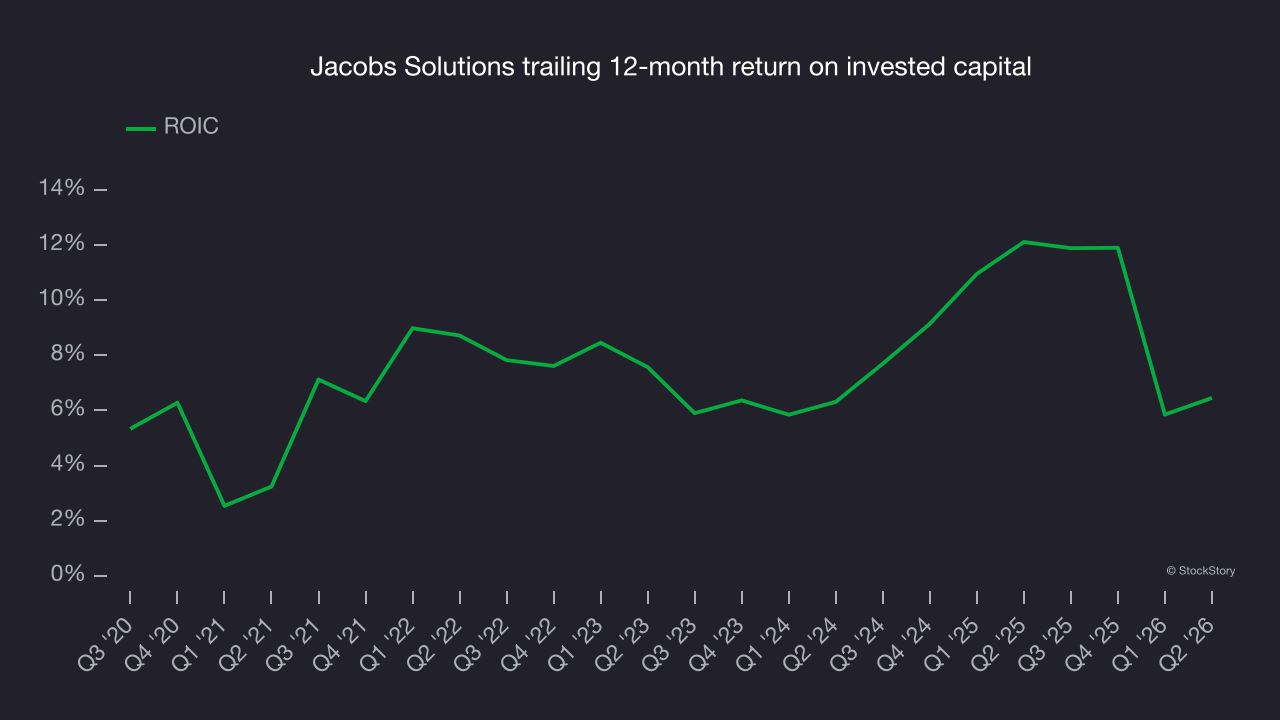
Jacobs Solutions historically did a mediocre job investing in profitable growth initiatives. Its five-year average ROIC was 8.2%, somewhat low compared to the best business services companies that consistently pump out 25%+.
Final judgment
We cheer for all companies making their customers lives easier, but in the case of Jacobs Solutions, we’ll be cheering from the sidelines. With its shares topping the market in recent months, the stock trades at 20.1× forward P/E (or $145.83 per share). This valuation tells us a lot of optimism is priced in - we think there are better stocks to buy right now. We’d suggest looking at one of our top software and edge computing picks.
Stocks we like more than Jacobs Solutions
ONE MORE THING: Top 5 Growth Stocks. The biggest stock winners almost always had one thing in common before they ran. Revenue growing like crazy. Meta. CrowdStrike. Broadcom. Our AI flagged all three. They returned 315%, 314%, and 455%, respectively.
Find out which 5 stocks it’s flagging this month — FREE. Get Our Top 5 Growth Stocks for Free HERE.
Stocks that have made our list include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-micro-cap company Tecnoglass (+1,552% between June 2020 and June 2025). Find your next big winner with StockStory today.