Over the last six months, AT&T’s shares have sunk to $21.75, producing a disappointing 14.9% loss - a stark contrast to the S&P 500’s 4.5% gain. This might have investors contemplating their next move.
Is now the time to buy AT&T, or should you be careful about including it in your portfolio? See what our analysts have to say in our full research report, it’s free.
Why do we think AT&T will underperform?
Even with the cheaper entry price, we don’t have much confidence in AT&T. Here are three reasons why there are better opportunities than T, plus one stock we’d rather own.
1. Long-term revenue growth flatter than a pancake
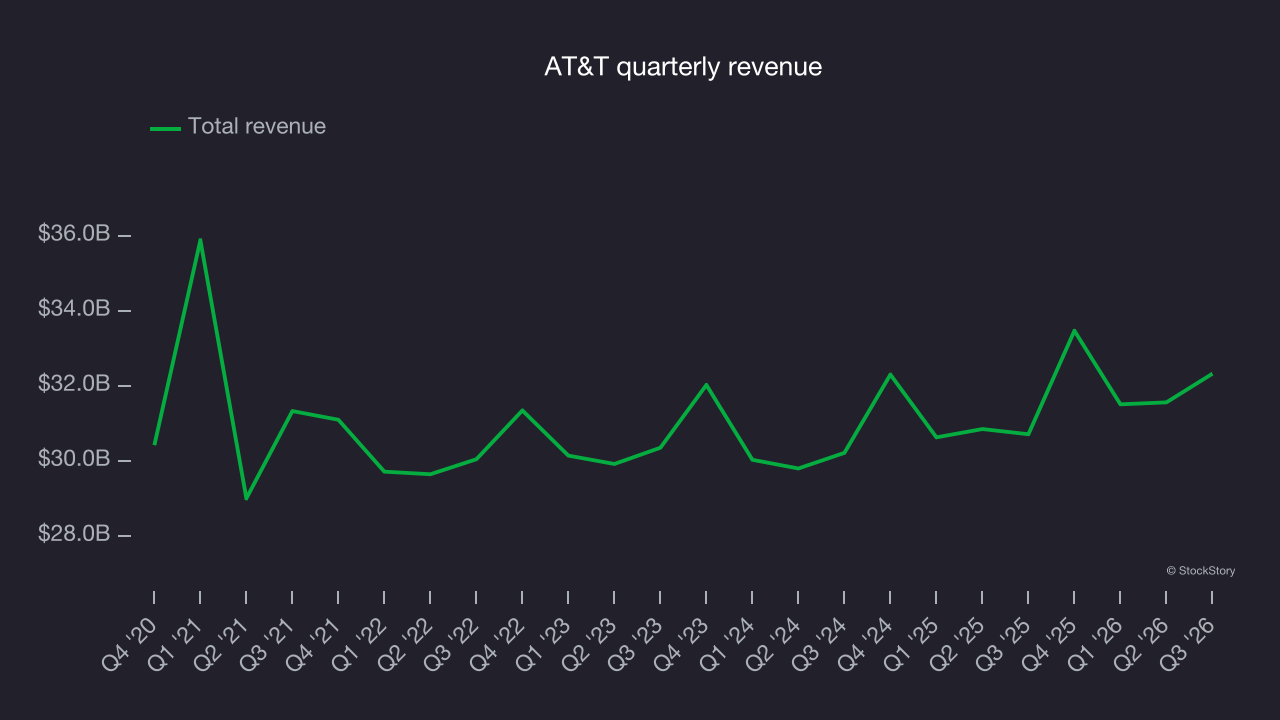
Examining a company’s long-term performance can provide clues about its quality. Any business can put up a good quarter or two, but the best consistently grow over the long haul. Unfortunately, AT&T struggled to consistently increase demand as its $128.9 billion of sales for the trailing 12 months was close to its revenue five years ago. This was below our standards and is a sign of poor business quality.
2. EPS trending down
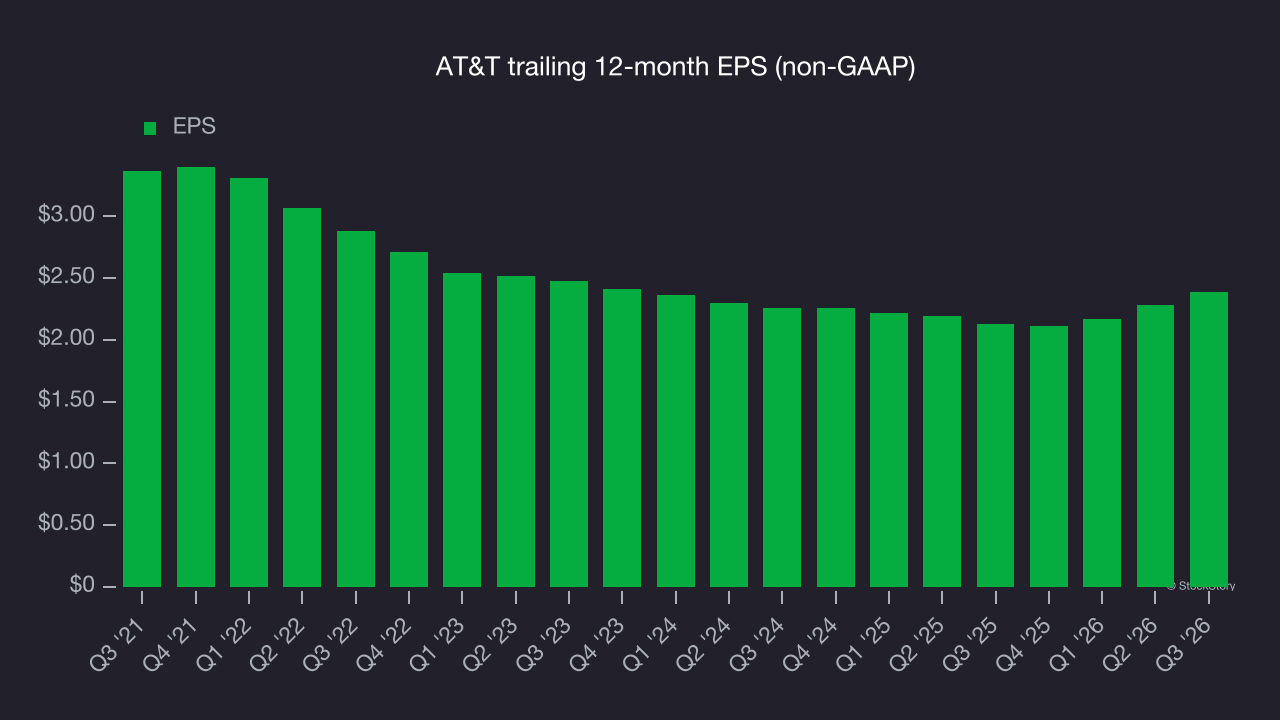
Analyzing the long-term change in earnings per share (EPS) shows whether a company’s incremental sales were profitable — for example, revenue could be inflated through excessive spending on advertising and promotions.
Sadly for AT&T, its EPS declined by 6.6% annually over the last five years while its revenue was flat. This tells us the company struggled because its fixed cost base made it difficult to adjust to choppy demand.
3. Free cash flow projections disappoint
If you’ve followed StockStory for a while, you know we emphasize free cash flow. Why, you ask? We believe that in the end, cash is king, and you can’t use accounting profits to pay the bills.
Over the next year, analysts’ consensus estimates, according to S&P, show they’re expecting AT&T’s free cash flow margin of 13.8% for the last 12 months to remain the same.
Final judgment
We cheer for all companies serving everyday consumers, but in the case of AT&T, we’ll be cheering from the sidelines. After the recent drawdown, the stock trades at 8.6× forward P/E (or $21.75 per share). While this valuation is optically cheap, the potential downside is huge given its shaky fundamentals. There are better investments elsewhere. We’d recommend looking at the most entrenched endpoint security platform on the market.
High-quality stocks for all market conditions
WHILE YOU’RE HERE: Top 9 Market-Beating Stocks. The best stocks don’t just beat the market once. They do it again. And again. Robust revenue growth, rising free cash flow, returns on capital that leave their competition in the dust. The market has already rewarded these businesses.
But our AI platform says the party isn’t over. Find out which 9 stocks made the cut this week — FREE. Get Our Top 9 Market-Beating Stocks for Free HERE.
Stocks that have made our list include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-small-cap company Comfort Systems (+1,154% between June 2020 and June 2025). Find your next big winner with StockStory today.