As the Q2 earnings season comes to a close, it’s time to take stock of this quarter’s best and worst performers in the business services & supplies industry, including Interface (NASDAQ: TILE) and its peers.
This is a sector that encompasses many types of business, and so it follows that a number of trends will impact the space. For industrial and environmental services companies, for example, trends around environmental compliance and increasing corporate ESG commitments matter while for safety and security services companies, the intersection of physical security, cybersecurity, and workplace safety regulations are the topics du jour. Broadly, AI and automation could be tailwinds for companies in the space that invest wisely. On the other hand, shifting regulatory frameworks could force continual changes in go-to-market and costly investments.
The 20 business services & supplies stocks we track reported a strong Q2. As a group, revenues beat analysts’ consensus estimates by 2.2% while next quarter’s revenue guidance was in line.
In light of this news, share prices of the companies have held steady. On average, they are relatively unchanged since the latest earnings results.
Interface (NASDAQ: TILE)
Pioneering carbon-neutral flooring since its founding in 1973, Interface (NASDAQ: TILE) is a global manufacturer of modular carpet tiles, luxury vinyl tile (LVT), and rubber flooring that specializes in carbon-neutral and sustainable flooring solutions.
Interface reported revenues of $395.7 million, up 5.4% year on year. This print exceeded analysts’ expectations by 1.4%. Overall, it was a strong quarter for the company with a beat of analysts’ EPS estimates and full-year revenue guidance meeting analysts’ expectations.
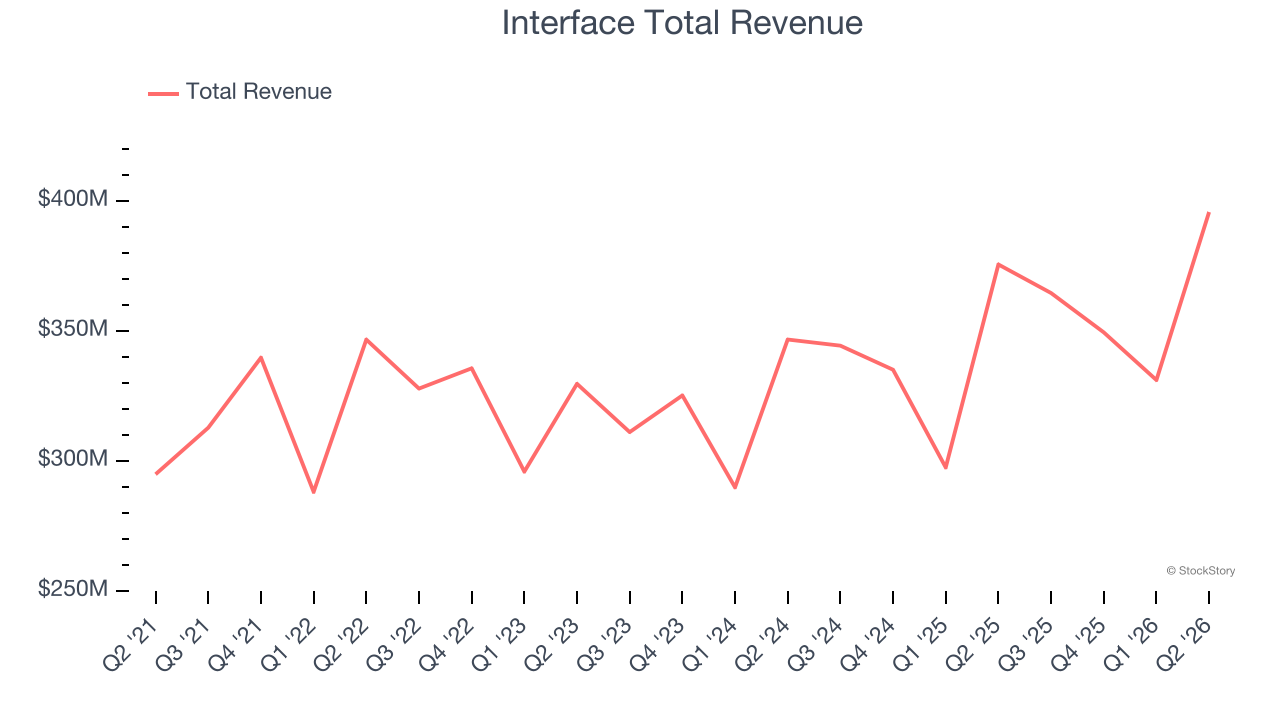
Investor expectations, however, were likely higher than Wall Street’s published projections, leaving some wishing for even better results (analysts’ consensus estimates are those published by big banks and advisory firms, not the investors who make buy and sell decisions). The stock is down 1.9% since reporting and currently trades at $34.42.
We think Interface is a good business, but is it a buy today? Read our full report here, it’s free.
Best Q2: OPENLANE (NYSE: OPLN)
Facilitating the sale of approximately 1.3 million used vehicles in 2023, OPENLANE (NYSE: OPLN) operates digital marketplaces that connect sellers and buyers of used vehicles across North America and Europe, facilitating wholesale transactions.
OPENLANE reported revenues of $554.6 million, up 15.1% year on year, outperforming analysts’ expectations by 4.4%. The business had a stunning quarter with a beat of analysts’ EPS estimates and a solid beat of analysts’ full-year EPS guidance estimates.
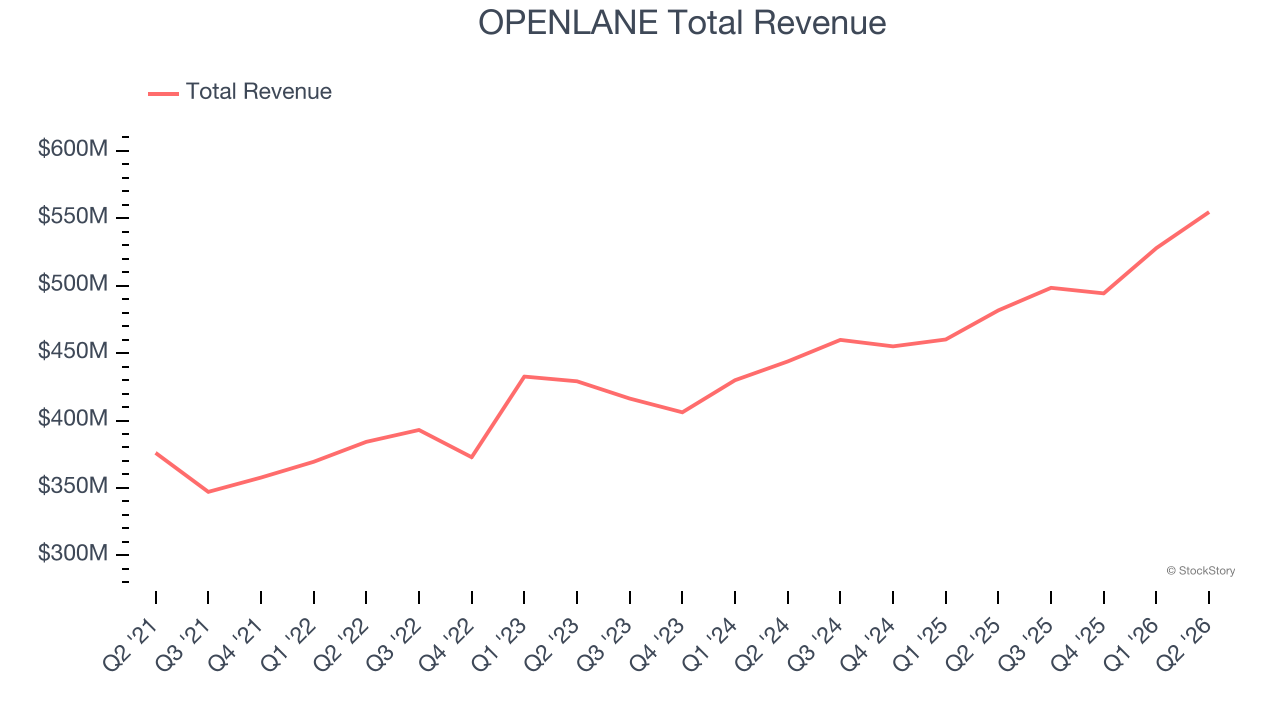
Although it had a fine quarter compared to its peers, the market seems unhappy with the results as the stock is down 13.8% since reporting. It currently trades at $35.50.
Is now the time to buy OPENLANE? Access our full analysis of the earnings results here, it’s free.
Weakest Q2: Copart (NASDAQ: CPRT)
Starting as a single salvage yard in California in 1982, Copart (NASDAQ: CPRT) operates an online auction platform that connects sellers of damaged and salvage vehicles with buyers ranging from dismantlers and rebuilders to used car dealers and exporters.
Copart reported revenues of $1.15 billion, up 2.4% year on year, exceeding analysts’ expectations by 1%. Still, it was a softer quarter as it posted a significant miss of analysts’ EPS estimates.
Interestingly, the stock is up 4.3% since the results and currently trades at $31.83.
Read our full analysis of Copart’s results here.
RB Global (NYSE: RBA)
Born from the 1958 founding of Ritchie Bros. Auctioneers and rebranded in 2023, RB Global (NYSE: RBA) operates global marketplaces that connect buyers and sellers of commercial assets, vehicles, and equipment across multiple industries.
RB Global reported revenues of $1.32 billion, up 11.1% year on year. This result surpassed analysts’ expectations by 6.8%. All in all, it was a strong quarter for the company.
The stock is down 24.5% since reporting and currently trades at $83.87.
Read our full, actionable report on RB Global here, it’s free.
Vestis (NYSE: VSTS)
Operating a network of more than 350 facilities with 3,300 delivery routes serving customers weekly, Vestis (NYSE: VSTS) provides uniform rentals, workplace supplies, and facility services to over 300,000 business locations across the United States and Canada.
Vestis reported revenues of $661.7 million, down 1.8% year on year. This number missed analysts’ expectations by 1.2%. Taking a step back, it was still a strong quarter as it produced a beat of analysts’ EPS estimates.
Vestis had the weakest performance against analyst estimates in the group. The stock is down 7.3% since reporting and currently trades at $12.85.
Read our full, actionable report on Vestis here, it’s free.
Market Update
Over the past year, investors have been forced to repeatedly answer the same question: what is the market’s biggest risk? The answer has changed several times, and each shift has reshaped market leadership.
Late in 2025 and early 2026, artificial intelligence became the market’s primary uncertainty. Investors questioned whether AI would erode software pricing power and weaken competitive moats as AI made it easier to replicate once-differentiated products.
By the spring, technology took a back seat to geopolitics. The U.S. conflict with Iran briefly became the market’s dominant narrative, raising concerns about oil prices, inflation, and global growth. But as energy markets remained orderly and fears of a prolonged supply disruption faded, investors quickly turned their focus back to fundamentals.
Want to invest in winners with rock-solid fundamentals? Check out our Top 5 Growth Stocks and add them to your watchlist. These companies are poised for growth regardless of the political or macroeconomic climate.