What a time it’s been for Atlanticus Holdings. In the past six months alone, the company’s stock price has increased by a massive 62.4%, reaching $90.92 per share. This was partly thanks to its solid quarterly results, and the run-up might have investors contemplating their next move.
Is now the time to buy Atlanticus Holdings, or should you be careful about including it in your portfolio? Dive into our full research report to see our analyst team’s opinion, it’s free.
Why Is Atlanticus Holdings Not Exciting?
Despite the momentum, we don’t have much confidence in Atlanticus Holdings. Here are two reasons you should be careful with ATLC, plus one stock we’d rather own.
1. EPS Growth Has Stalled
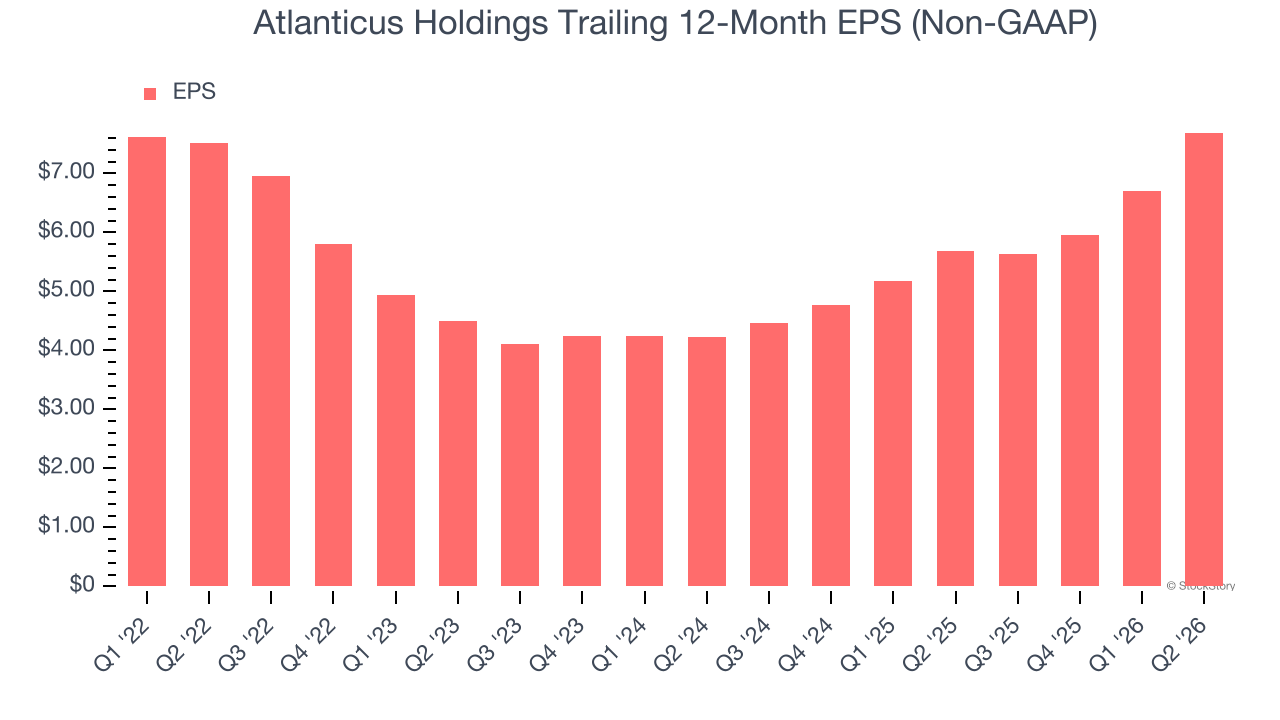
Analyzing the long-term change in earnings per share (EPS) shows whether a company’s incremental sales were profitable — for example, revenue could be inflated through excessive spending on advertising and promotions.
Atlanticus Holdings’s full-year EPS was flat over the last four years, worse than the broader financials sector.
2. High Debt Levels Increase Risk
Atlanticus Holdings reported $645.2 million of cash and $6.99 billion of debt on its balance sheet in the most recent quarter.
As investors in high-quality companies, we primarily focus on whether a company’s profits can support its debt.
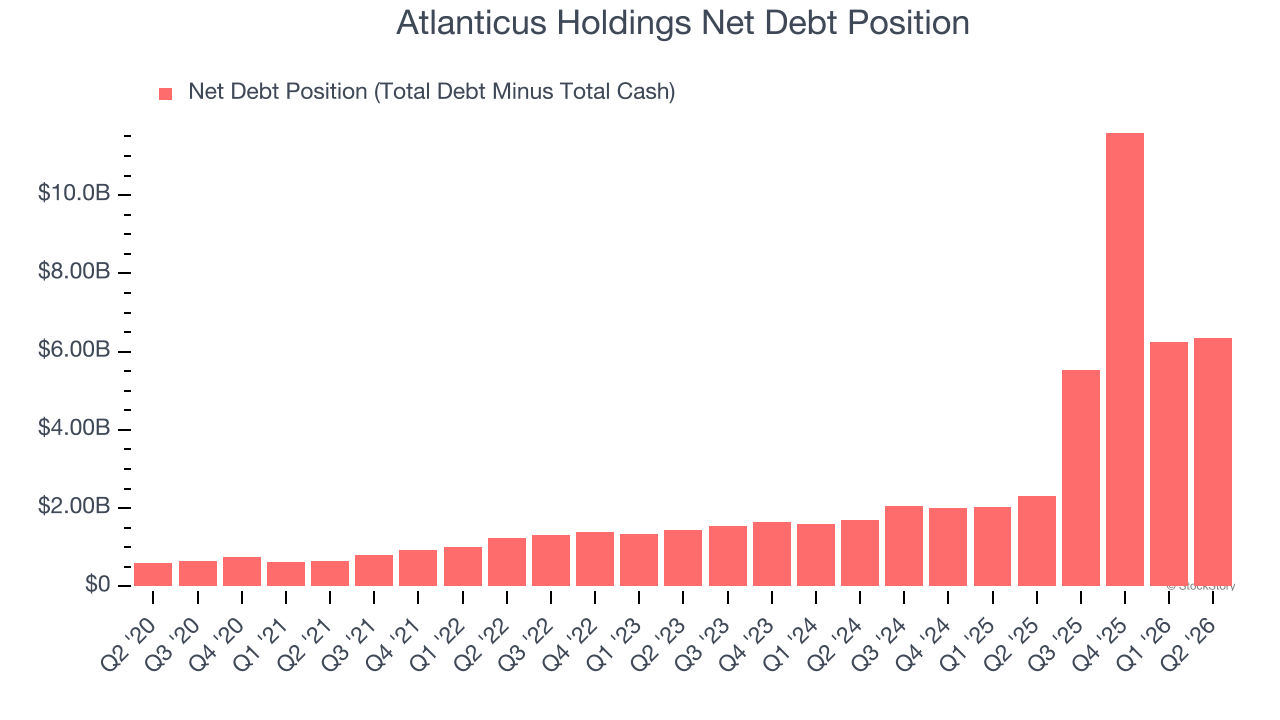
With $228.9 million of EBITDA over the last 12 months, we view Atlanticus Holdings’s 27.7× net-debt-to-EBITDA ratio as inadequate. The company’s lacking profits relative to its borrowings give it little breathing room, raising red flags.
Final Judgment
Atlanticus Holdings isn’t a terrible business, but it isn’t one of our picks. After the recent surge, the stock trades at 8.2× forward P/E (or $90.92 per share). This valuation is reasonable, but the company’s shakier fundamentals present too much downside risk. We’re pretty confident there are superior stocks to buy right now. We’d suggest looking at one of our all-time favorite software stocks.
High-Quality Stocks for All Market Conditions
ONE MORE THING: Top 6 Stocks for This Week. This market is separating quality stocks from expensive ones fast. AI is taking down whole sectors with no warning. In a rotation this fast, you need more than a list of good companies.
Our AI system flagged Palantir before it ran 1,662% between October 2022 and February 2026. AppLovin before it ran 753% between February 2024 and February 2026. Nvidia before it ran 1,178% between January 2023 and February 2026. Each week it produces 6 new names that pass the same tests. Get Our Top 6 Stocks for Free HERE.
Stocks that have made our list include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-small-cap company Comfort Systems (+1,154% between June 2020 and June 2025). Find your next big winner with StockStory today.