Over the past six months, Royal Caribbean’s stock price fell to $239.25. Shareholders have lost 14.2% of their capital, which is disappointing considering the S&P 500 has climbed by 16.9%. This might have investors contemplating their next move.
Is now the time to buy Royal Caribbean, or should you be careful about including it in your portfolio? See what our analysts have to say in our full research report, it’s free.
Why Do We Think Royal Caribbean Will Underperform?
Even with the cheaper entry price, we’re sitting this one out for now. Here are three reasons you should be careful with RCL, plus one stock we’d rather own.
1. Weak Growth in Passenger Cruise Days Points to Soft Demand
Revenue growth can be broken down into changes in price and volume (for companies like Royal Caribbean, our preferred volume metric is passenger cruise days). While both are important, the latter is the most critical to analyze because prices have a ceiling.
Royal Caribbean’s passenger cruise days came in at 14.96 million in the latest quarter, and over the last two years, averaged 6.6% year-on-year growth. This performance was underwhelming and suggests it might have to lower prices or invest in product improvements to accelerate growth, factors that can hinder near-term profitability. 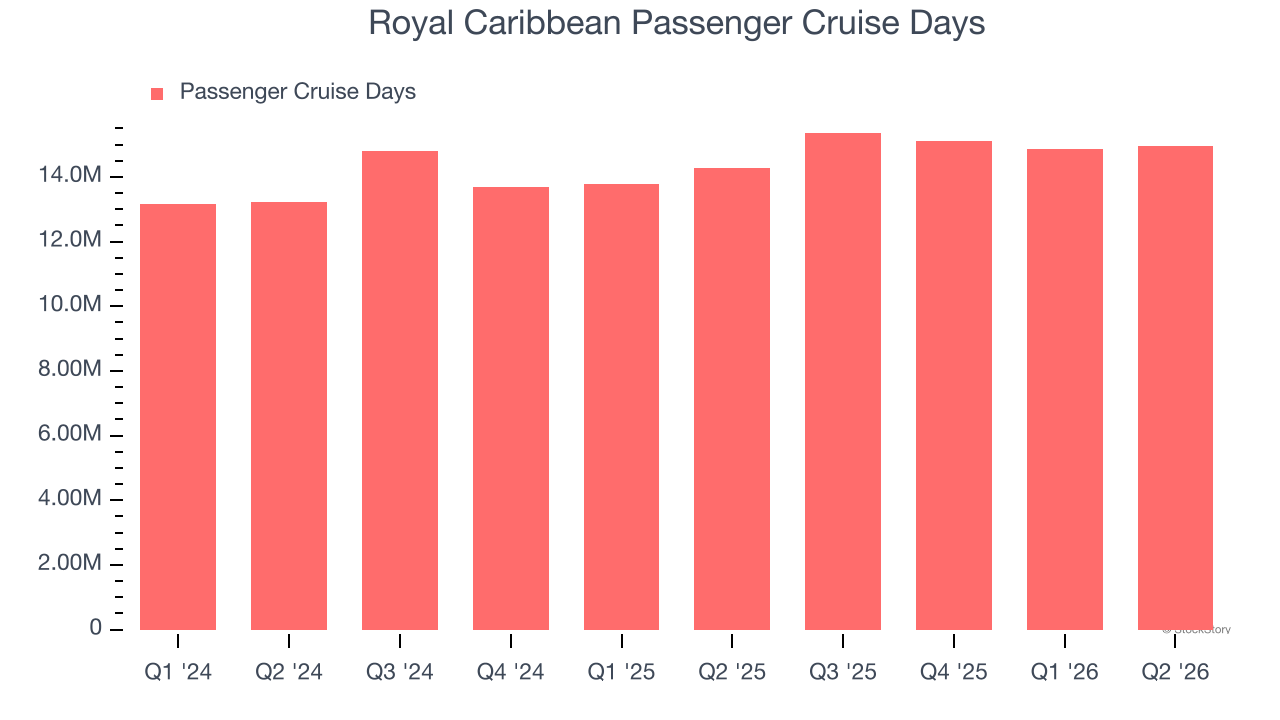
2. Mediocre Free Cash Flow Margin Limits Reinvestment Potential
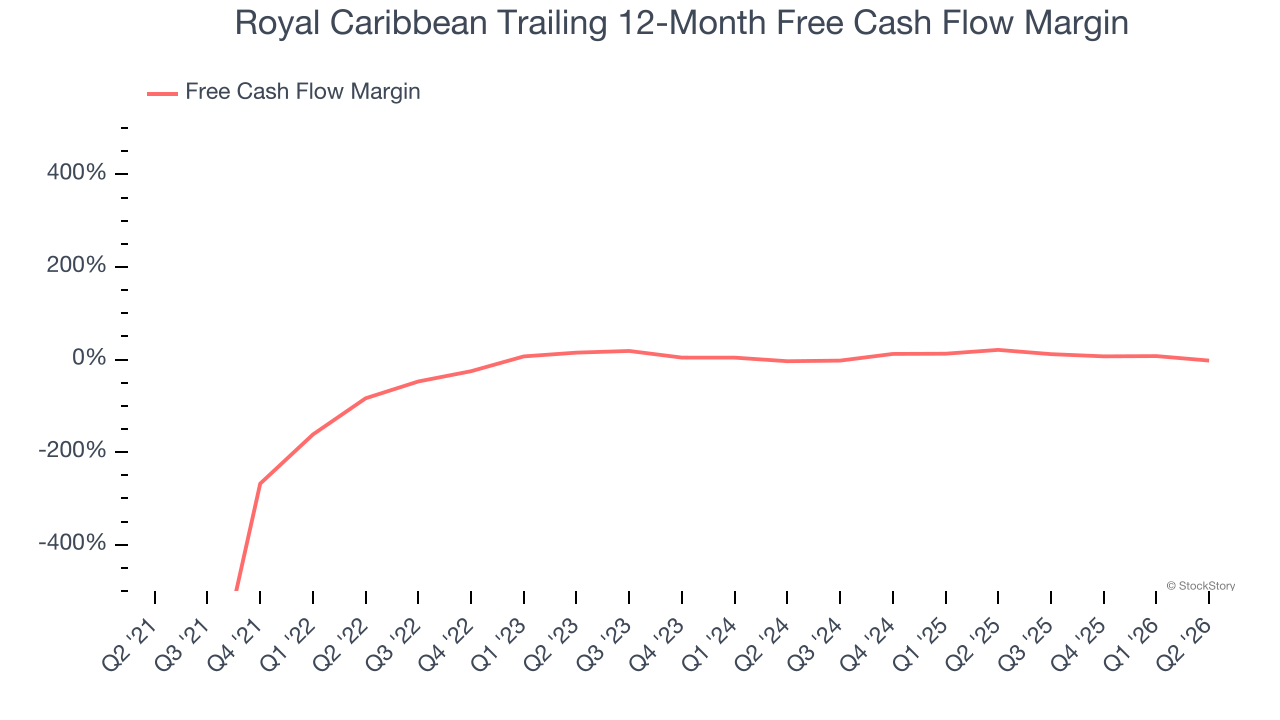
If you’ve followed StockStory for a while, you know we emphasize free cash flow. Why, you ask? We believe that in the end, cash is king, and you can’t use accounting profits to pay the bills.
Royal Caribbean has shown poor cash profitability relative to peers over the last two years, giving the company fewer opportunities to return capital to shareholders. Its free cash flow margin averaged 8.8%, below what we’d expect for a consumer discretionary business.
3. Previous Growth Initiatives Haven’t Impressed
Growth gives us insight into a company’s long-term potential, but how capital-efficient was that growth? A company’s ROIC explains this by showing how much operating profit it makes compared to the money it has raised (debt and equity).
Royal Caribbean historically did a mediocre job investing in profitable growth initiatives. Its five-year average ROIC was 7.6%, somewhat low compared to the best consumer discretionary companies that consistently pump out 65%+.
Final Judgment
We cheer for all companies serving everyday consumers, but in the case of Royal Caribbean, we’ll be cheering from the sidelines. Following the recent decline, the stock trades at 12.2× forward P/E (or $239.25 per share). This valuation is reasonable, but the company’s shaky fundamentals present too much downside risk. There are better stocks to buy right now. We’d suggest looking at a dominant aerospace business that has perfected its M&A strategy.
High-Quality Stocks for All Market Conditions
WHILE YOU’RE HERE: Top 9 Market-Beating Stocks. The best stocks don’t just beat the market once. They do it again. And again. Robust revenue growth, rising free cash flow, returns on capital that leave their competition in the dust. The market has already rewarded these businesses.
But our AI platform says the party isn’t over. Find out which 9 stocks made the cut this week — FREE. Get Our Top 9 Market-Beating Stocks for Free HERE.
Stocks that have made our list include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-micro-cap company Tecnoglass (+1,552% between June 2020 and June 2025). Find your next big winner with StockStory today.