Perella Weinberg’s stock price has taken a beating over the past six months, shedding 20.7% of its value and falling to $13.82 per share. This might have investors contemplating their next move.
Is now the time to buy Perella Weinberg, or should you be careful about including it in your portfolio? See what our analysts have to say in our full research report, it’s free.
Why Do We Think Perella Weinberg Will Underperform?
Even with the cheaper entry price, we don’t have much confidence in Perella Weinberg. Here are three reasons we avoid PWP, plus one stock we’d rather own.
1. Revenue Spiraling Downwards
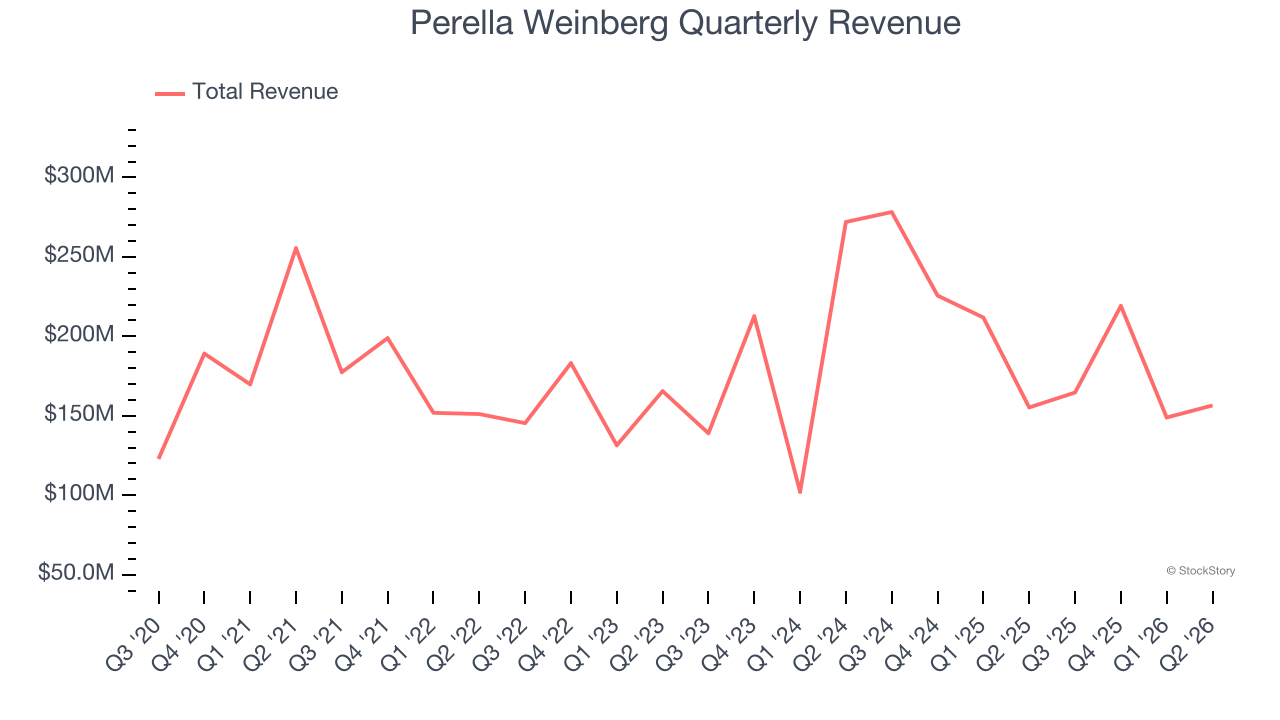
A company’s long-term sales performance can indicate its overall quality. Any business can experience short-term success, but top-performing ones enjoy sustained growth for years.
Over the last five years, Perella Weinberg’s demand was weak and its revenue declined by 1.3% per year. This wasn’t a great result and is a sign of poor business quality.
2. EPS Trending Down
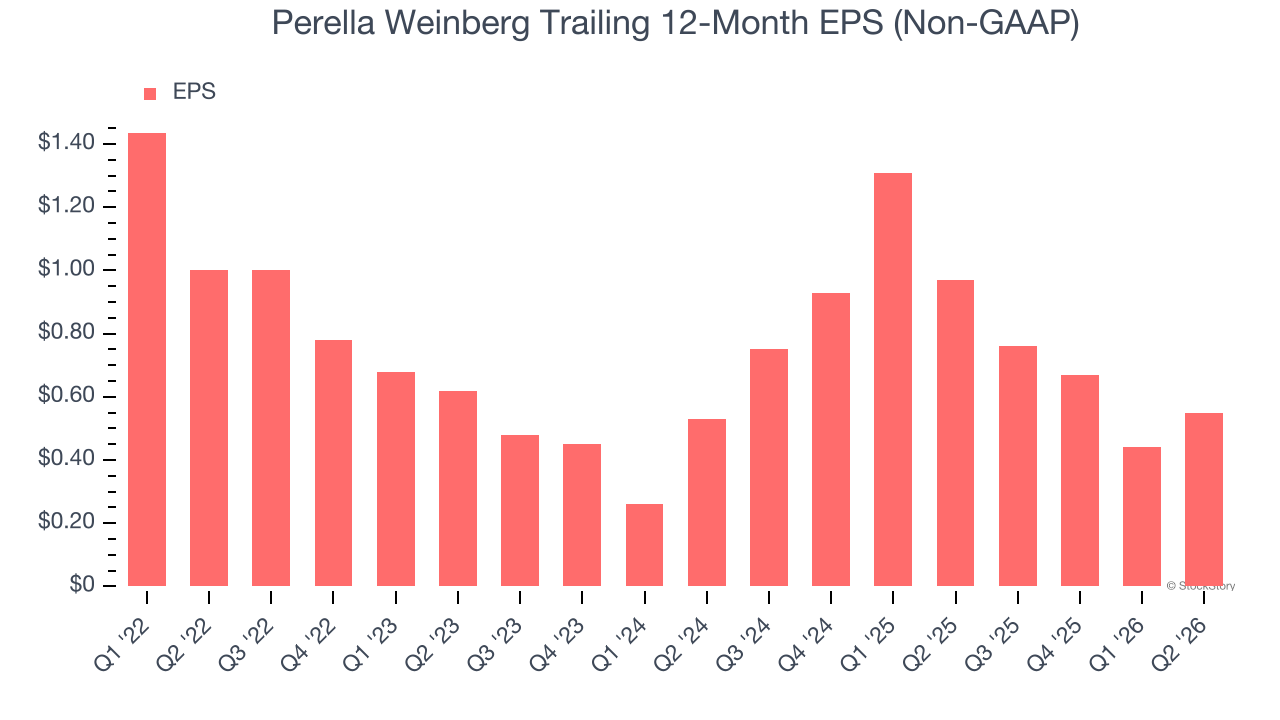
We track the long-term change in earnings per share (EPS) because it highlights whether a company’s growth is profitable.
Perella Weinberg’s full-year EPS dropped 68.2%, or 13.9% annually, over the last four years. We tend to steer our readers away from companies with falling revenue and EPS, where diminishing earnings could imply changing secular trends and preferences. If the tide turns unexpectedly, Perella Weinberg’s low margin of safety could leave its stock price susceptible to large downswings.
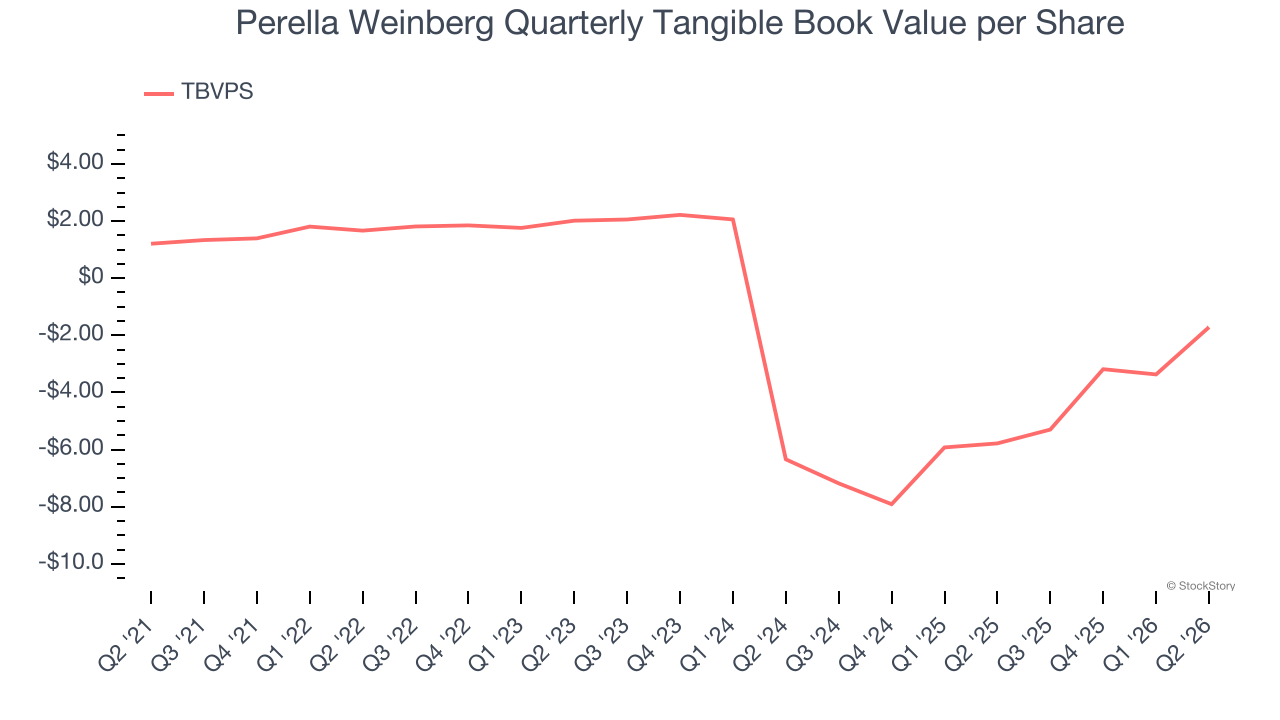
3. Declining TBVPS Reflects Erosion of Asset Value
Tangible book value per share (TBVPS) is a crucial metric that measures the actual value of shareholders’ equity, stripping out goodwill and other intangible assets that may not be recoverable in a worst-case scenario.
To the detriment of investors, Perella Weinberg’s TBVPS declined at a 48% annual clip over the last two years.
Final Judgment
We cheer for all companies supporting the economy, but in the case of Perella Weinberg, we’ll be cheering from the sidelines. Following the recent decline, the stock trades at 10.3× forward P/E (or $13.82 per share). This valuation tells us it’s a bit of a market darling with a lot of good news priced in - we think there are better stocks to buy right now. Let us point you toward one of our all-time favorite software stocks.
High-Quality Stocks for All Market Conditions
ONE MORE THING: Top 6 Stocks for This Week. This market is separating quality stocks from expensive ones fast. AI is taking down whole sectors with no warning. In a rotation this fast, you need more than a list of good companies.
Our AI system flagged Palantir before it ran 1,662% between October 2022 and February 2026. AppLovin before it ran 753% between February 2024 and February 2026. Nvidia before it ran 1,178% between January 2023 and February 2026. Each week it produces 6 new names that pass the same tests. Get Our Top 6 Stocks for Free HERE.
Stocks that have made our list include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-small-cap company Comfort Systems (+1,154% between June 2020 and June 2025). Find your next big winner with StockStory today.