Even though Aflac (currently trading at $113.73 per share) has gained 5.1% over the last six months, it has lagged the S&P 500’s 21.4% return during that period. This might have investors contemplating their next move.
Is there a buying opportunity in Aflac, or does it present a risk to your portfolio? Get the full stock story straight from our expert analysts, it’s free.
Why Do We Think Aflac Will Underperform?
We don’t have much confidence in Aflac. Here are three reasons why there are better opportunities than AFL, plus one stock we’d rather own.
1. Declining Net Premiums Earned Reflect Weakness
Net premiums earned are net of what’s paid to reinsurers (insurance for insurance companies), which are used by insurers to protect themselves from large losses.
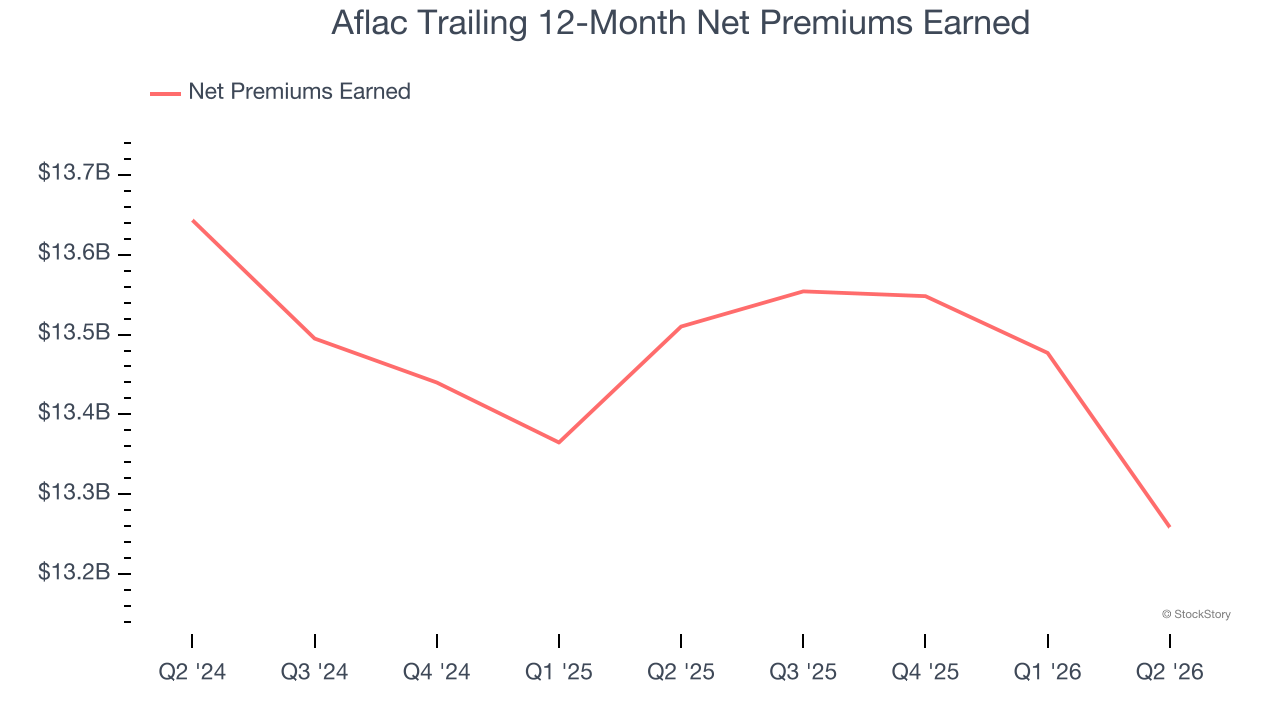
Aflac’s net premiums earned has declined by 6.3% annually over the last five years, much worse than the broader insurance industry. This shows that policy underwriting underperformed its other business lines.
2. BVPS Projections Show Stormy Skies Ahead
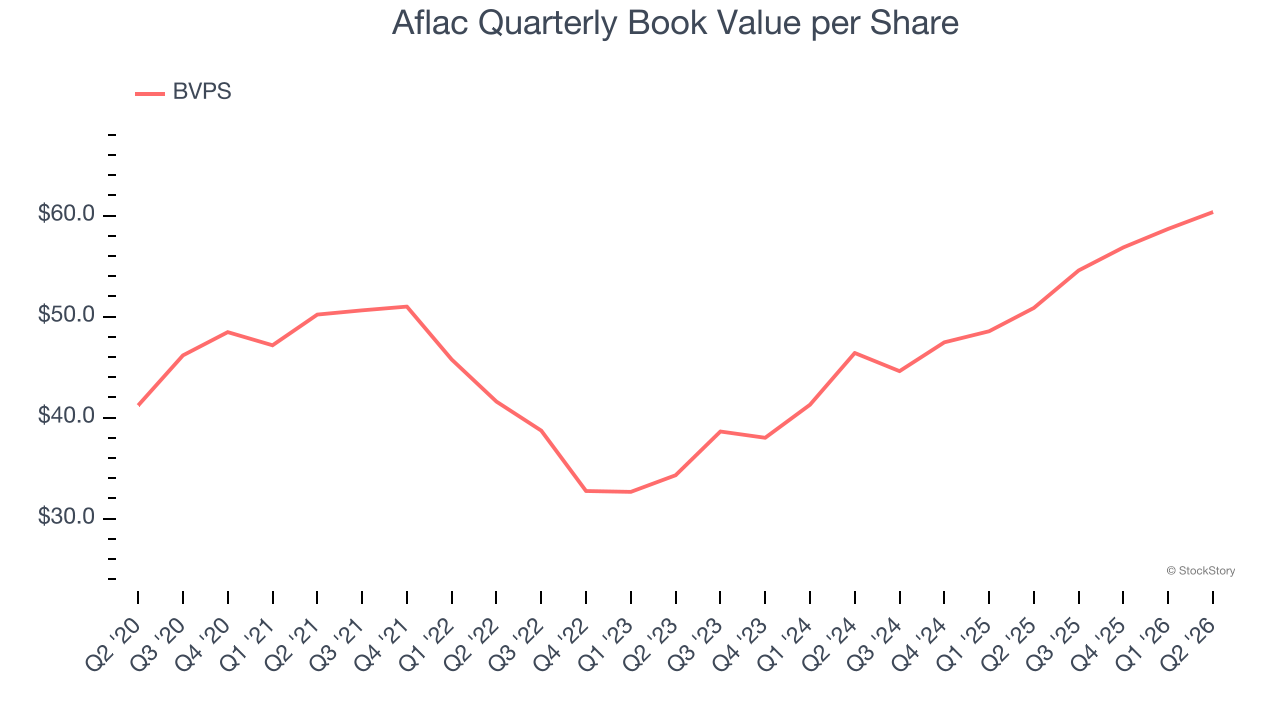
Book value per share (BVPS) growth comes from an insurer’s ability to price risk appropriately and invest premiums profitably.
Over the next 12 months, Consensus estimates call for Aflac’s BVPS to shrink by 7.5% to $55.23, a sour projection.
The debt-to-equity ratio is a widely used measure to assess a company’s balance sheet health. A higher ratio means that a business aggressively financed its growth with debt. This can result in higher earnings (if the borrowed funds are invested profitably) but also increases risk.
If debt levels are too high, there could be difficulties in meeting obligations, especially during economic downturns or periods of rising interest rates if the debt has variable-rate payments.
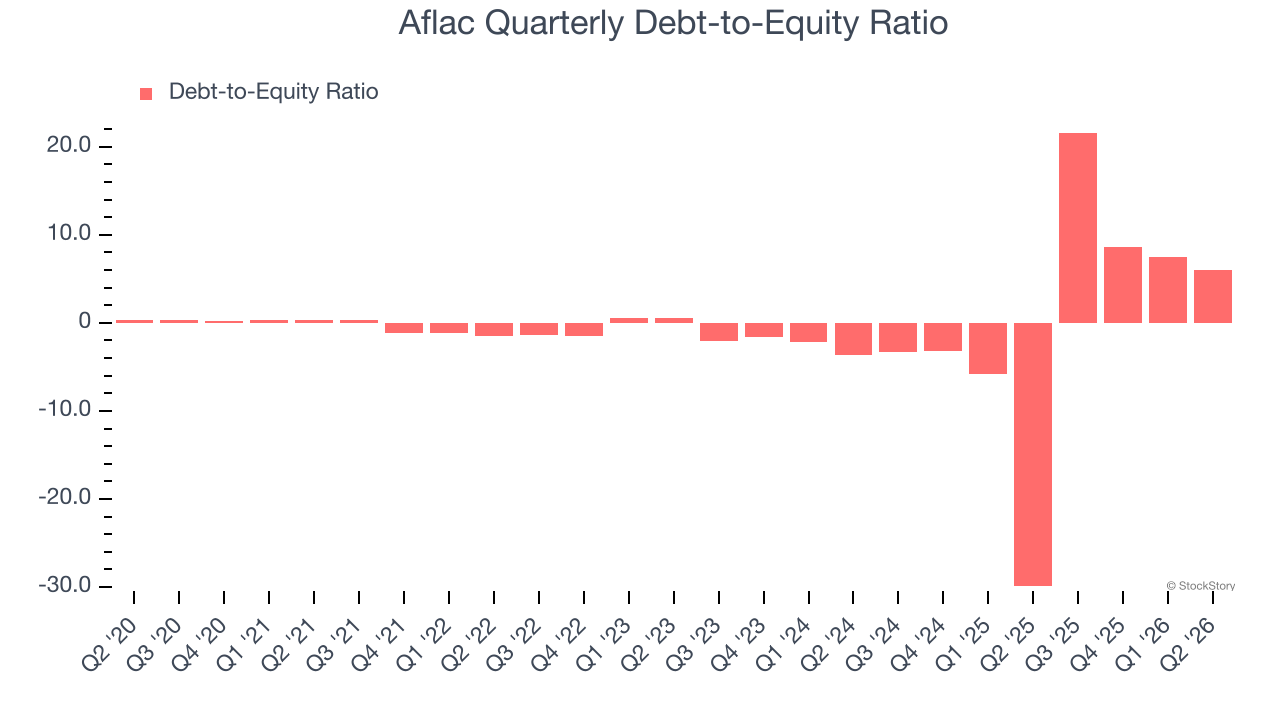
Aflac currently has $16.07 billion of debt and $2.68 billion of shareholders’ equity on its balance sheet, and over the past four quarters, has averaged a debt-to-equity ratio of 10.9×. We think this is dangerous - for an insurance business, anything above 1.0× raises red flags.
Final Judgment
We cheer for all companies serving everyday consumers, but in the case of Aflac, we’ll be cheering from the sidelines. With its shares lagging the market recently, the stock trades at 1.9× forward P/B (or $113.73 per share). This valuation tells us it’s a bit of a market darling with a lot of good news priced in - we think there are better opportunities elsewhere. We’d recommend looking at the most entrenched endpoint security platform on the market.
High-Quality Stocks for All Market Conditions
ALSO WORTH WATCHING: Top 5 Momentum Stocks. The best time to own a great stock is when the market is finally noticing it. These aren’t just high-quality businesses. Something is happening with them right now. Elite fundamentals meet near-term momentum — both boxes checked at the same time.
Find out which stocks our AI platform is flagging this week. See this week’s Strong Momentum stocks — FREE. Get Our Strong Momentum Stocks for Free HERE.
Stocks that have made our list include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-micro-cap company Tecnoglass (+1,552% between June 2020 and June 2025). Find your next big winner with StockStory today.