While the S&P 500 is up 21.4% since March 2026, Valley National Bank (currently trading at $13.09 per share) has lagged behind, posting a return of 10%. This was partly driven by its softer quarterly results and may have investors wondering how to approach the situation.
Is now the time to buy Valley National Bank, or should you be careful about including it in your portfolio? Dive into our full research report to see our analyst team’s opinion, it’s free.
Why Is Valley National Bank Not Exciting?
We’re passing on Valley National Bank for now. Here are three reasons why VLY doesn’t excite us, plus one stock we’d rather own.
1. Net Interest Income Points to Soft Demand
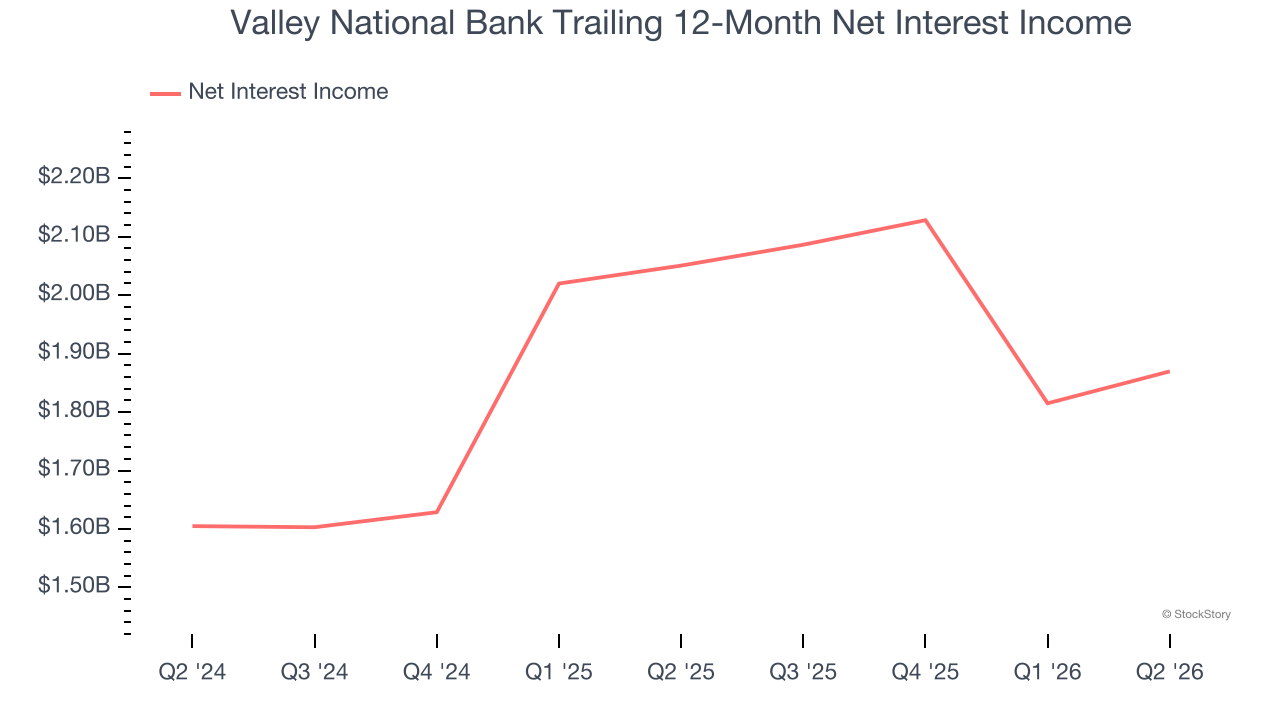
Our experience and research show the market cares primarily about a bank’s net interest income growth as one-time fees are considered a lower-quality and non-recurring revenue source.
Valley National Bank’s net interest income has grown at a 9.9% annualized rate over the last five years, slightly worse than the broader banking industry and in line with its total revenue.
2. Low Net Interest Margin Reveals Weak Loan Book Profitability
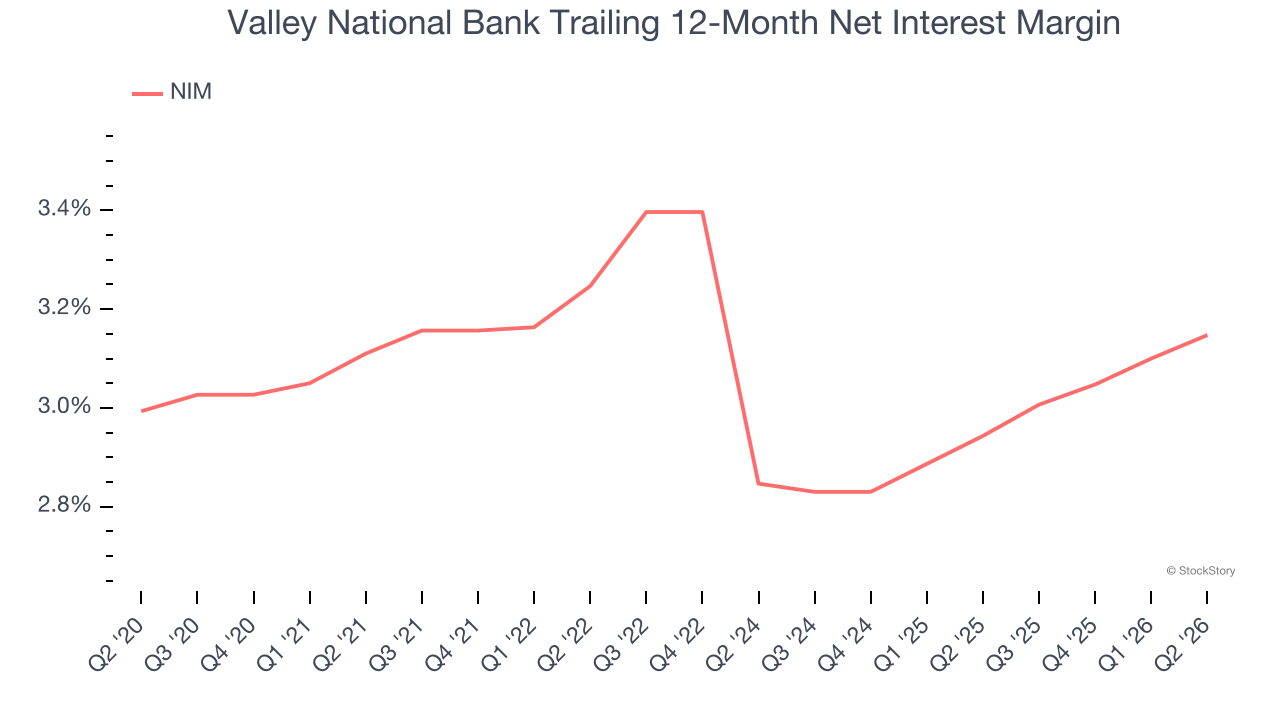
The net interest margin (NIM) is a key profitability indicator that measures the difference between what a bank earns on its loans and what it pays on its deposits. This metric measures how efficiently it can generate income from its core lending activities.
Over the past two years, we can see that Valley National Bank’s net interest margin averaged a weak 3.1%, indicating the company has weak loan book economics.
3. EPS Barely Growing
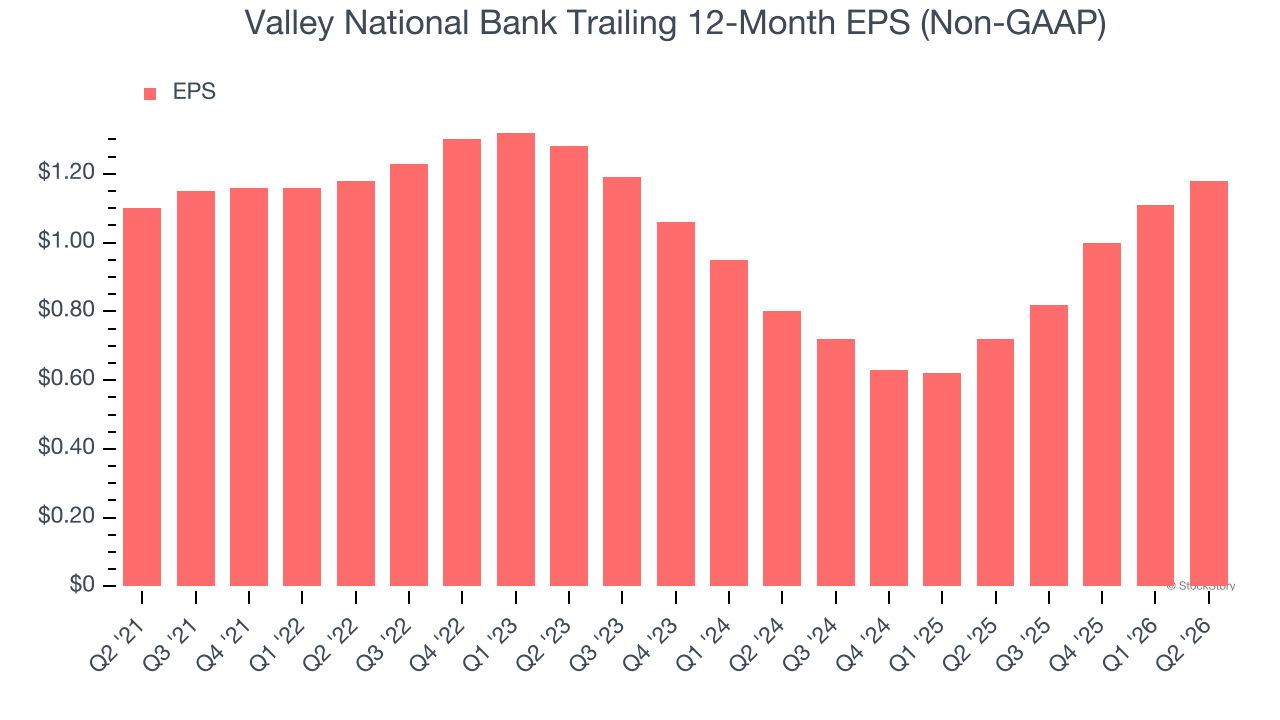
Analyzing the long-term change in earnings per share (EPS) shows whether a company’s incremental sales were profitable — for example, revenue could be inflated through excessive spending on advertising and promotions.
Valley National Bank’s EPS grew at a weak 1.4% compounded annual growth rate over the last five years, lower than its 10% annualized revenue growth. This tells us the company became less profitable on a per-share basis as it expanded.
Final Judgment
Valley National Bank isn’t a terrible business, but it doesn’t pass our bar. With its shares underperforming the market lately, the stock trades at 0.9× forward P/B (or $13.09 per share). This valuation multiple is fair, but we don’t have much faith in the company. We’re fairly confident there are better investments elsewhere. We’d recommend looking at a fast-growing restaurant franchise with an A+ ranch dressing sauce.
Stocks We Would Buy Instead of Valley National Bank
ONE MORE THING: Top 5 Growth Stocks. The biggest stock winners almost always had one thing in common before they ran. Revenue growing like crazy. Meta. CrowdStrike. Broadcom. Our AI flagged all three. They returned 315%, 314%, and 455%, respectively.
Find out which 5 stocks it’s flagging this month — FREE. Get Our Top 5 Growth Stocks for Free HERE.
Stocks that have made our list include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-small-cap company Comfort Systems (+1,154% between June 2020 and June 2025). Find your next big winner with StockStory today.