Even though Levi's (currently trading at $19.69 per share) has gained 8.4% over the last six months, it has lagged the S&P 500’s 21.4% return during that period. This might have investors contemplating their next move.
Is there a buying opportunity in Levi's, or does it present a risk to your portfolio? Dive into our full research report to see our analyst team’s opinion, it’s free.
Why Do We Think Levi's Will Underperform?
We don’t have much confidence in Levi's. Here are three reasons why LEVI doesn’t excite us, plus one stock we’d rather own.
1. Weak Constant Currency Growth Points to Soft Demand
Investors interested in Consumer Discretionary - Apparel and Accessories companies should track constant currency revenue in addition to reported revenue. This metric excludes currency movements, which are outside of Levi’s control and are not indicative of underlying demand.
Over the last two years, Levi’s constant currency revenue averaged 6.9% year-on-year growth. This performance was underwhelming and suggests it might have to lower prices or invest in product improvements to accelerate growth, factors that can hinder near-term profitability. 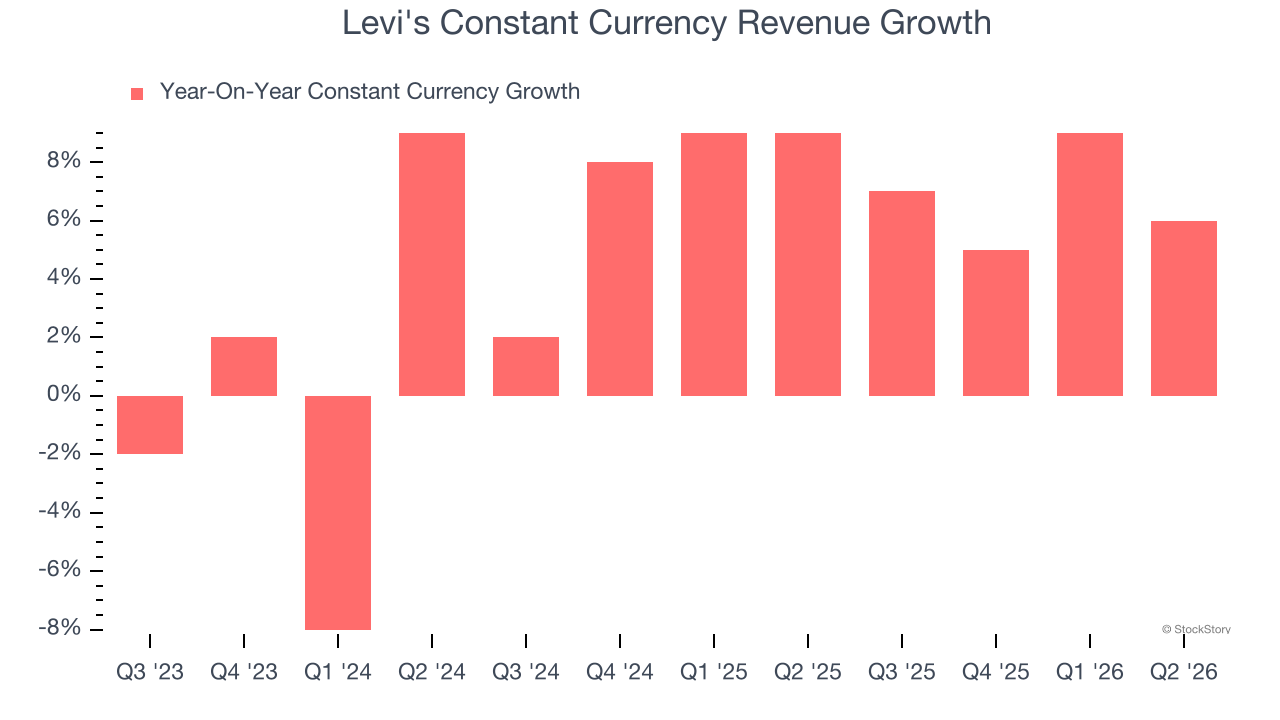
2. Cash Flow Margin Set to Decline
If you’ve followed StockStory for a while, you know we emphasize free cash flow. Why, you ask? We believe that in the end, cash is king, and you can’t use accounting profits to pay the bills.
Over the next year, analysts predict Levi’s cash conversion will fall. Their consensus estimates imply its free cash flow margin of 8.5% for the last 12 months will decrease to 4.4%.
3. New Investments Fail to Bear Fruit as ROIC Declines
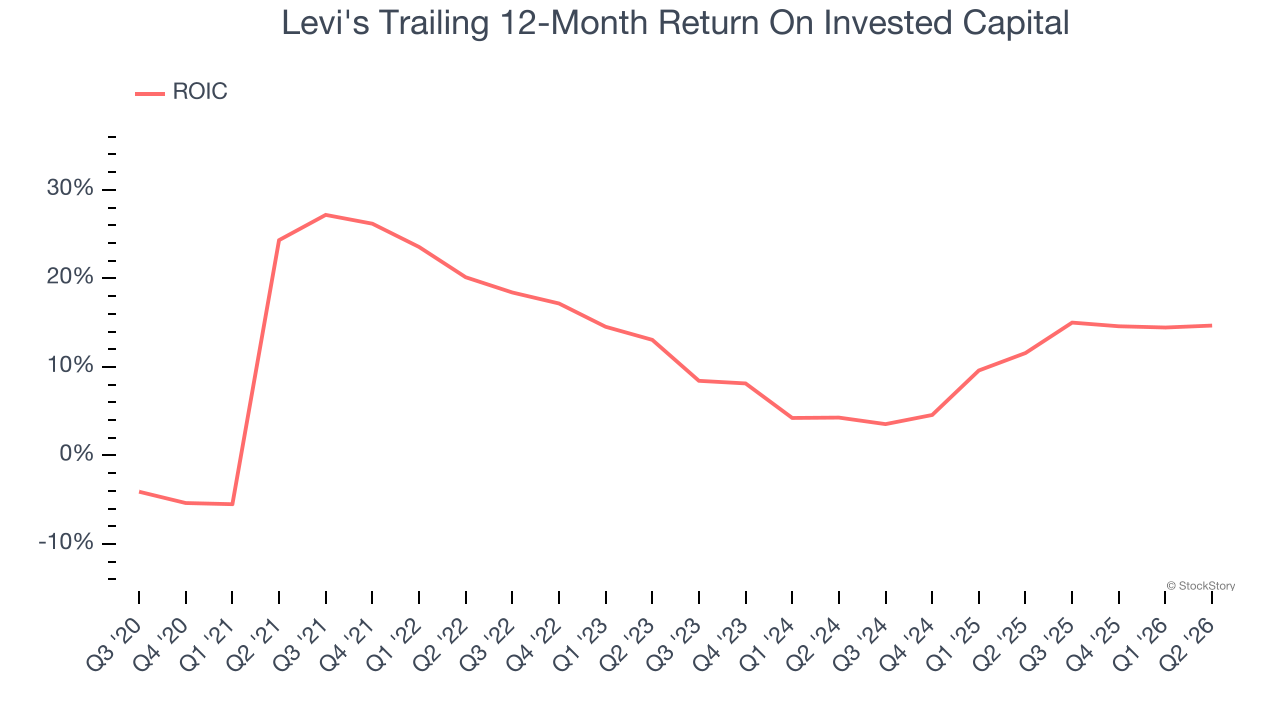
We like to invest in businesses with high returns, but the trend in a company’s ROIC can also be an early indicator of future business quality.
On average, Levi’s ROIC decreased by 3.5 percentage points annually each year over the last few years. Paired with its already low returns, these declines suggest its profitable growth opportunities are few and far between.
Final Judgment
We see the value of companies helping consumers, but in the case of Levi's, we’re out. With its shares trailing the market in recent months, the stock trades at 12.3× forward P/E (or $19.69 per share). This valuation is reasonable, but the company’s shaky fundamentals present too much downside risk. There are more exciting stocks to buy at the moment. We’d suggest looking at a fast-growing restaurant franchise with an A+ ranch dressing sauce.
Stocks We Would Buy Instead of Levi's
WHILE YOU’RE HERE: Top 9 Market-Beating Stocks. The best stocks don’t just beat the market once. They do it again. And again. Robust revenue growth, rising free cash flow, returns on capital that leave their competition in the dust. The market has already rewarded these businesses.
But our AI platform says the party isn’t over. Find out which 9 stocks made the cut this week — FREE. Get Our Top 9 Market-Beating Stocks for Free HERE.
Stocks that have made our list include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-small-cap company Exlservice (+271% between June 2020 and June 2025). Find your next big winner with StockStory today.