Insurance customer acquisition platform MediaAlpha (NYSE: MAX) announced better-than-expected revenue in Q3 2026, with revenue up 22.7% year on year to $375.9 million. Next quarter’s revenue guidance ($365 million at the midpoint) was a positive surprise, coming in 9.8% above analysts’ consensus estimates. Its GAAP profit of $0.46 per share was 49.5% above analysts’ consensus estimates.
For more on MediaAlpha, read the full research report for free.
MediaAlpha (MAX) Q3 2026 highlights:
- Revenue $375.9 million vs S&P analysts’ consensus estimates of $350.7 million (22.7% year-on-year growth, 7.2% beat)
- EPS (GAAP) $0.46 vs analysts’ consensus estimates of $0.31 (49.5% beat)
- Adjusted EBITDA $39.49 million vs analysts’ consensus estimates of $34.07 million (10.5% margin, 15.9% beat)
- Revenue guidance $365 million at the midpoint for Q4 2026, above analysts’ consensus estimates of $332.5 million
- EBITDA guidance $37.5 million at the midpoint for Q4 2026, above analysts’ consensus estimates of $34.91 million
- Operating margin 7.7%, up from 6.4% in the same quarter last year
- Market capitalization $623.5 million
“We delivered a milestone third quarter, achieving record results across all of our key metrics as demand continued to broaden in our marketplace,” said Steve Yi, CEO of MediaAlpha. “Carriers are competing aggressively for new policies and committing meaningful budgets in both home and auto insurance, which is driving stronger outcomes for our partners. Looking forward, we believe the shift toward digital customer acquisition, combined with our industry-leading scale advantages, will allow us to drive double-digit growth in 2027 and beyond.”
Revenue growth
A company’s long-term performance is an indicator of its overall quality. Even a bad business can perform well for one or two quarters, but a top-tier one grows for years.
With $1.29 billion in revenue over the past 12 months, MediaAlpha is a mid-sized business services company, which sometimes brings disadvantages compared to larger competitors benefiting from better economies of scale. On the positive side, it can still achieve high growth rates because it’s working from a smaller revenue base.
MediaAlpha’s 13.9% annualized revenue growth over the last five years was strong, showing its demand was higher than that of many business services companies.
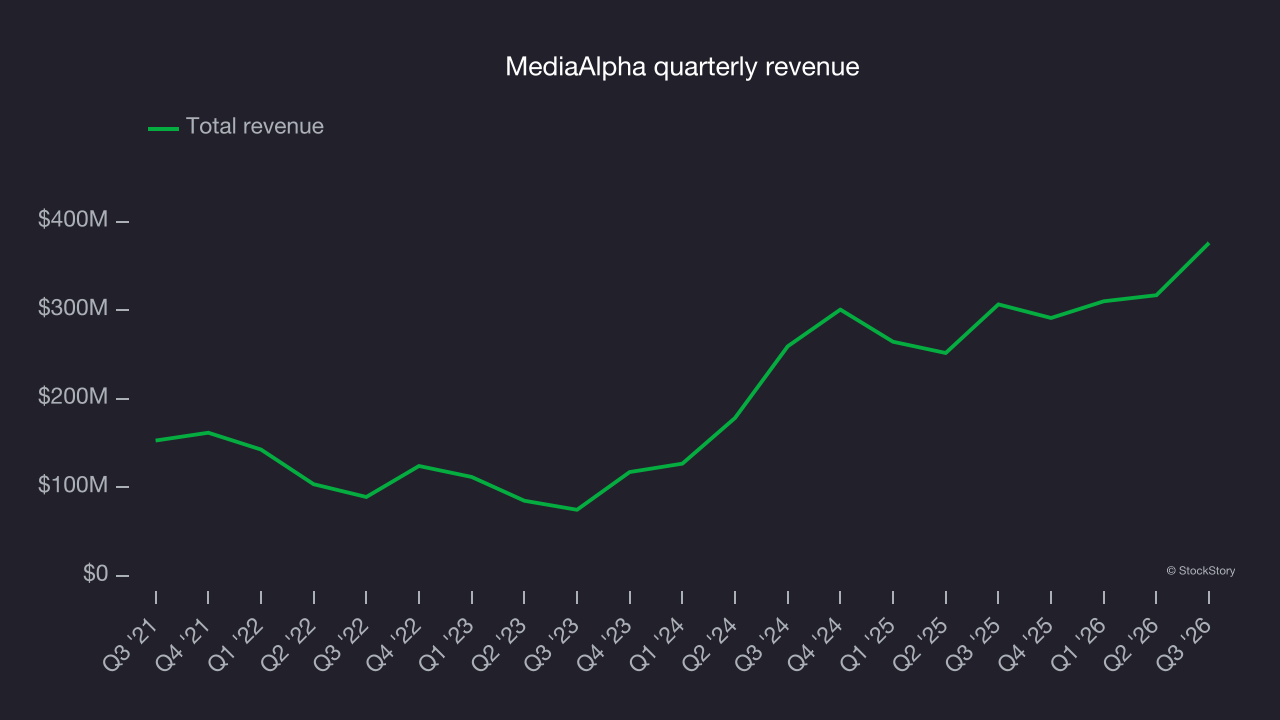
Long-term growth is the most important, but within business services, a half-decade historical view may miss new innovations or demand cycles. MediaAlpha’s annualized revenue growth of 37.8% over the last two years is above its five-year trend, suggesting its demand was strong and recently accelerated. 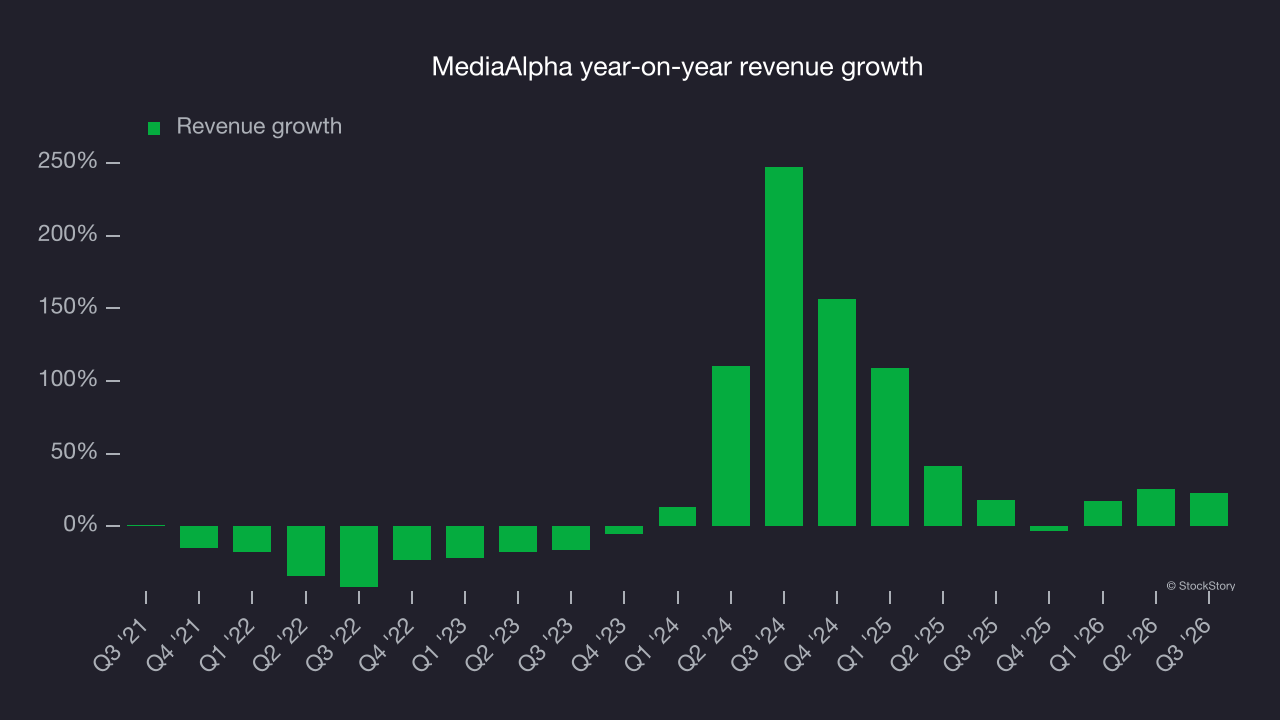
This quarter, MediaAlpha reported year-on-year revenue growth of 22.7%, and its $375.9 million of revenue topped Wall Street’s consensus estimates by 7.2%. Company management is currently guiding for a 25.4% year-on-year increase in revenue next quarter.
Looking further ahead, sell-side analysts expect revenue to grow 8.1% over the next 12 months, according to S&P, a deceleration versus the last two years. Despite the slowdown, this projection is solid and implies the market is forecasting success for its products and services.
Adjusted operating margin
MediaAlpha was profitable over the last five years but held back by its large cost base. Its average adjusted operating margin of 6.6% was weak for a business services company.
On the positive side, MediaAlpha’s adjusted operating margin rose by 3.8 percentage points over the last five years, as its revenue growth provided operating leverage.
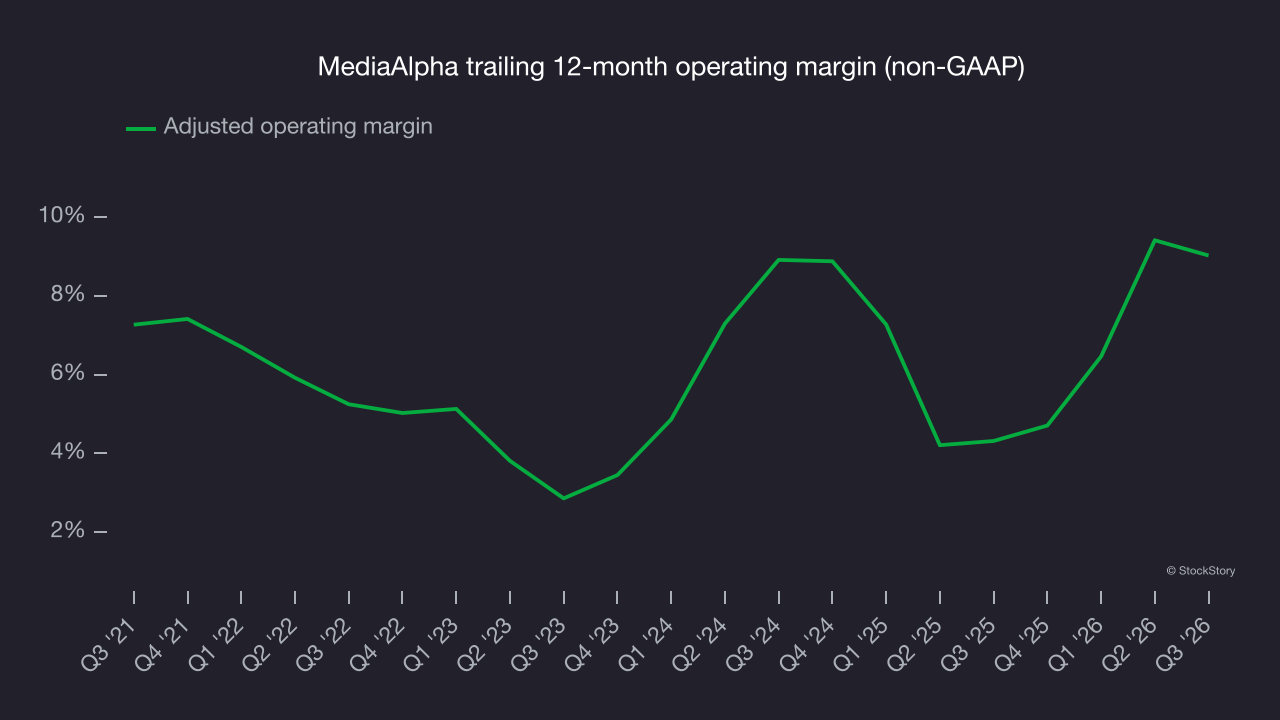
In Q3, MediaAlpha generated an adjusted operating margin of 7.7%, down 1.2 percentage points year on year. This small decline indicates the company’s overall cost structure has been relatively stable.
Earnings per share
Revenue trends explain a company’s historical growth, but the long-term change in earnings per share (EPS) points to the profitability of that growth; for example, a company could inflate its revenue through excessive spending on advertising and promotions.
MediaAlpha’s full-year EPS flipped from negative to positive over the last five years. This is a good sign and shows it’s at an inflection point.
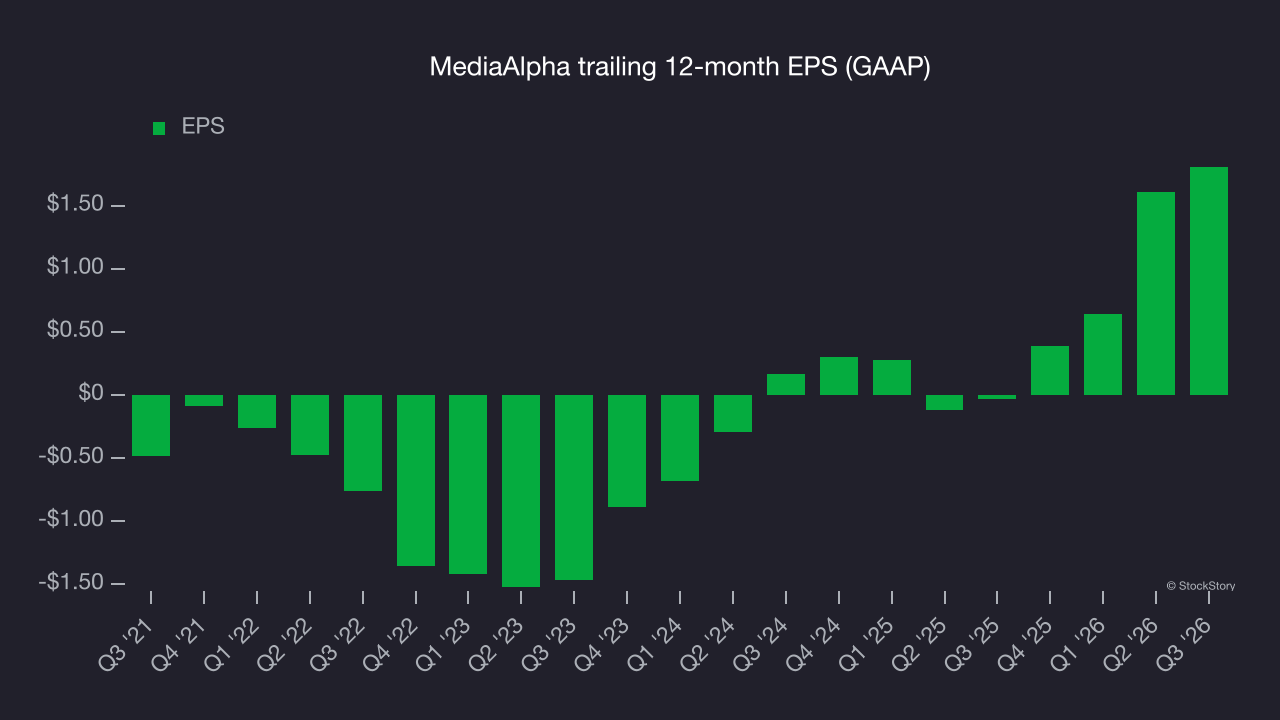
As with revenue, examining EPS over a more recent period can provide insight into an emerging theme or development for the business.
MediaAlpha’s EPS grew at a 229% compounded annual growth rate over the last two years, higher than its 37.8% annualized revenue growth. This tells us the company became more profitable on a per-share basis as it expanded.
In Q3, MediaAlpha reported EPS of $0.46, up from $0.26 in the same quarter last year. EPS easily topped analysts’ consensus estimates, a positive result for shareholders. Over the next 12 months, Wall Street expects MediaAlpha’s full-year EPS to shrink by 37.9% from $1.81 to $1.12, according to S&P.
Key takeaways from MediaAlpha’s Q3 results
MediaAlpha delivered a strong quarter, with revenue beating Wall Street’s consensus estimates by a wide margin and EPS also topping analysts’ consensus estimates. Shares soared 18% to $13.85 immediately after the results.
MediaAlpha reported solid earnings, but one quarter doesn’t necessarily make the stock a buy. To assess the investment, consider the bigger picture of valuation, business quality and the latest earnings. For more on those factors, read our full research report here (it’s free).