Fast-food chain Wingstop (NASDAQ: WING) missed Wall Street’s revenue expectations in Q3 2026, but revenue rose 5.3% year on year to $185.1 million. Its non-GAAP profit of $1.08 per share was 5.7% above analysts’ consensus estimates.
For more on Wingstop, read the full research report for free.
Wingstop (WING) Q3 2026 highlights:
- Revenue $185.1 million vs S&P analysts’ consensus estimates of $192.9 million (5.3% year-on-year growth, 4% miss)
- Adjusted EPS $1.08 vs S&P analysts’ consensus estimates of $1.02 (5.7% beat)
- Adjusted EBITDA $64 million vs analysts’ consensus estimates of $65.74 million (34.6% margin, 2.7% miss)
- Operating margin 27.4%, in line with the same quarter last year
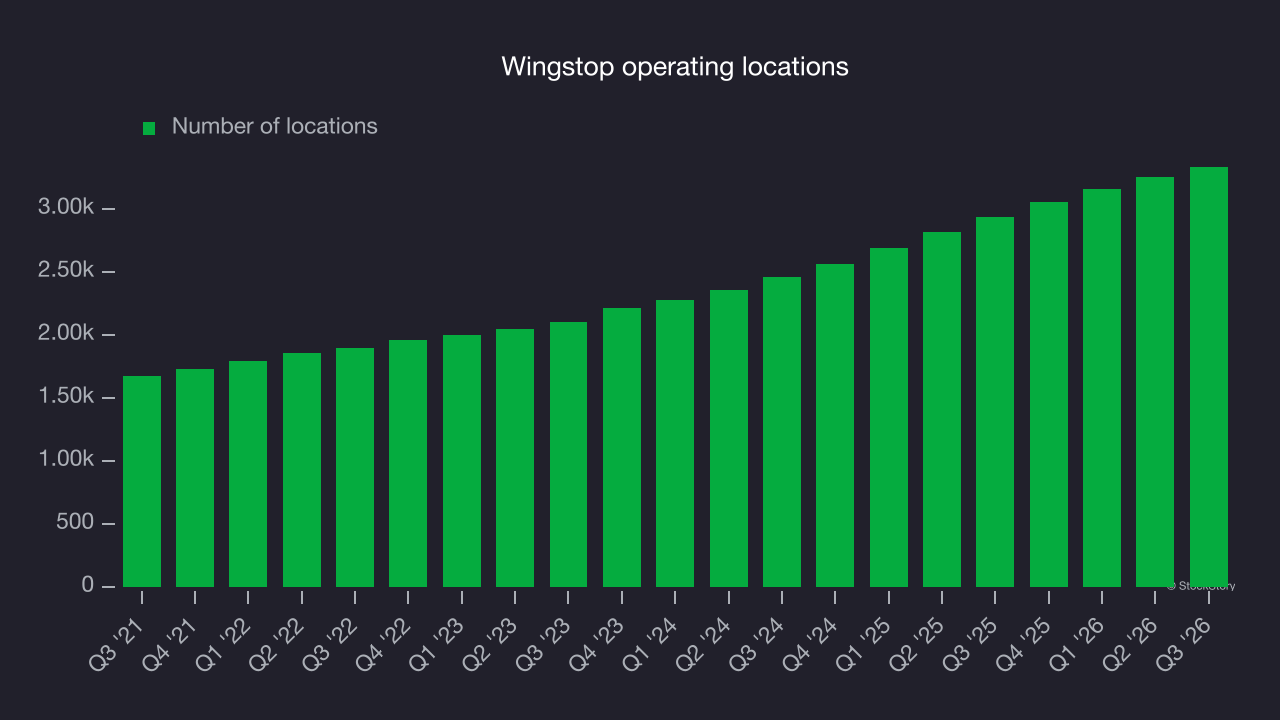
- Locations 3,331 at quarter end, up from 2,932 in the same quarter last year
- Same-store sales fell 5.4% year on year, in line with the same quarter last year
- Market capitalization $3.36 billion
Revenue growth
Examining a company’s long-term performance can provide clues about its quality. Any business can experience short-term success, but top-performing ones enjoy sustained growth for years.
With $730.1 million in revenue over the past 12 months, Wingstop is a small restaurant chain, which sometimes brings disadvantages compared to larger competitors benefiting from better brand awareness and economies of scale. On the positive side, it can grow faster because it has more room to build new restaurants.
Wingstop grew its revenue at a strong 21.5% compounded annual growth rate over the last seven years as it opened new restaurants and expanded its reach.
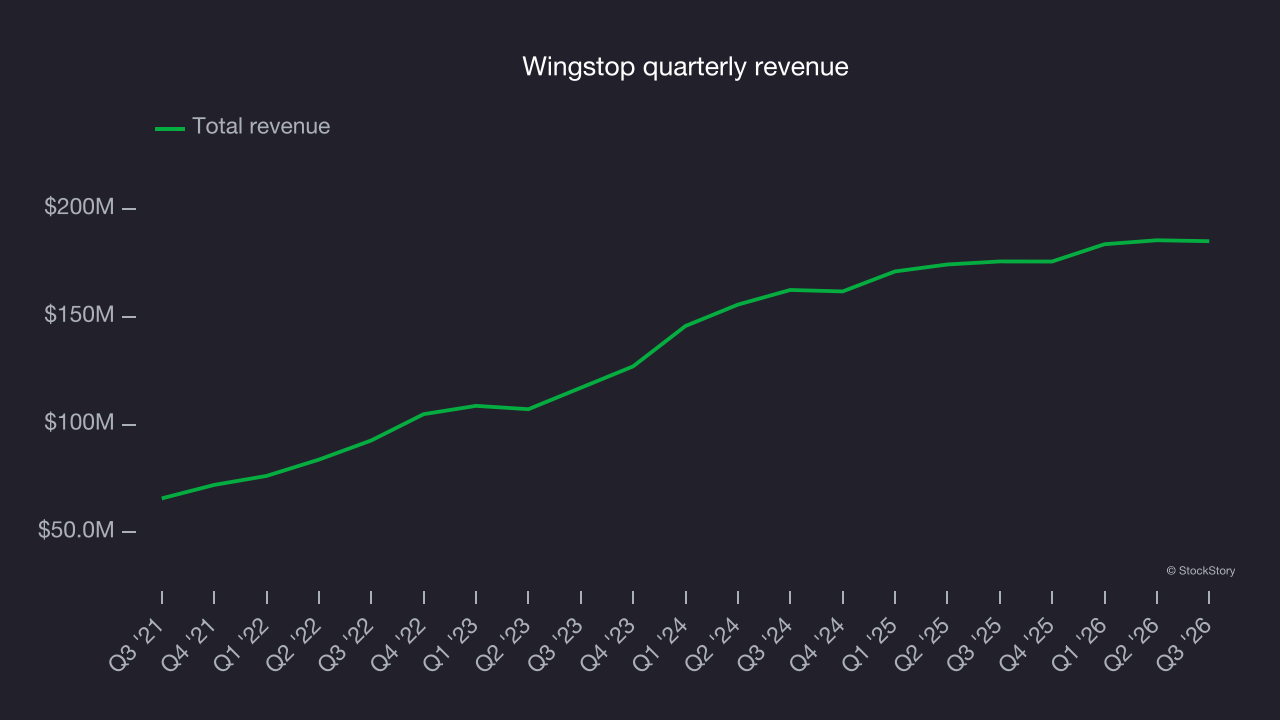
This quarter, Wingstop’s revenue grew by 5.3% year on year to $185.1 million, missing Wall Street’s consensus estimates.
Looking ahead, sell-side analysts expect revenue to grow 17% over the next 12 months, according to S&P, a deceleration versus the last seven years. Despite the slowdown, this projection remains encouraging and implies the market expects its menu offerings to succeed.
Restaurant performance
Number of restaurants
A restaurant chain’s total number of dining locations influences how much it can sell and how quickly revenue can grow.
Wingstop operated 3,331 locations in the latest quarter. It has opened new restaurants at a rapid pace over the last two years, averaging 17.3% annual growth, much faster than the broader restaurant sector. This gives it a chance to scale into a mid-sized business over time. Its franchise model also facilitates expansion: franchisees are primarily responsible for opening new restaurants while Wingstop provides support.
When a chain opens new restaurants, it usually means it’s investing for growth because there’s healthy demand for its meals and there are markets where its concepts have few or no locations.
Same-store sales
A company’s restaurant base only paints one part of the picture. When demand is high, it makes sense to open more. But when demand is low, it’s prudent to close some locations and use the money in other ways. Same-store sales provides a deeper understanding of this issue because it measures organic growth at restaurants open for at least a year.
Wingstop’s demand has been shrinking over the last two years as its same-store sales have averaged 3% annual declines. This performance is concerning: it shows Wingstop artificially boosts its revenue by building new restaurants. Same-store sales growth should precede the costly, capital-intensive expansion of a company’s restaurant base.
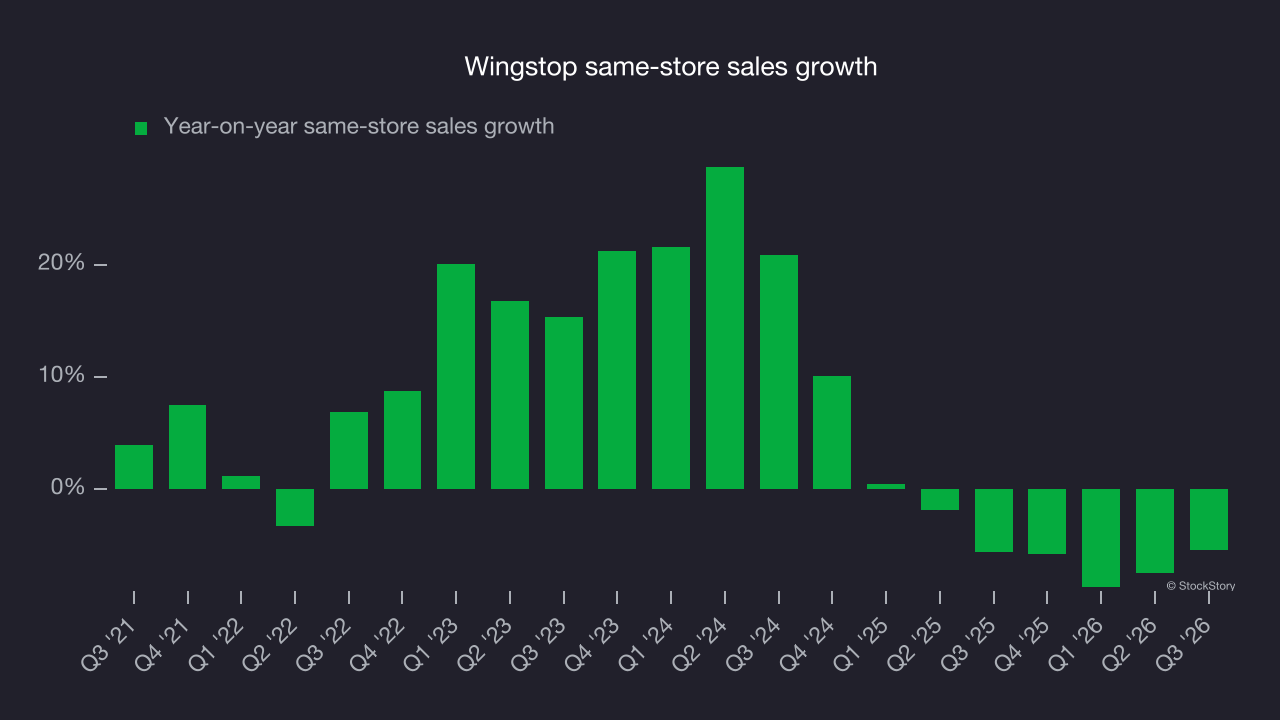
In the latest quarter, Wingstop’s same-store sales fell by 5.4% year on year. This decrease represents a further deceleration from its historical levels. A return to growth would be welcome.
Key takeaways from Wingstop’s Q3 results
It was good to see Wingstop beat analysts’ EPS expectations this quarter. On the other hand, its revenue missed. Overall, this was a mixed quarter. Still, the stock traded up 6.9% to $134.21 immediately following the results.
When deciding whether to buy the stock, it’s important to consider its valuation, business quality and what happened in the latest quarter. For more, read our full research report here (it’s free).