
Restaurant company Bloomin’ Brands (NASDAQ: BLMN) reported Q3 2026 results exceeding the market’s revenue expectations, with revenue up 1.7% year on year to $944.3 million. Its non-GAAP loss of $0.17 per share was 28.5% above analysts’ consensus estimates.
For more on Bloomin' Brands, read our free full research report.
Bloomin' Brands (BLMN) Q3 2026 highlights:
- Revenue $944.3 million vs S&P analysts’ consensus estimates of $925 million (1.7% year-on-year growth, 2.1% beat)
- Adjusted EPS -$0.17 vs S&P analysts’ consensus estimates of -$0.24 (28.5% beat)
- Adjusted EPS guidance Management raised its full-year adjusted EPS guidance to $1.00 at the midpoint, a 4.7% increase
- Operating margin 2%, up from -3.9% in the same quarter last year
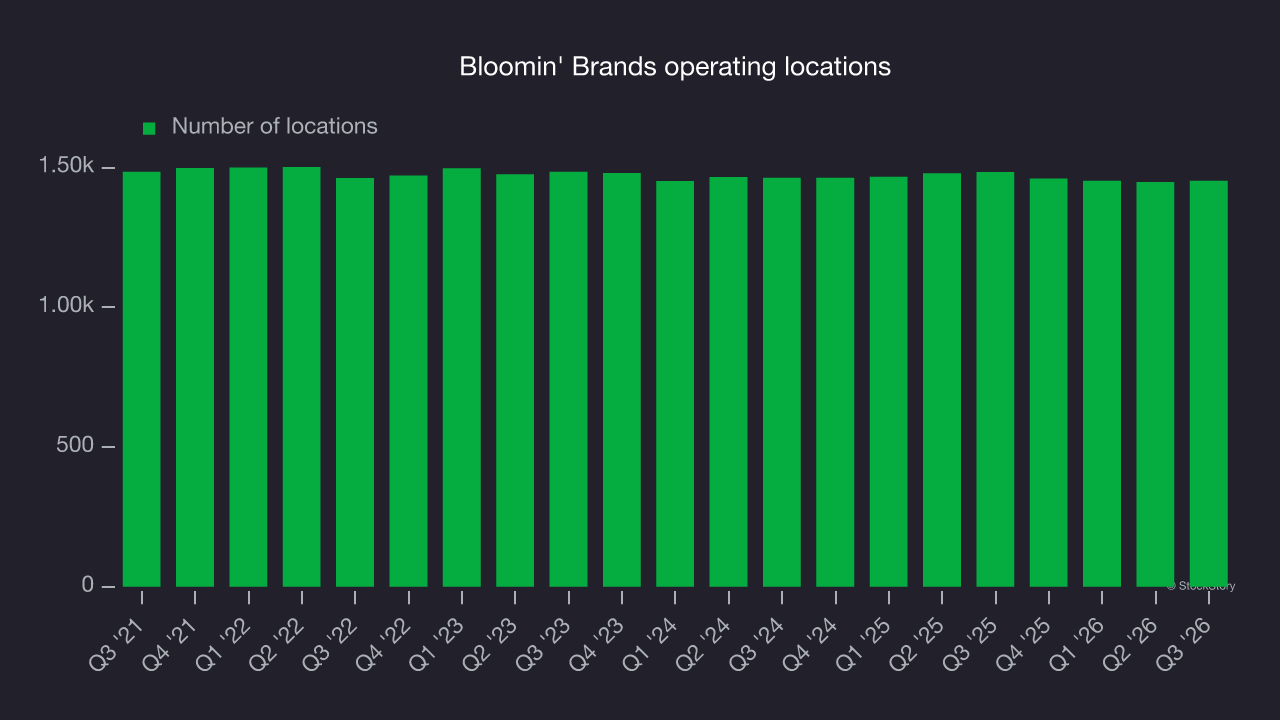
- Locations 1,452 at quarter end, down from 1,483 in the same quarter last year
- Same-store sales rose 1.9% year on year, in line with the same quarter last year
- Market capitalization $896.5 million
CEO Comments “We are encouraged by our third quarter results and the continued progress on the Outback Turnaround, including five consecutive quarters of year-over-year improvement in Outback guest scores,” said Mike Spanos, CEO. “We remain focused on consistent execution across food, service, experience, and affordability to strengthen the guest experience and drive sustainable long-term growth.”
Revenue growth
A company’s long-term revenue performance is one signal of its overall quality. Any business can have short-term success, but a top-tier one grows for years.
With $4.00 billion in revenue over the past 12 months, Bloomin' Brands is one of the larger restaurant chains in the industry and benefits from a well-known brand that influences consumer purchasing decisions. However, its scale is a double-edged sword because there is only so much real estate to build restaurants, placing a ceiling on its growth. For Bloomin' Brands to boost its revenue, it likely needs to adjust its prices, launch new chains or expand in foreign markets.
Bloomin' Brands struggled to increase demand as its $4.00 billion in revenue for the trailing 12 months was close to its revenue seven years ago. This was mainly because it didn’t open many new restaurants.
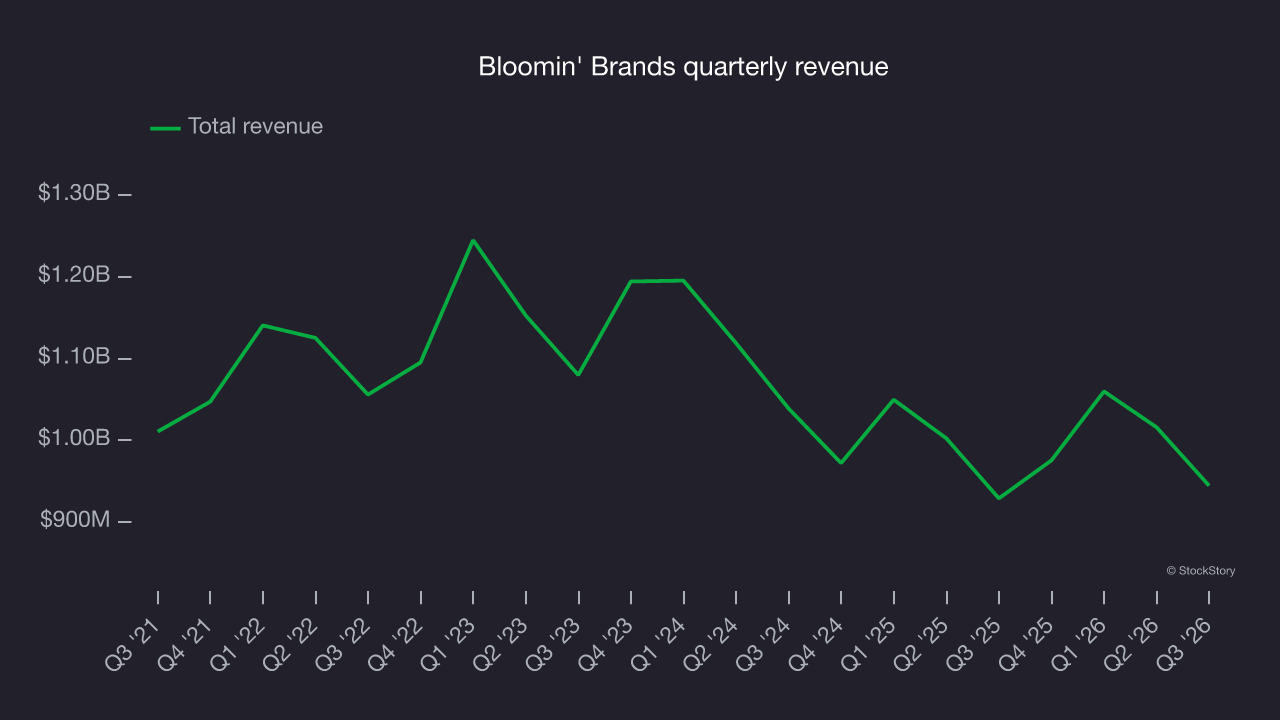
This quarter, Bloomin' Brands reported modest year-on-year revenue growth of 1.7% but beat Wall Street’s consensus estimates by 2.1%.
Looking ahead, sell-side analysts expect revenue to remain flat over the next 12 months, according to S&P. Although this projection implies its newer menu offerings will spur better top-line performance, it is still below the sector average.
Restaurant performance
Number of restaurants
A restaurant chain’s total number of dining locations often determines how much revenue it can generate.
Bloomin' Brands listed 1,452 locations in the latest quarter and has kept its restaurant count flat over the last two years while other restaurant businesses have opted for growth.
When a chain doesn’t open many new restaurants, it usually means there’s stable demand for its meals and it’s focused on improving operational efficiency to increase profitability.
Same-store sales
A company’s restaurant base only paints one part of the picture. When demand is high, it makes sense to open more. But when demand is low, it’s prudent to close some locations and use the money in other ways. Same-store sales provide a deeper understanding of this issue because the metric measures organic growth at restaurants open for at least a year.
Bloomin' Brands’s demand within its existing dining locations has barely increased over the last two years as its same-store sales were flat. This performance isn’t ideal and warrants skepticism if Bloomin' Brands starts opening new restaurants to artificially boost revenue growth.
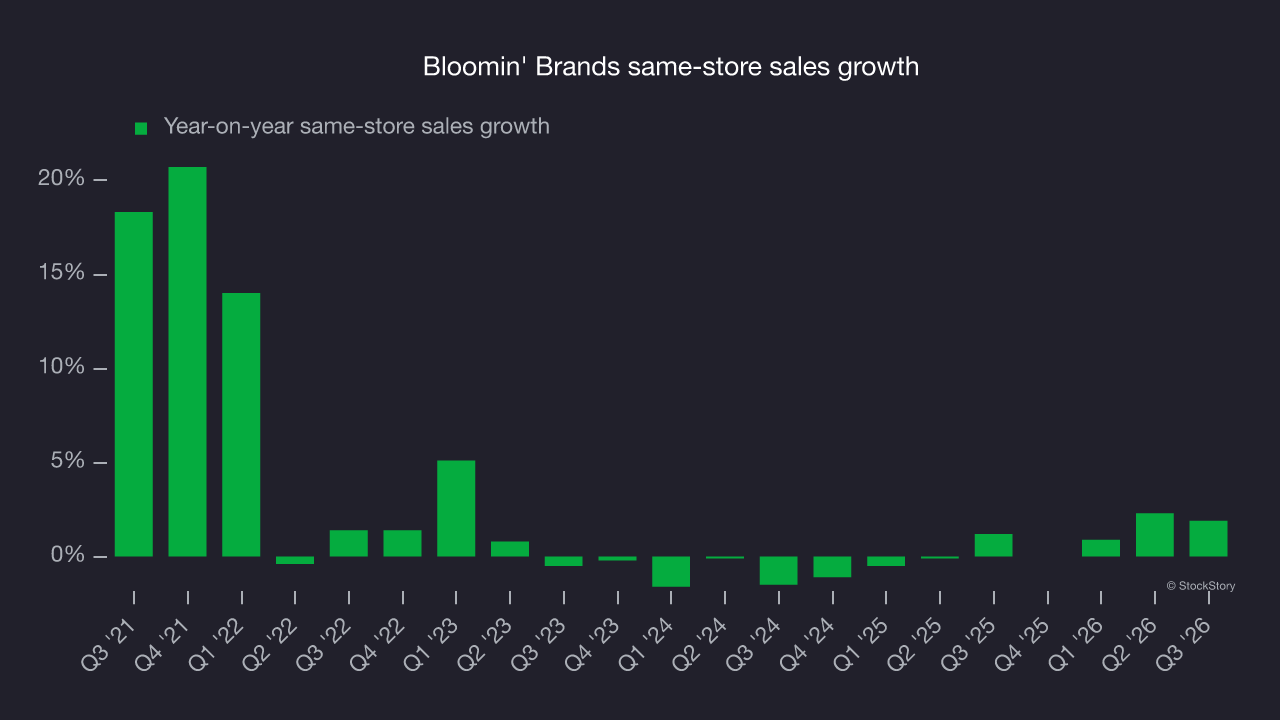
In the latest quarter, Bloomin' Brands’s same-store sales rose 1.9% year on year. This growth marked an acceleration from its historical levels, a positive sign.
Key takeaways from Bloomin' Brands’s Q3 results
Bloomin' Brands delivered some key positives in Q3, with revenue above analysts’ consensus estimates and full-year EPS guidance ahead of Wall Street’s consensus. But its EPS outlook for next quarter fell short of expectations. Investors were likely hoping for more, and shares fell 2.8% to $10.17 immediately after the results.
Considering an investment in Bloomin' Brands? If you’re making that decision, you should consider the bigger picture of valuation and business quality, as well as the latest earnings. We cover that in our full research report, which you can read here (it’s free).




