
Cable, internet and telephone services provider Charter (NASDAQ: CHTR) announced better-than-expected revenue in Q3 2026, with revenue up 9.1% year on year to $14.92 billion. Its GAAP loss of $20.50 per share was significantly below analysts’ consensus estimates.
For more on Charter, read our free full research report.
Charter (CHTR) Q3 2026 highlights:
- Revenue $14.92 billion vs S&P analysts’ consensus estimates of $13.54 billion (9.1% year-on-year growth, 10.2% beat)
- EPS (GAAP) -$20.50 vs analysts’ consensus estimates of $8.93 (significant miss)
- Adjusted EBITDA $5.94 billion vs analysts’ consensus estimates of $6.06 billion (39.8% margin, 1.9% miss)
- Operating margin -23.6%, down from 22.9% in the same quarter last year
- Free cash flow margin 4.5%, down from 10.5% in the same quarter last year
- Internet subscribers increased by 4.52 million year on year
- Market capitalization $14.41 billion
Revenue growth
A company’s long-term performance is an indicator of its overall quality. Any business can experience short-term success, but top-performing ones enjoy sustained growth for years. Charter’s revenue grew at a weak 1.7% compounded annual growth rate over the last five years, falling short of our standards.
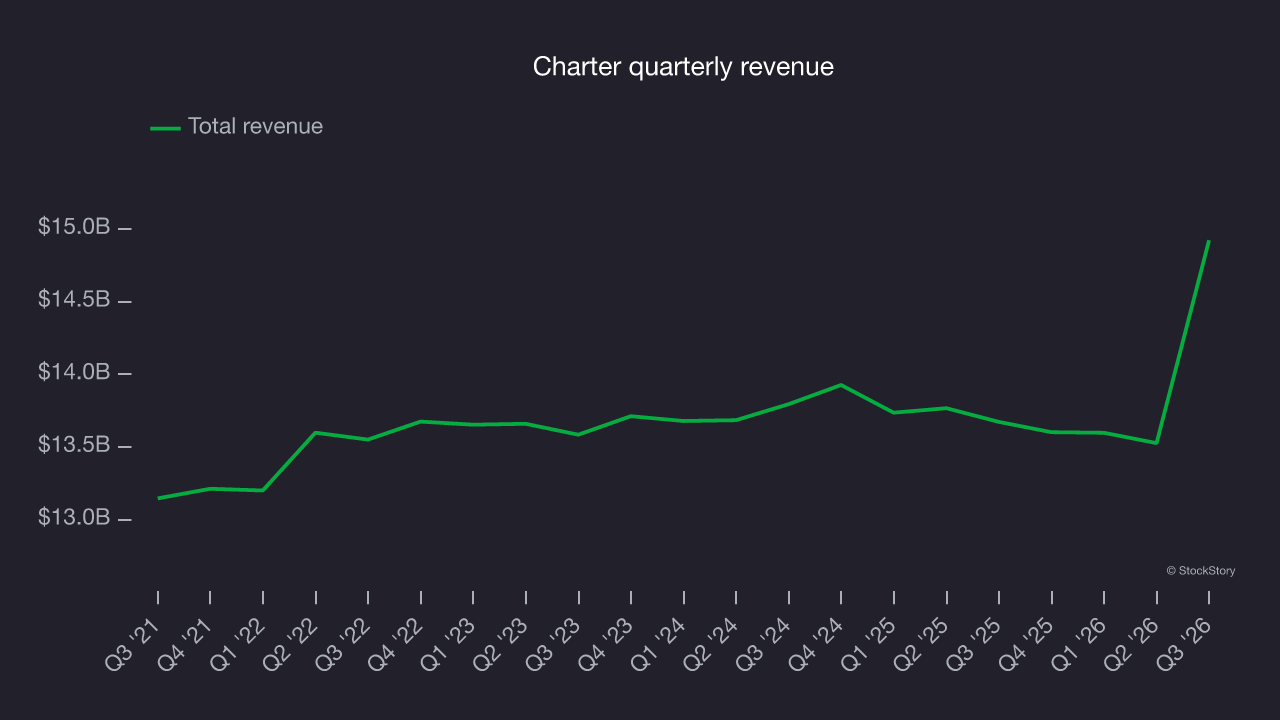
Long-term growth matters most, but within consumer discretionary, a stretched historical view may miss a company riding a successful new product or trend. Charter’s recent performance shows its demand has slowed as its revenue was flat over the last two years. 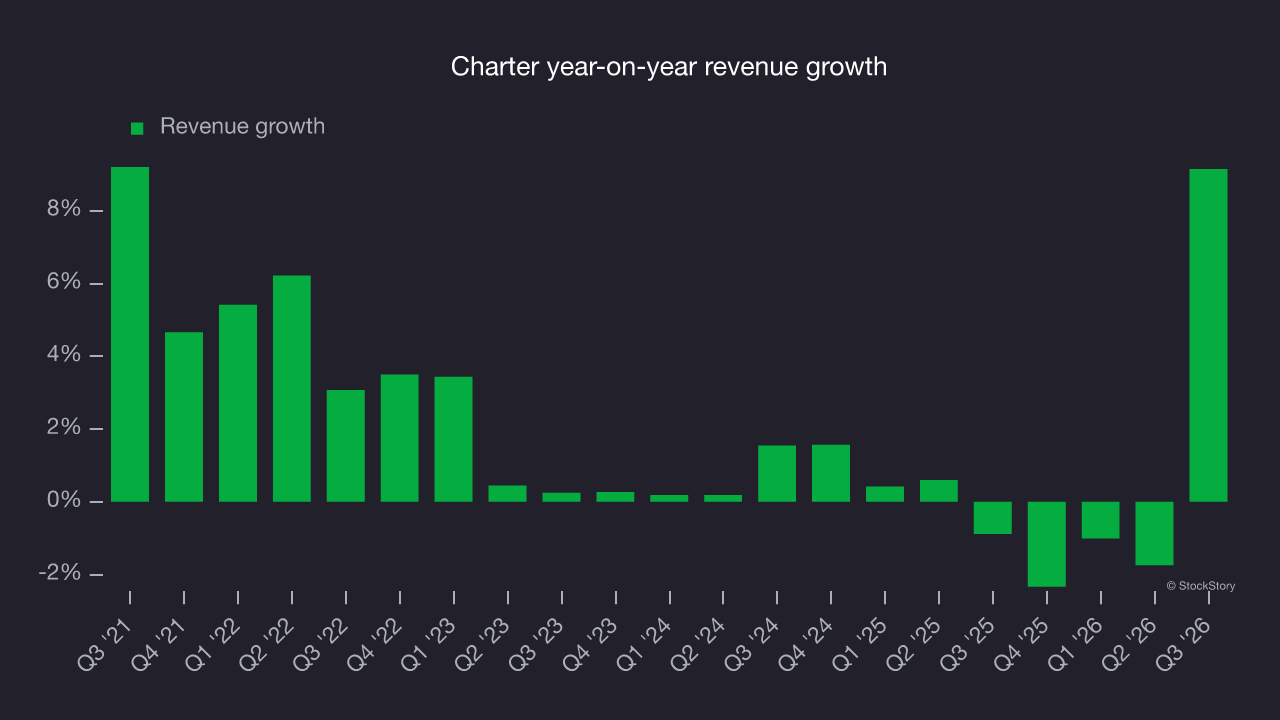
Charter also discloses its number of internet subscribers and video subscribers, which totaled 34.31 million and 13.8 million in the latest quarter. Over the last two years, Charter’s internet subscribers averaged 4.1% year-on-year growth while its video subscribers were flat. 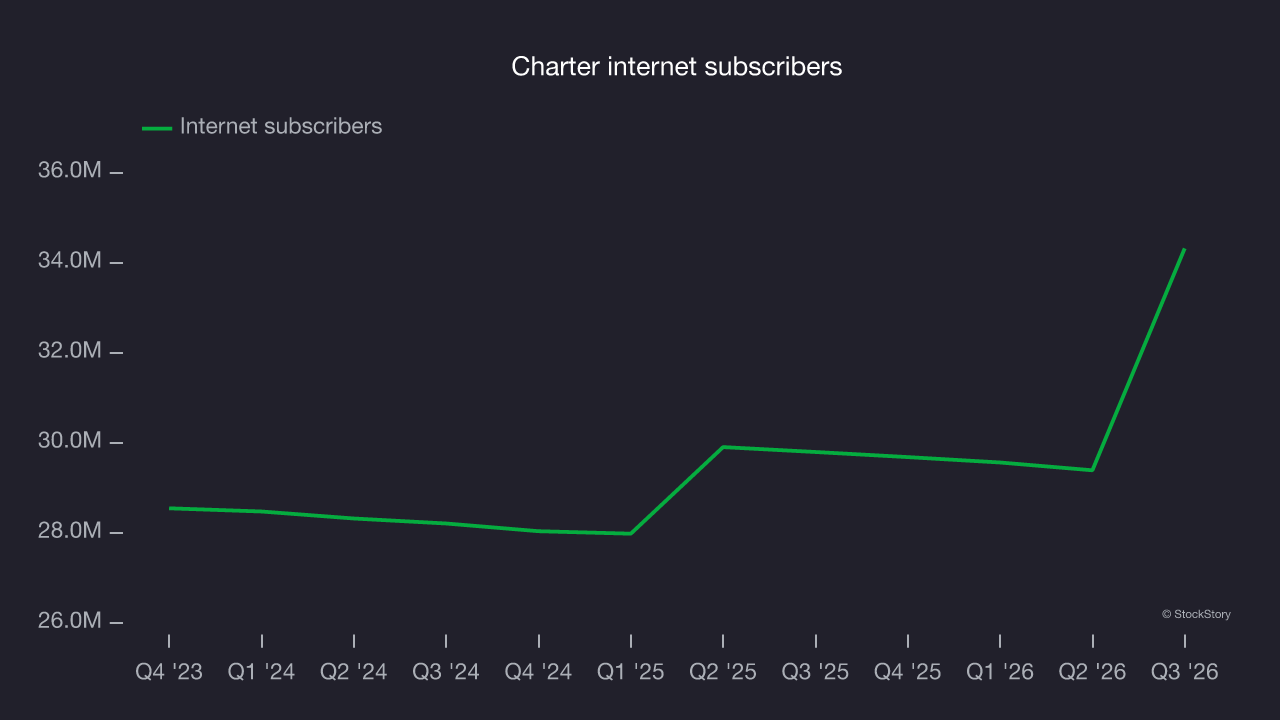
This quarter, Charter reported year-on-year revenue growth of 9.1%, and its $14.92 billion of revenue exceeded Wall Street’s consensus estimates by 10.2%.
Looking ahead, sell-side analysts expect revenue to decline by 3.5% over the next 12 months, according to S&P, a deceleration versus the last two years. This projection is underwhelming and suggests its products and services will face some demand challenges.
Operating margin
Operating margin is an important measure of profitability as it shows the portion of revenue left after accounting for all core expenses, from the cost of goods sold to advertising and wages. It’s also useful for comparing profitability across companies with different levels of debt and tax rates because it excludes interest and taxes.
Charter’s operating margin has been trending down over the last 12 months and averaged 17.2% over the last two years. The company’s profitability was mediocre for a consumer discretionary business and shows it couldn’t pass its higher operating expenses on to its customers.
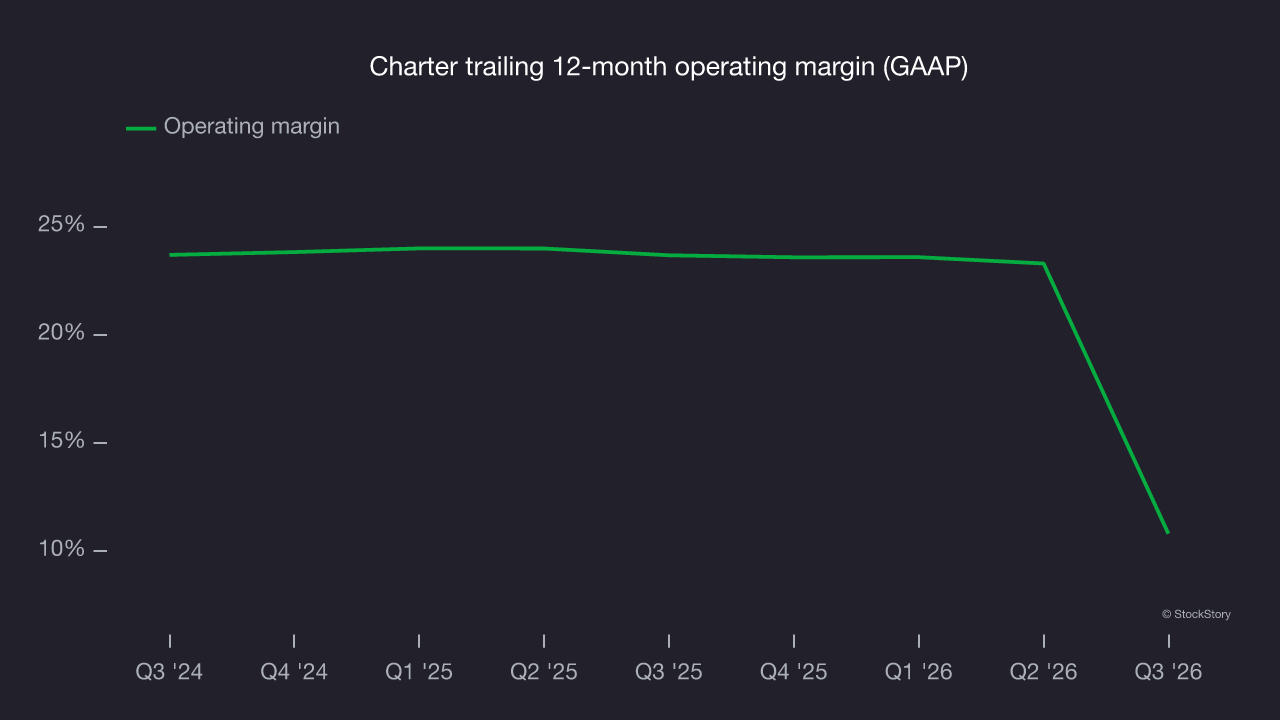
In Q3, Charter generated an operating margin of negative 23.6%, down 46.5 percentage points year on year. This contraction shows it was less efficient because its expenses grew faster than its revenue.
Earnings per share
Long-term changes in earnings per share, or EPS, matter for the same reason as long-term revenue growth. Compared to revenue, however, EPS highlights whether a company’s growth is profitable.
Charter’s EPS declined by 14.7% annually over the last five years while its revenue grew by 1.7%. This indicates the company became less profitable on a per-share basis as it expanded due to non-fundamental factors such as interest expenses and taxes.
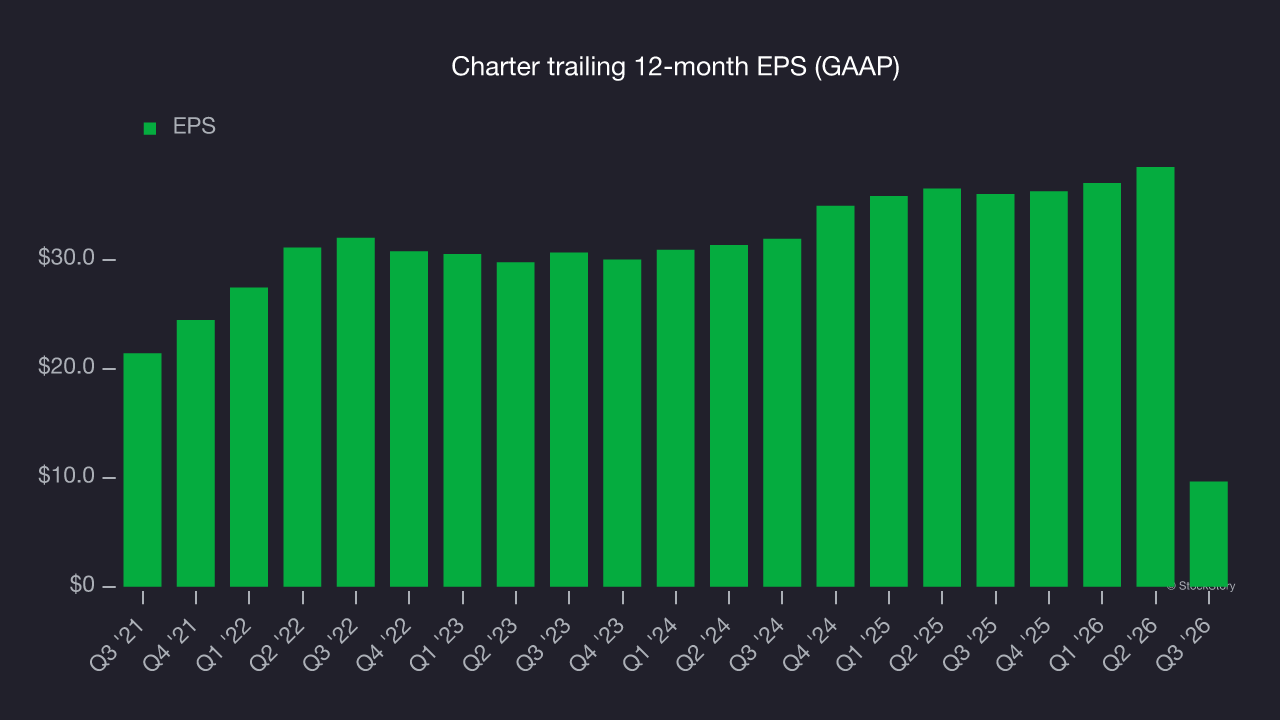
In Q3, Charter reported EPS of negative $20.50, down from $8.34 in the same quarter last year. This result missed analysts’ consensus estimates. Over the next 12 months, Wall Street expects Charter’s full-year EPS to grow 387% from $9.65 to $47.06, according to S&P.
Key takeaways from Charter’s Q3 results
Charter’s revenue came in well above analysts’ consensus estimates, but an EPS miss left the quarter weaker overall. Shares tumbled 5.8% to $117.93 immediately after the release.
When deciding whether to buy Charter at its current price, the latest quarter matters, but not nearly as much as longer-term fundamentals and valuation. For more on those factors, read our full research report here (it’s free).




