Fuel cell technology company Plug Power (NASDAQ: PLUG) reported Q3 2026 results beating Wall Street’s revenue expectations, with revenue up 13.3% year on year to $200.6 million. Its GAAP loss of $0 per share was significantly above analysts’ consensus estimates.
For more on Plug Power, read our free full research report.
Plug Power (PLUG) Q3 2026 highlights:
- Revenue $200.6 million vs analysts' consensus estimates of $198.2 million, according to S&P (13.3% year-on-year growth, 1.2% beat)
- EPS (GAAP) $0 vs analysts' consensus estimates of -$0.06 (significant beat)
- Operating margin -37.5%, up from -197% in the same quarter last year
- Free cash flow -$79.69 million compared to -$117.5 million in the same quarter last year
- Market capitalization $2.03 billion
"Our third quarter results reflect continued progress toward a stronger, more profitable Plug," said Jose Luis Crespo, Chief Executive Officer of Plug. "We grew revenue, improved margins, and significantly reduced cash usage through disciplined execution. Commercially, we advanced key customer projects, including our 280 MW Arcadia eFuels agreement and broader partnership covering more than 1 GW of potential projects. Our focus remains on improving operating leverage, delivering on customer commitments and building sustainable growth."
Revenue growth
A company’s long-term revenue performance is one signal of its overall quality. Any business can experience short-term success, but top-performing ones sustain growth for years. Plug Power’s revenue grew at a strong 9.8% compounded annual growth rate over the last five years. Its growth beat the average industrials company and shows its offerings resonate with customers.
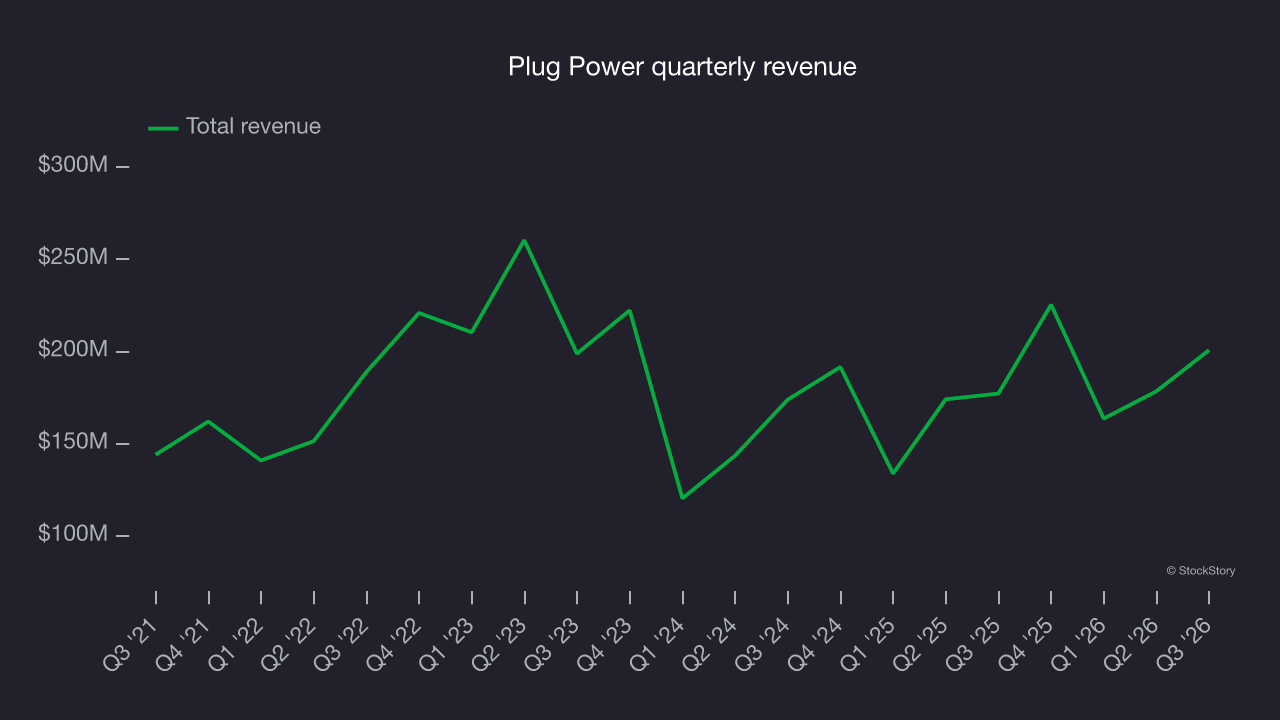
Long-term growth is the most important, but within industrials, a half-decade historical view may miss new industry trends or demand cycles. Plug Power’s annualized revenue growth of 7.9% over the last two years is below its five-year trend, but the results still suggest healthy demand.
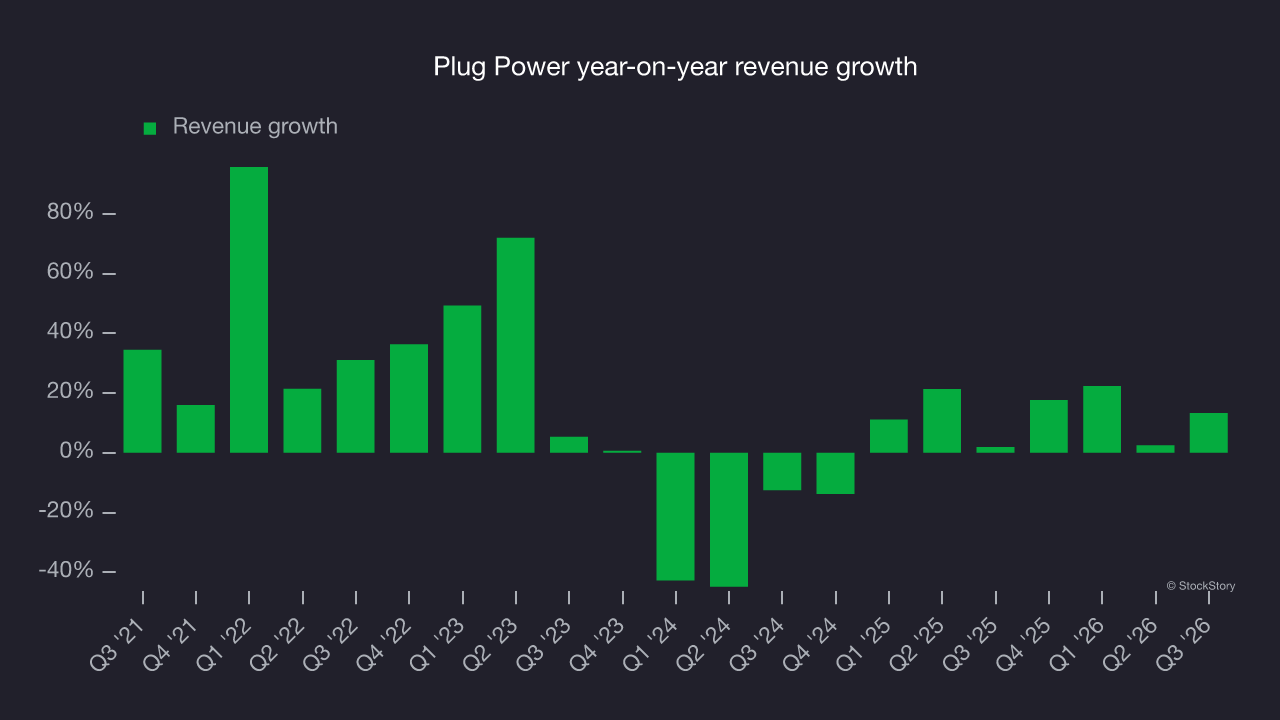
This quarter, Plug Power reported year-on-year revenue growth of 13.3%, and its $200.6 million of revenue exceeded Wall Street’s consensus estimates by 1.2%.
Looking ahead, sell-side analysts expect revenue to grow 23.5% over the next 12 months, according to S&P, an improvement versus the last two years. This strong projection indicates its newer products and services will drive better revenue performance.
Operating margin
Operating margin is an important measure of profitability as it shows the portion of revenue left after accounting for all core expenses – everything from the cost of goods sold to advertising and wages. It’s also useful for comparing profitability across companies with different levels of debt and tax rates because it excludes interest and taxes.
Over the last five years, Plug Power’s operating margin fell by 31.2 percentage points. This deterioration shows its costs grew relative to revenue, putting pressure on profitability. Its trailing 12-month operating margin was negative 132%.
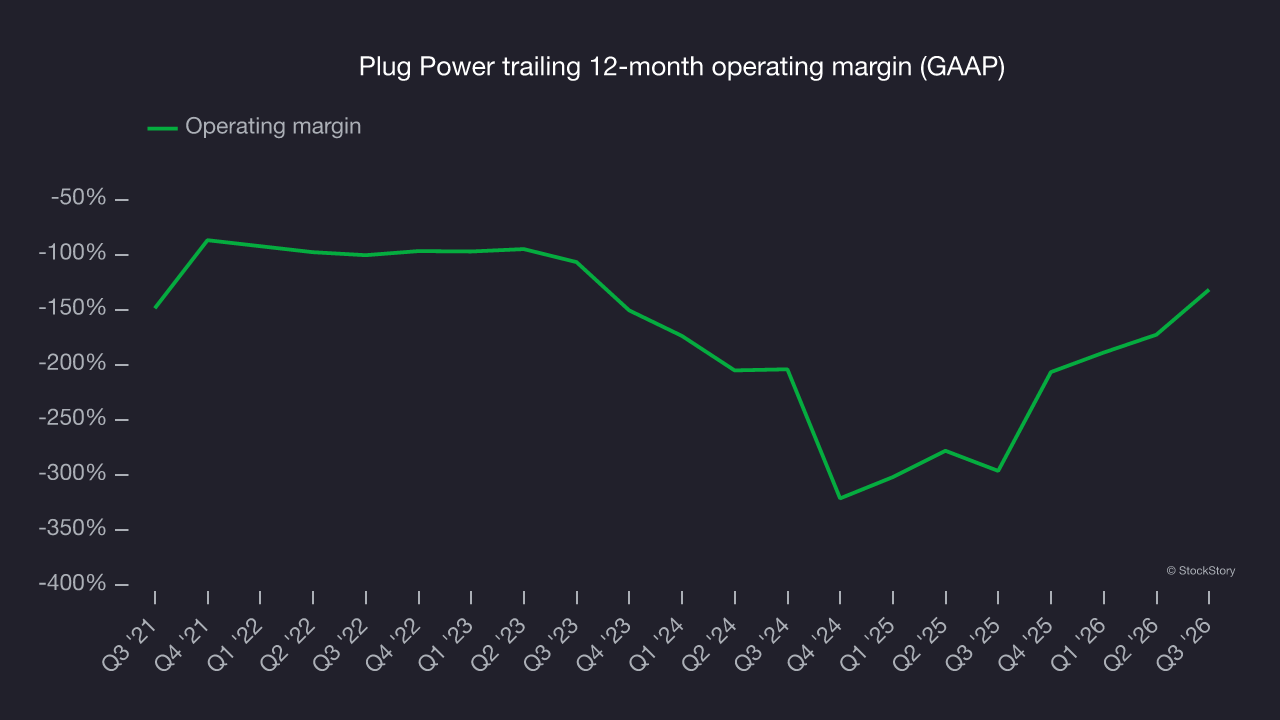
In Q3, Plug Power generated a negative 37.5% operating margin.
Earnings per share
Long-term changes in earnings per share (EPS) matter for the same reason as long-term revenue growth. Compared to revenue, however, EPS highlights whether a company’s growth is profitable.
Although Plug Power’s full-year earnings are still negative, it reduced its losses and improved its EPS by 9.5% annually over the last five years. The next few quarters will be critical for assessing its long-term profitability.
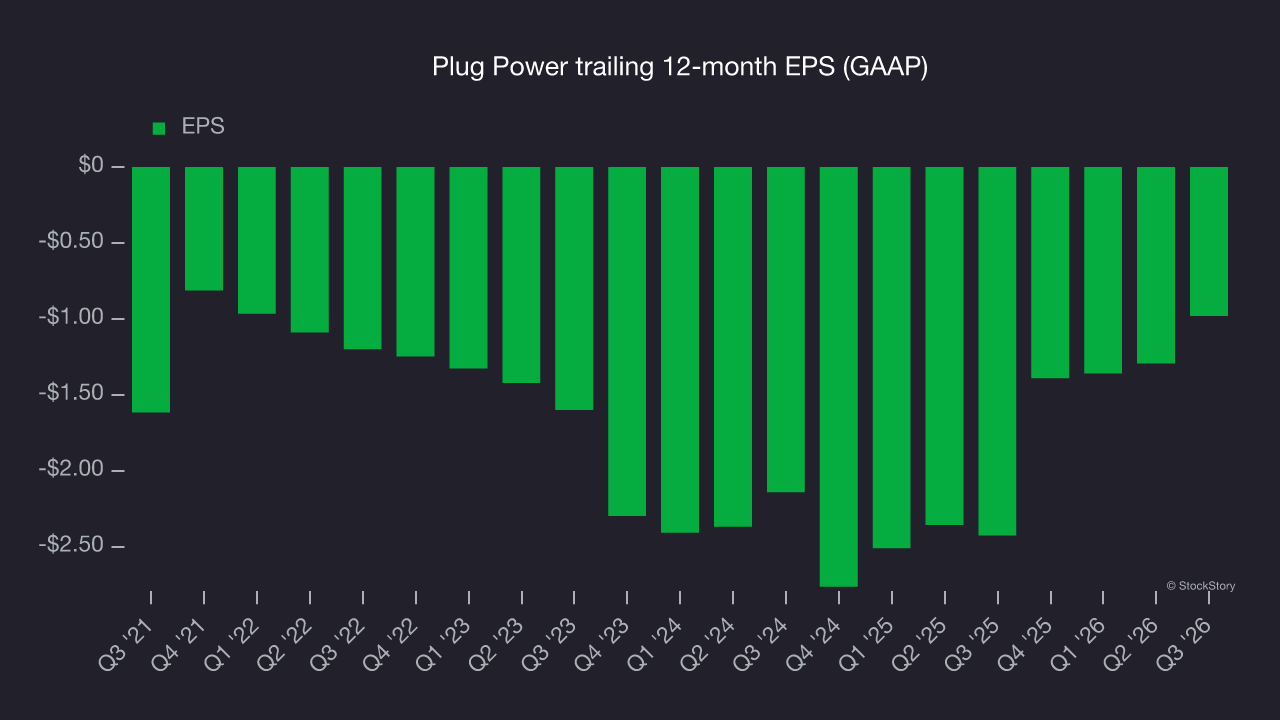
As with revenue, looking at EPS over a more recent period can provide insight into an emerging theme or development for the business.
For Plug Power, its two-year annual EPS growth of 32.4% was higher than its five-year trend. Its improving earnings are an encouraging data point, but a caveat is that its EPS is still in the red.
In Q3, Plug Power reported EPS of $0, up from negative $0.31 in the same quarter last year. This result came in well above analysts’ consensus estimates, a positive for shareholders. Over the next 12 months, Wall Street expects Plug Power to narrow its losses. Analysts forecast its full-year EPS will improve from negative $0.98 to negative $0.17, according to S&P.
Key takeaways from Plug Power’s Q3 results
Plug Power delivered a solid quarter, beating analysts’ consensus estimates for EPS and narrowly topping Wall Street’s revenue expectations. Shares edged higher 1.7% to $1.53 immediately after the report.
Plug Power had a solid quarterly earnings result, but the investment case requires a broader view. Investors should consider valuation, business quality and the latest earnings. Read the full research report here for more on Plug Power (it’s free).