As the Q2 earnings season wraps, let’s dig into this quarter’s best and worst performers in the home builders industry, including Installed Building Products (NYSE: IBP) and its peers.
Traditionally, homebuilders have built competitive advantages with economies of scale that lead to advantaged purchasing and brand recognition among consumers. Aesthetic trends have always been important in the space, but more recently, energy efficiency and conservation are driving innovation. However, these companies are still at the whim of the macro, specifically interest rates that heavily impact new and existing home sales. In fact, homebuilders are one of the most cyclical subsectors within industrials.
The 10 home builders stocks we track reported a mixed Q2. As a group, revenues beat analysts’ consensus estimates by 0.6%.
Amidst this news, share prices of the companies have had a rough stretch. On average, they are down 7.7% since the latest earnings results.
Best Q2: Installed Building Products (NYSE: IBP)
Founded in 1977, Installed Building Products (NYSE: IBP) is a company specializing in the installation of insulation, waterproofing, and other complementary building products for residential and commercial construction.
Installed Building Products reported revenues of $777.8 million, up 2.3% year on year. This print exceeded analysts’ expectations by 4.4%. Overall, it was a stunning quarter for the company with a solid beat of analysts’ EBITDA and EPS estimates.
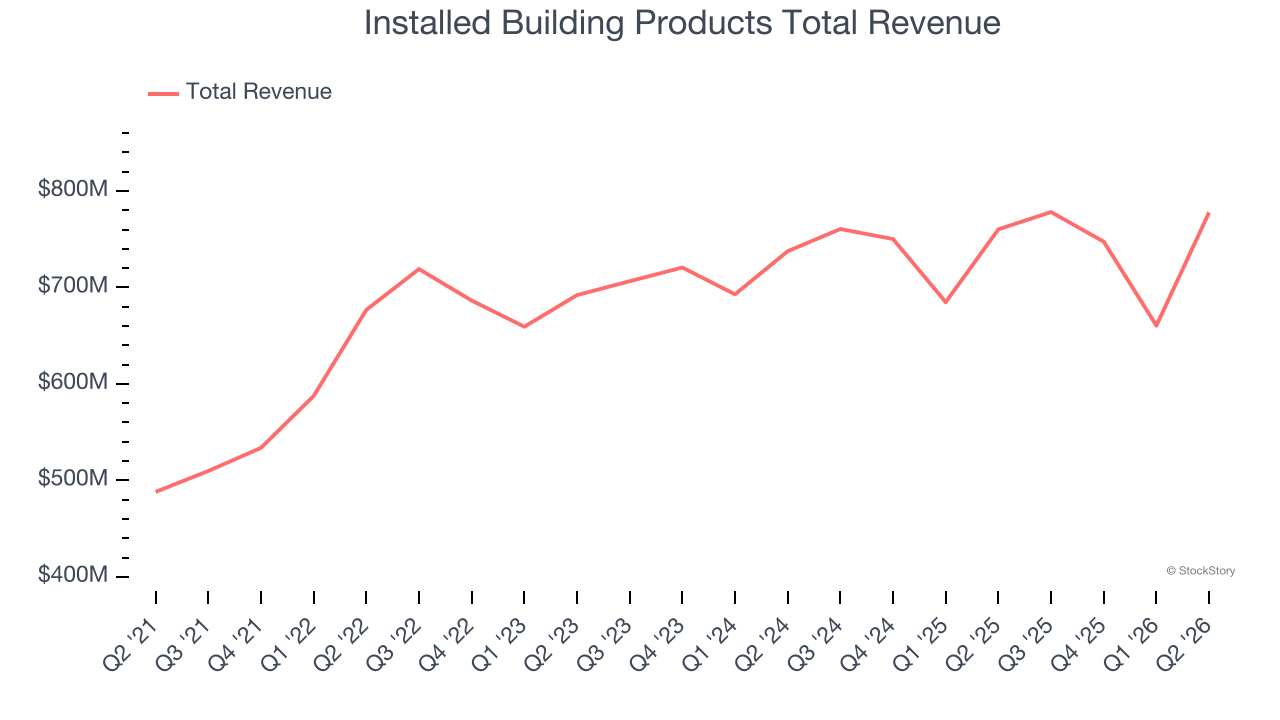
Installed Building Products pulled off the biggest analyst estimate beat among its peers. Investor expectations, however, were likely higher than Wall Street’s published projections, leaving some wishing for even better results (analysts’ consensus estimates are those published by big banks and advisory firms, not the investors who make buy and sell decisions). The stock is down 15.1% since reporting and currently trades at $205.
Is now the time to buy Installed Building Products? Access our full analysis of the earnings results here, it’s free.
LGI Homes (NASDAQ: LGIH)
Based in Texas, LGI Homes (NASDAQ: LGIH) is a homebuilding company specializing in constructing affordable, entry-level single-family homes in desirable communities across the United States.
LGI Homes reported revenues of $501.5 million, up 3.7% year on year, outperforming analysts’ expectations by 2.9%. The business had a very strong quarter.
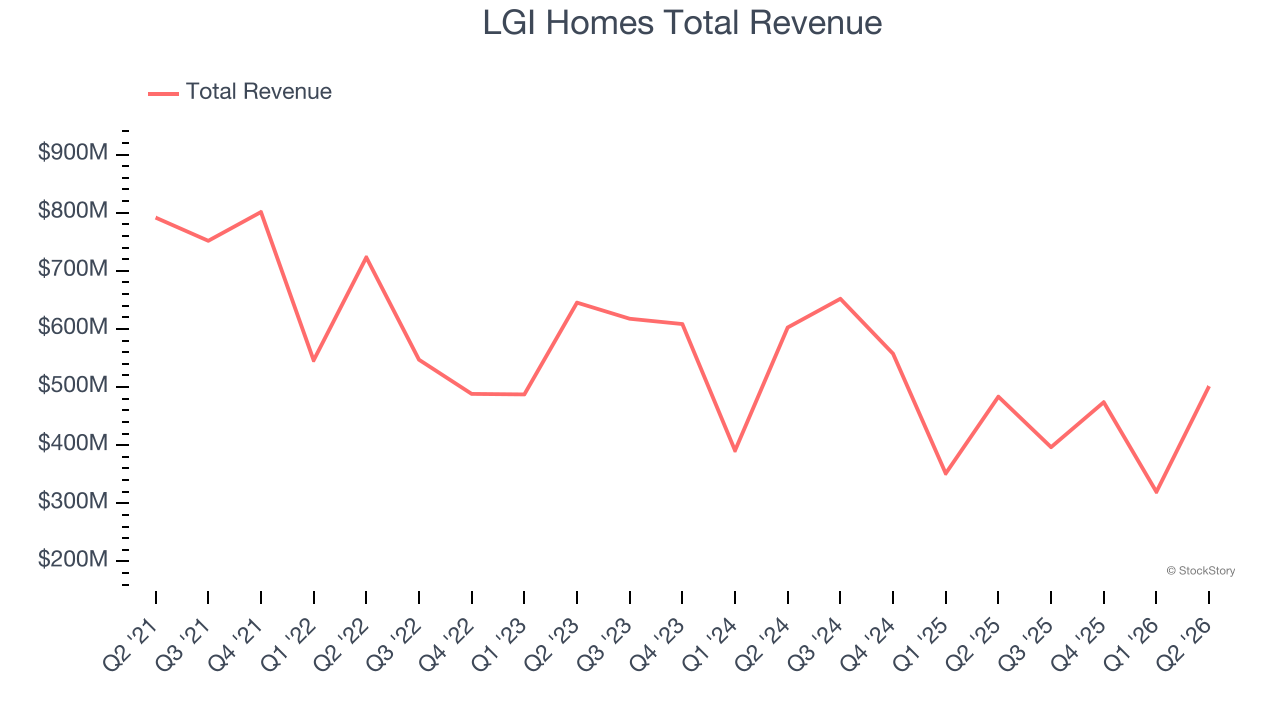
LGI Homes scored the fastest revenue growth of the whole group. Although it had a fine quarter compared to its peers, the market seems unhappy with the results as the stock is down 11.9% since reporting. It currently trades at $49.43.
Is now the time to buy LGI Homes? Access our full analysis of the earnings results here, it’s free.
Weakest Q2: NVR (NYSE: NVR)
Known for its unique land acquisition strategy, NVR (NYSE: NVR) is a respected homebuilder and mortgage company in the United States.
NVR reported revenues of $2.33 billion, down 10.5% year on year, falling short of analysts’ expectations by 3.9%. It was a disappointing quarter as it posted a significant miss of analysts’ EPS estimates.
NVR delivered the weakest performance against analyst estimates in the group. As expected, the stock is down 3% since the results and currently trades at $6,161.
Read our full analysis of NVR’s results here.
D.R. Horton (NYSE: DHI)
One of the largest homebuilding companies in the U.S., D.R. Horton (NYSE: DHI) builds a variety of new construction homes across multiple markets.
D.R. Horton reported revenues of $9.23 billion, flat year on year. This number was in line with analysts’ expectations. Taking a step back, it was a slower quarter as it logged full-year revenue guidance missing analysts’ expectations significantly.
The stock is down 4.7% since reporting and currently trades at $137.94.
Read our full, actionable report on D.R. Horton here, it’s free.
PulteGroup (NYSE: PHM)
Having delivered over 850,000 homes since its founding in 1950, PulteGroup (NYSE: PHM) is one of America's largest homebuilders, constructing single-family homes, townhouses, and condominiums for first-time, move-up, and active adult buyers across 46 markets in 25 states.
PulteGroup reported revenues of $3.98 billion, down 9.6% year on year. This print topped analysts’ expectations by 1.1%. Overall, it was a strong quarter as it also recorded a beat of analysts’ EPS estimates.
The stock is down 4.8% since reporting and currently trades at $118.25.
Read our full, actionable report on PulteGroup here, it’s free.
Market Update
Over the past year, investors have been forced to repeatedly answer the same question: what is the market’s biggest risk? The answer has changed several times, and each shift has reshaped market leadership.
Late in 2025 and early 2026, artificial intelligence became the market’s primary uncertainty. Investors questioned whether AI would erode software pricing power and weaken competitive moats as AI made it easier to replicate once-differentiated products.
By the spring, technology took a back seat to geopolitics. The U.S. conflict with Iran briefly became the market’s dominant narrative, raising concerns about oil prices, inflation, and global growth. But as energy markets remained orderly and fears of a prolonged supply disruption faded, investors quickly turned their focus back to fundamentals.
Want to invest in winners with rock-solid fundamentals? Check out our Strong Momentum Stocks and add them to your watchlist. These companies are poised for growth regardless of the political or macroeconomic climate.