Wintrust Financial has been treading water for the past six months, recording a small loss of 2.7% while holding steady at $143.30. The stock also fell short of the S&P 500’s 12.8% gain during that period.
Is now the time to buy Wintrust Financial, or should you be careful about including it in your portfolio? Check out our in-depth research report to see what our analysts have to say, it’s free.
Why Is Wintrust Financial Not Exciting?
We’re passing on Wintrust Financial for now. Here are two reasons we avoid WTFC, plus one stock we’d rather own.
1. Net Interest Margin Dropping
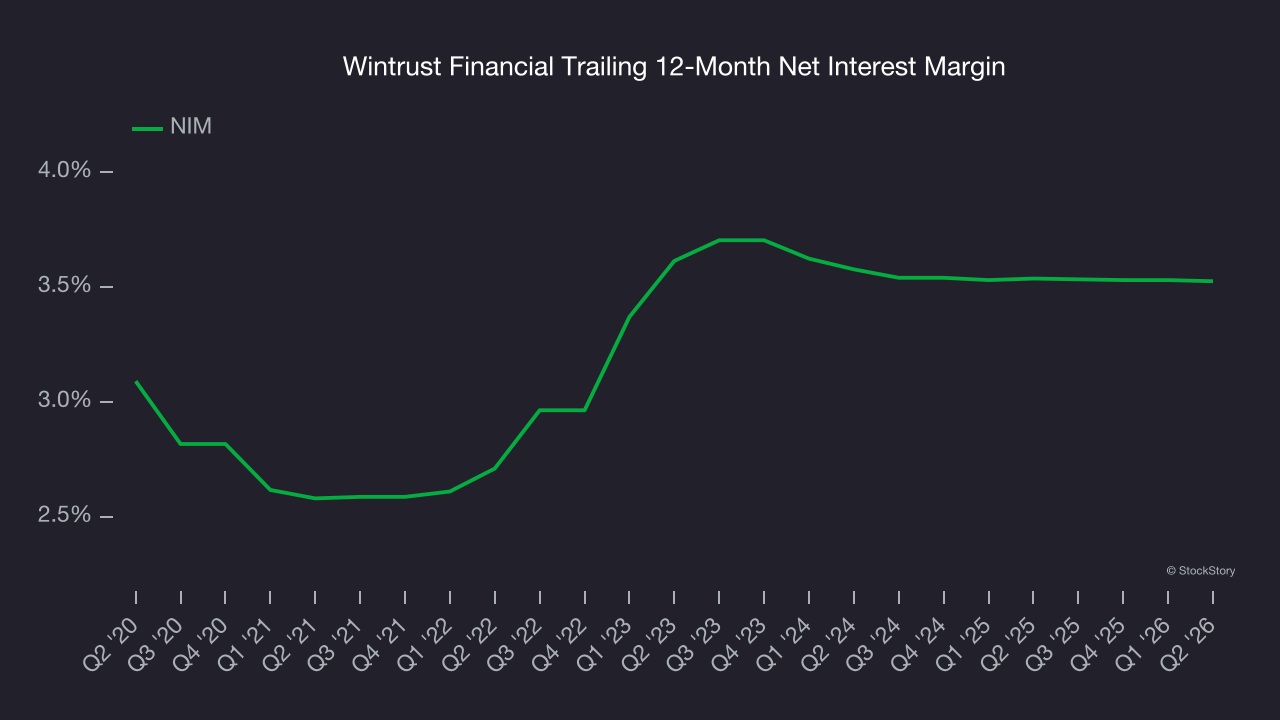
Net interest margin (NIM) represents how much a bank earns in relation to its outstanding loans. It’s one of the most important metrics to track because it shows how a bank’s loans are performing and whether it has the ability to command higher premiums for its services.
Over the past two years, Wintrust Financial’s net interest margin averaged 3.5%. However, its margin contracted by 5.2 basis points (100 basis points = 1 percentage point) over that period.
This decline was a headwind for its net interest income. While prevailing rates are a major determinant of net interest margin changes over time, the decline could mean Wintrust Financial either faced competition for loans and deposits or experienced a negative mix shift in its balance sheet composition.
2. Projected TBVPS Growth Is Slim
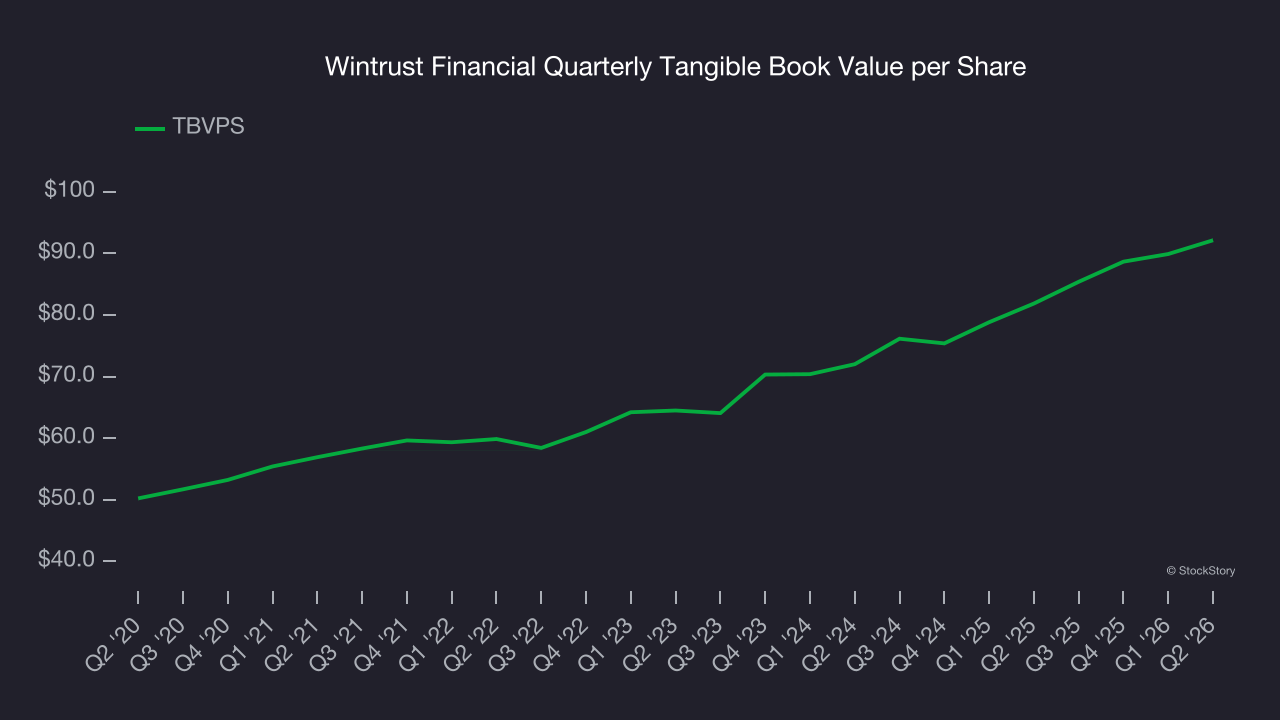
Tangible book value per share (TBVPS) growth is driven by a bank’s ability to earn more than its cost of capital through lending activities while maintaining a strong balance sheet.
Over the next 12 months, Consensus estimates call for Wintrust Financial’s TBVPS to grow by 12.4% to $103.54, mediocre growth rate.
Final Judgment
Wintrust Financial isn’t a terrible business, but it doesn’t pass our bar. With its shares underperforming the market lately, the stock trades at 1.3× forward P/B (or $143.30 per share). While this valuation is fair, the upside isn’t great compared to the potential downside. We’re fairly confident there are better investments elsewhere. Let us point you toward our favorite semiconductor picks and shovels play.
Stocks We Like More Than Wintrust Financial
WHILE YOU’RE HERE: Top 9 Market-Beating Stocks. The best stocks don’t just beat the market once. They do it again. And again. Robust revenue growth, rising free cash flow, returns on capital that leave their competition in the dust. The market has already rewarded these businesses.
But our AI platform says the party isn’t over. Find out which 9 stocks made the cut this week — FREE. Get Our Top 9 Market-Beating Stocks for Free HERE.
Stocks that have made our list include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-small-cap company Comfort Systems (+1,154% between June 2020 and June 2025). Find your next big winner with StockStory today.