Freight delivery company Werner (NASDAQ: WERN) met Wall Street’s revenue expectations in Q3 2026, with revenue rising 23.2% year on year to $950.5 million. Its non-GAAP profit of $0.16 per share was in line with analysts’ consensus estimates.
For more on Werner, read the full research report for free.
Werner (WERN) Q3 2026 highlights:
- Revenue $950.5 million vs S&P analysts’ consensus estimates of $954.8 million (23.2% year-on-year growth, in line)
- Adjusted EPS $0.16 vs S&P analysts’ consensus estimates of $0.16 (in line)
- Adjusted operating income $20.98 million vs analysts’ consensus estimates of $26.35 million (2.2% margin, 20.4% miss)
- Operating margin 1.8%, up from -1.7% in the same quarter last year
- Free cash flow -$15.81 million, down from $8.91 million in the same quarter last year
- Market capitalization $1.7 billion
“Werner’s third-quarter results demonstrate strong top-line momentum, highlighted by a 28% increase in freight revenue and double-digit Truckload Transportation Services (“TTS”) revenue per truck growth,” said Chairman and CEO Derek Leathers. “While rapidly rising fuel costs and elevated claims temporarily impacted near-term margins, our underlying strategy is working, driving a near-doubling of adjusted operating income. We made the deliberate decision to accelerate investments in driver recruiting and onboarding to capture rising customer demand and support fleet expansion as industry capacity tightens. We remain confident in our trajectory and our ability to capitalize on the early stages of this freight upcycle.”
Revenue growth
A company’s long-term revenue performance is one signal of its overall quality. Any business can deliver a good quarter or two, but the best consistently grow over the long term. Werner’s revenue grew at a tepid 5.8% compounded annual growth rate over the last five years, falling short of our benchmark for the industrials sector.
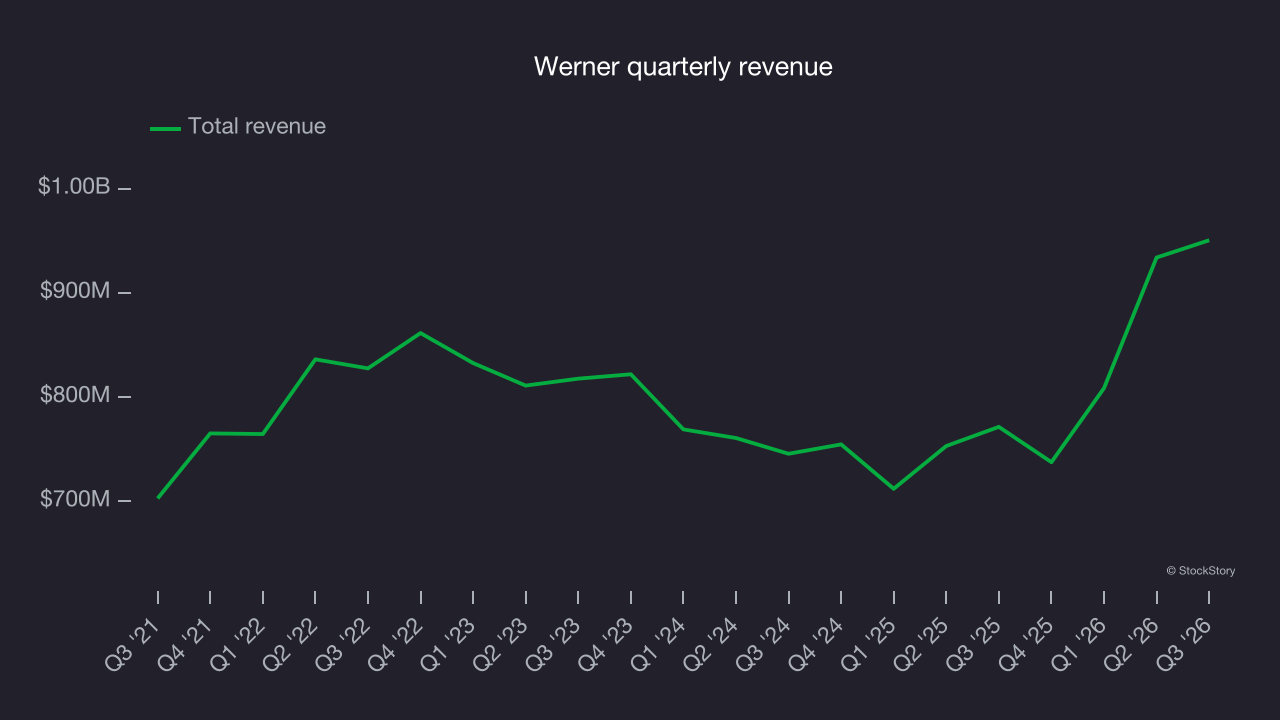
Long-term growth is the most important, but within industrials, a half-decade historical view may miss new industry trends or demand cycles. Werner’s annualized revenue growth of 5.2% over the last two years aligns with its five-year trend, suggesting its demand was consistently weak. 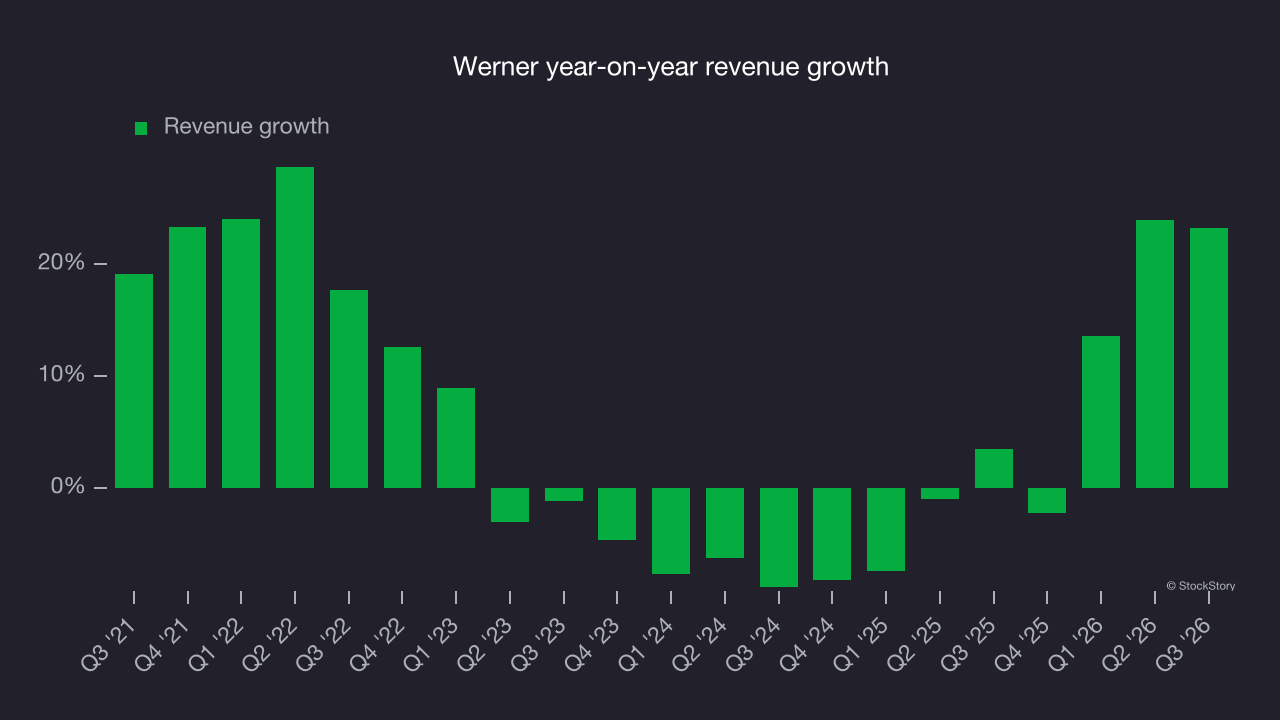
Werner also breaks out the revenue for its most important segments, Truckload Transportation and Logistics, which are 75.1% and 22.7% of revenue. Over the last two years, Werner’s Truckload Transportation revenue (deliveries made with Werner's fleet) averaged 13.2% year-on-year growth while its Logistics revenue (brokered deliveries using third-party fleets) was flat. 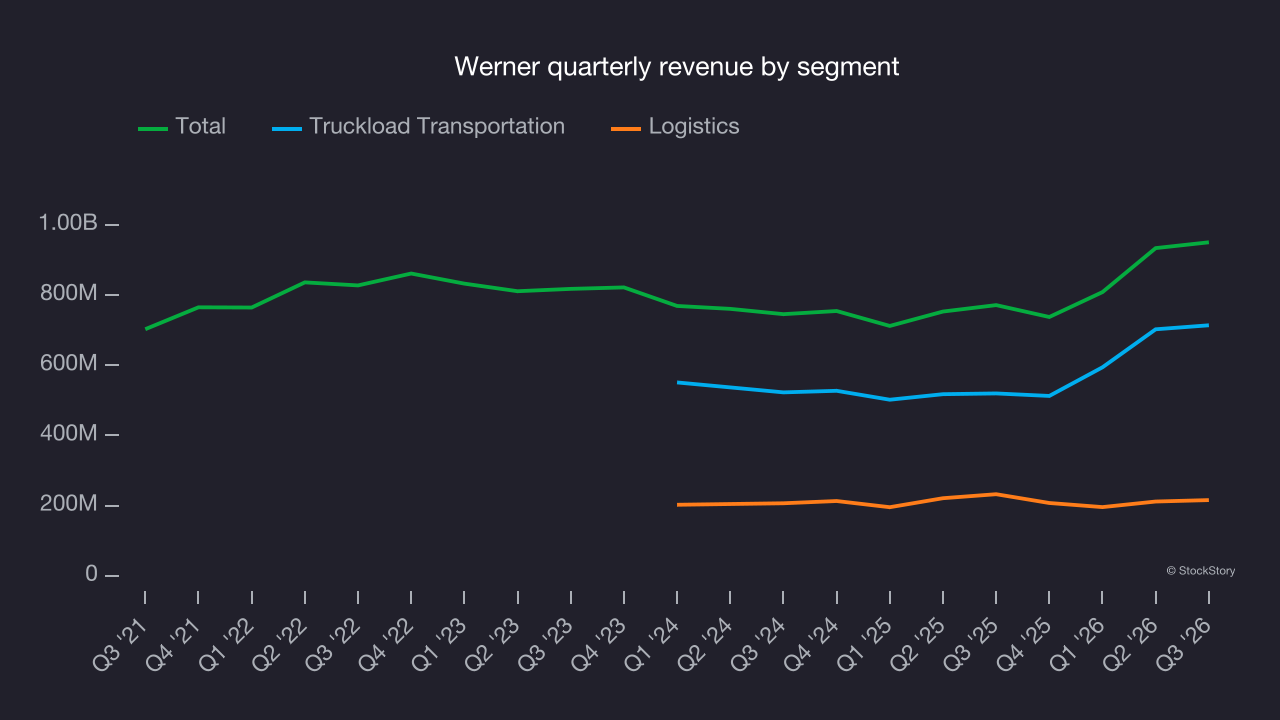
This quarter, Werner’s year-on-year revenue growth of 23.2% was strong, and its $950.5 million of revenue was in line with Wall Street’s consensus estimates.
Looking ahead, sell-side analysts expect revenue to grow 13% over the next 12 months, according to S&P, an improvement versus the last two years. This projection is healthy and indicates its newer products and services will improve revenue performance.
Operating margin
Operating margin is one of the best measures of profitability because it tells us how much a company earns after procuring and manufacturing its products, marketing and selling those products and, most importantly, keeping them relevant through research and development.
Werner was profitable over the last five years but held back by its large cost base. Its average operating margin of 4.5% was weak for an industrials business. That outcome is unsurprising given its low gross margin baseline.
Looking at the trend in its profitability, Werner’s operating margin decreased by 10.4 percentage points over the last five years. This raises questions about the company’s expense base because its revenue growth should have given it leverage on its fixed costs, resulting in better economies of scale and profitability. Werner’s poor performance shows that costs were rising and it couldn’t pass them on to its customers.
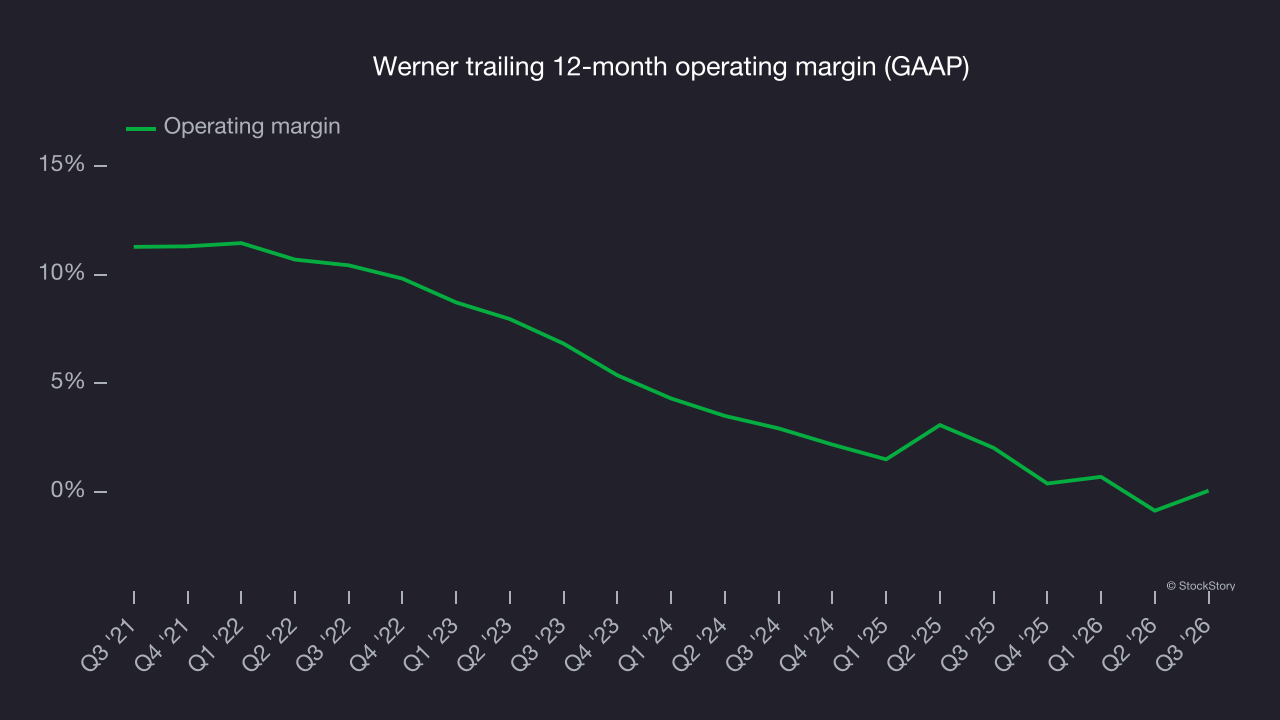
In Q3, Werner reported an operating margin of 1.8%, up 3.5 percentage points year on year. Its gross margin expanded more than its operating margin, indicating that leverage on its cost of sales was the primary driver of the recent efficiency gains.
Earnings per share
Revenue trends explain a company’s historical growth, but the long-term change in earnings per share (EPS) points to the profitability of that growth – for example, a company could inflate its revenue through excessive spending on advertising and promotions.
Werner’s EPS declined by 32.5% annually over the last five years while its revenue grew by 5.8%. This indicates the company became less profitable on a per-share basis as it expanded due to non-fundamental factors such as interest expenses and taxes.
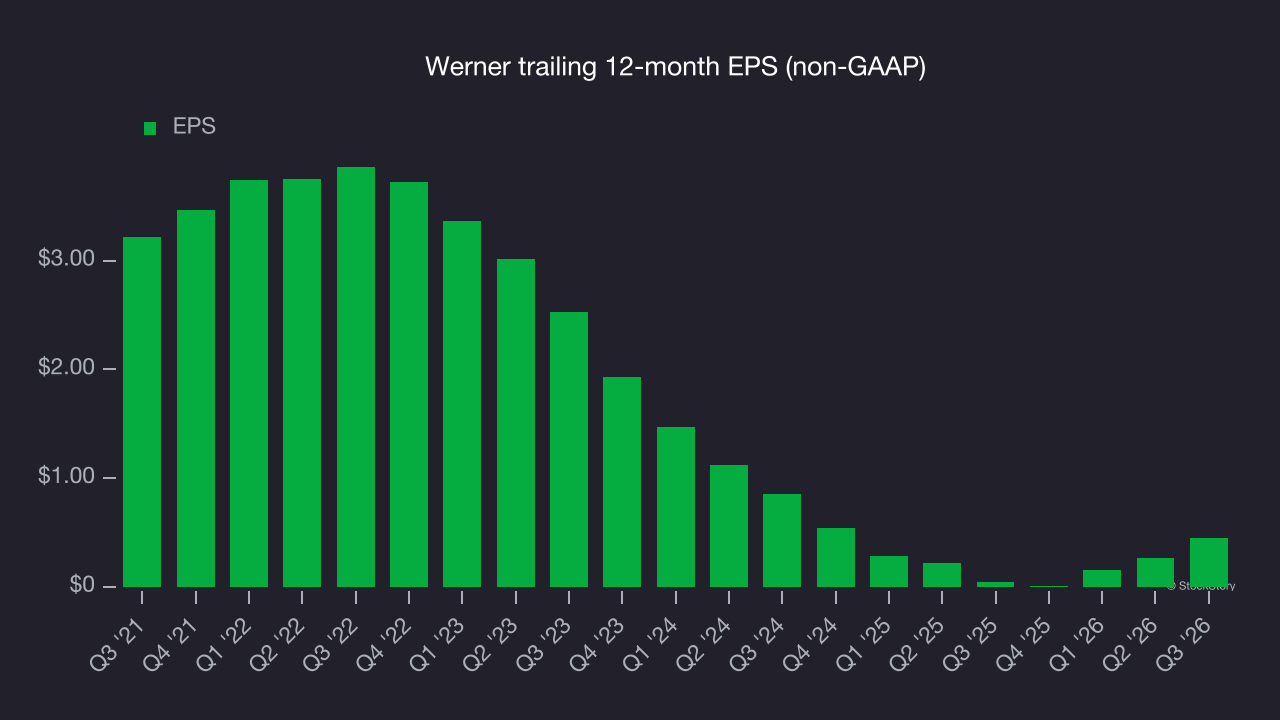
We can take a deeper look into Werner’s earnings to better understand the drivers of its performance. As we mentioned earlier, Werner’s operating margin expanded this quarter but declined by 10.4 percentage points over the last five years. This was the most relevant factor (aside from the revenue impact) behind its lower earnings; interest expenses and taxes can also affect EPS but don’t tell us as much about a company’s fundamentals.
Like with revenue, we analyze EPS over a more recent period because it can provide insight into an emerging theme or development for the business.
For Werner, its two-year annual EPS declines of 27.2% show it’s still underperforming. The results were poor over both periods.
In Q3, Werner reported adjusted EPS of $0.16, up from negative $0.03 in the same quarter last year. This beat analysts’ consensus estimates by 2.3%. Over the next 12 months, Wall Street expects Werner’s full-year EPS to grow 290% from $0.45 to $1.76, according to S&P.
Key takeaways from Werner’s Q3 results
Werner’s adjusted operating income missed expectations, and revenue only met Wall Street’s consensus estimates, leaving few positives in a softer quarter. Shares fell 2.3% to $28.70 immediately after the results.
Werner’s latest quarter was underwhelming. One earnings report doesn’t define a company’s quality, though, so let’s examine whether the stock is a buy at the current price. The latest quarter does matter, but not nearly as much as longer-term fundamentals and valuation when deciding if the stock is a buy. For more on Werner, read our full research report here (it’s free).