Peloton trades at $5 per share and has stayed right on track with the overall market, gaining 16.3% over the last six months. At the same time, the S&P 500 has returned 16.6%.
Is now the time to buy Peloton, or should you be careful about including it in your portfolio? Get the full breakdown from our expert analysts, it’s free.
Why Do We Think Peloton Will Underperform?
We’re cautious about Peloton. Here are three reasons why PTON doesn’t excite us, plus one stock we’d rather own.
1. Decline in Connected Fitness Subscribers Points to Weak Demand
Revenue growth can be broken down into changes in price and volume (for companies like Peloton, our preferred volume metric is connected fitness subscribers). While both are important, the latter is the most critical to analyze because prices have a ceiling.
Peloton’s connected fitness subscribers came in at 2.55 million in the latest quarter, and over the last two years, averaged 5.1% year-on-year declines. This performance was underwhelming and implies there may be increasing competition or market saturation. It also suggests Peloton might have to lower prices or invest in product improvements to grow, factors that can hinder near-term profitability. 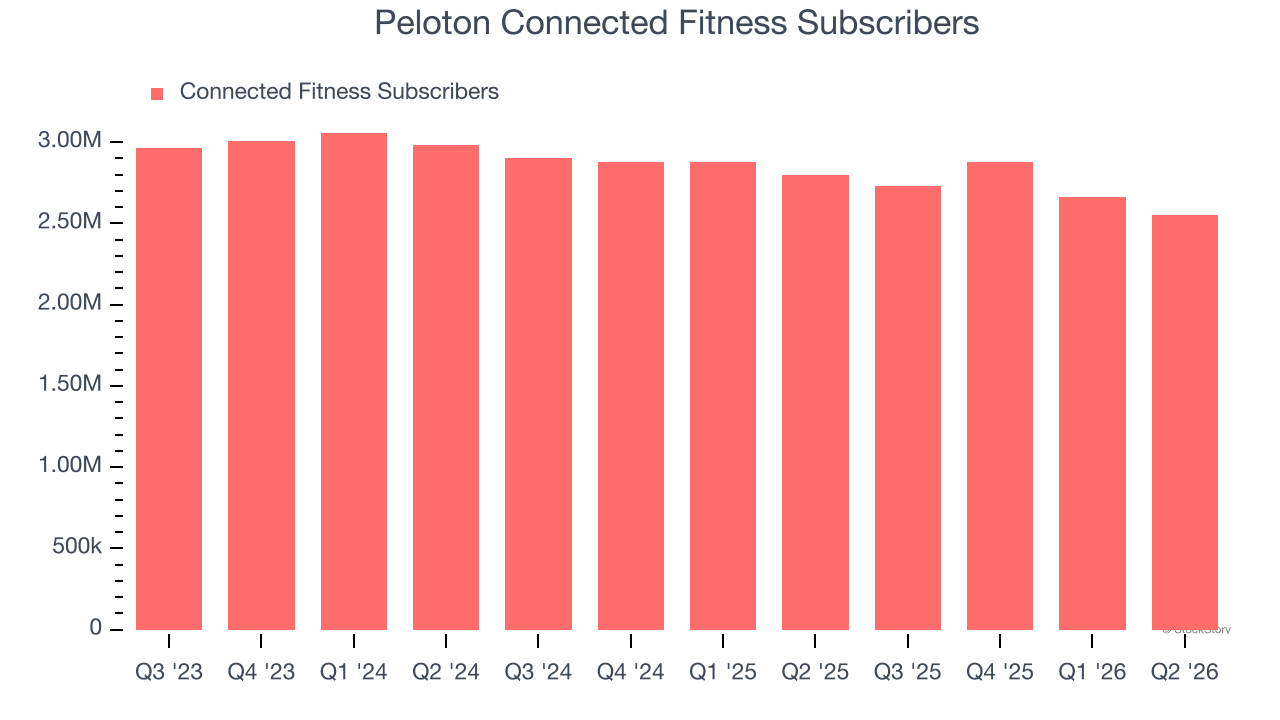
2. Weak Operating Margin Could Cause Trouble
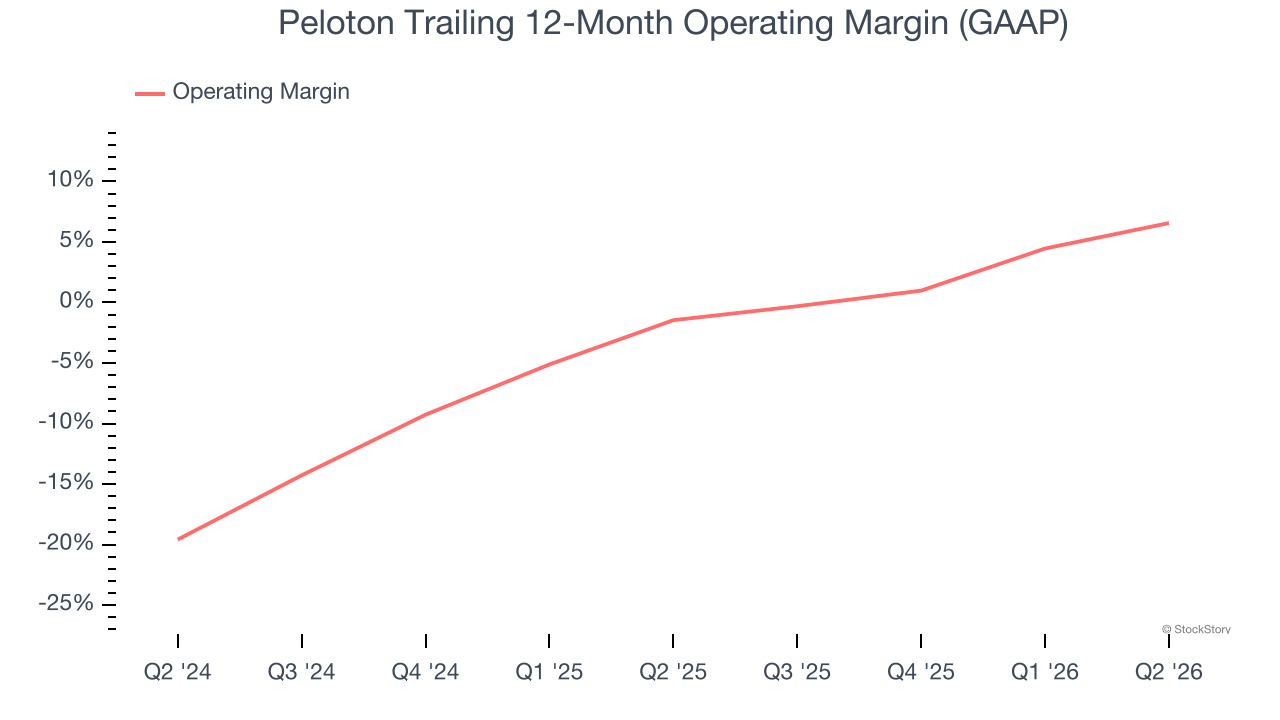
Operating margin is a key measure of profitability. Think of it as net income - the bottom line - excluding the impact of taxes and interest on debt, which are less connected to business fundamentals.
Peloton’s operating margin has risen over the last 12 months and averaged 2.5% over the last two years. The company’s higher efficiency is a breath of fresh air, but its suboptimal cost structure means it still sports inadequate profitability for a consumer discretionary business.
3. Free Cash Flow Projections Disappoint
If you’ve followed StockStory for a while, you know we emphasize free cash flow. Why, you ask? We believe that in the end, cash is king, and you can’t use accounting profits to pay the bills.
Over the next year, analysts’ consensus estimates show they’re expecting Peloton’s free cash flow margin of 15.4% for the last 12 months to remain the same.
Final Judgment
We see the value of companies helping consumers, but in the case of Peloton, we’re out. That said, the stock currently trades at 15.2× forward P/E (or $5 per share). This valuation multiple is fair, but we don’t have much confidence in the company. There are superior stocks to buy right now. We’d recommend looking at a top digital advertising platform riding the creator economy.
Stocks We Like More Than Peloton
WHILE YOU’RE HERE: Top 9 Market-Beating Stocks. The best stocks don’t just beat the market once. They do it again. And again. Robust revenue growth, rising free cash flow, returns on capital that leave their competition in the dust. The market has already rewarded these businesses.
But our AI platform says the party isn’t over. Find out which 9 stocks made the cut this week — FREE. Get Our Top 9 Market-Beating Stocks for Free HERE.
Stocks that have made our list include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-micro-cap company Tecnoglass (+1,552% between June 2020 and June 2025). Find your next big winner with StockStory today.