IT infrastructure services provider Kyndryl (NYSE: KD) met Wall Street’s revenue expectations in calendar Q3 2026 (fiscal Q2 2027), but revenue fell by 1.9% year on year to $3.65 billion. Its non-GAAP profit of $0.42 per share was 10% above analysts’ consensus estimates.
For more on Kyndryl, read our free full research report.
Kyndryl (KD) Q3 CY2026 highlights:
- Revenue $3.65 billion vs S&P analysts’ consensus estimates of $3.65 billion (1.9% year-on-year decline, in line)
- Adjusted EPS $0.42 vs S&P analysts’ consensus estimates of $0.38 (10% beat)
- Adjusted EBITDA $699 million vs analysts’ consensus estimates of $616.5 million (19.1% margin, 13.4% beat)
- Market capitalization $2.82 billion
Revenue growth
Examining a company’s long-term performance can provide clues about its quality. Any business can put up a good quarter or two, but the best consistently grow over the long haul.
With $14.9 billion in revenue over the past 12 months, Kyndryl is a large company in the business services sector and benefits from economies of scale, giving it an edge in distribution. This also gives it more leverage on its fixed costs than smaller competitors and the flexibility to offer lower prices. However, its scale is a double-edged sword because finding new avenues for growth becomes difficult with a substantial market presence. To expand meaningfully, Kyndryl likely needs to adjust its prices, innovate with new offerings or enter new markets.
Kyndryl’s revenue declined by 4.8% per year over the last five years.
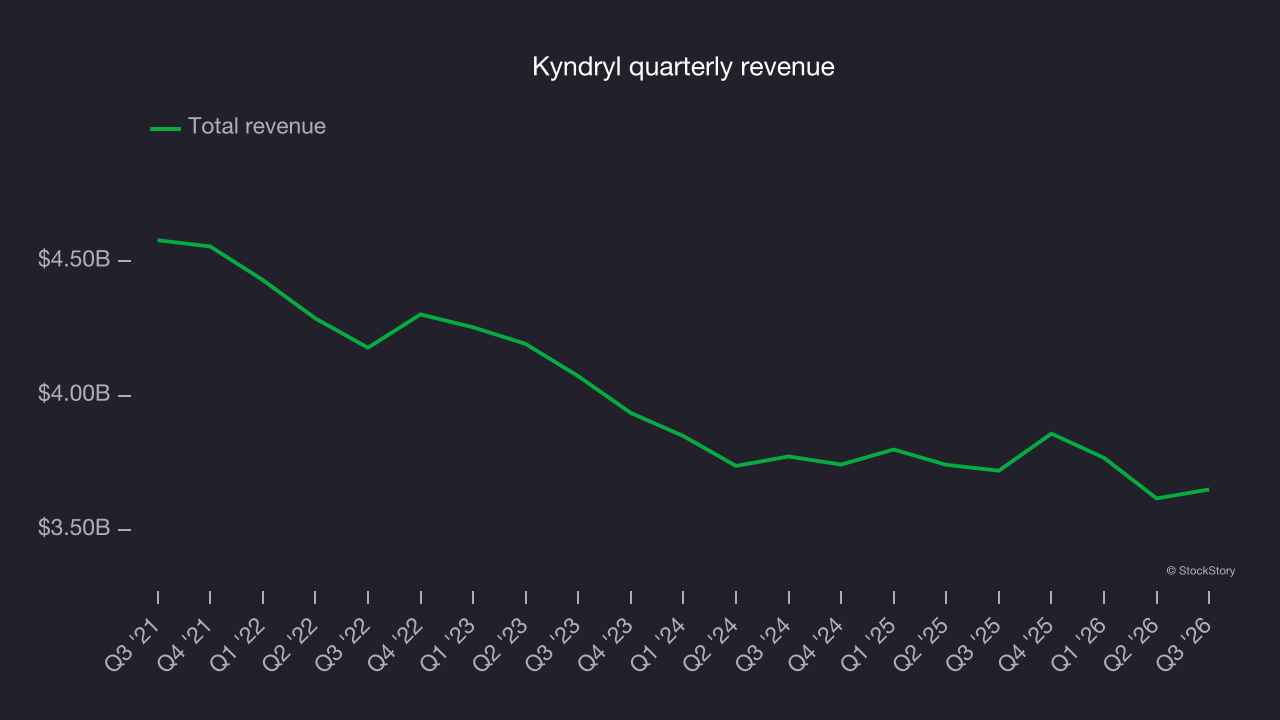
Long-term growth is the most important, but within business services, a half-decade historical view may miss new innovations or demand cycles. Kyndryl’s annualized revenue declines of 1.3% over the last two years suggest its demand continued shrinking.
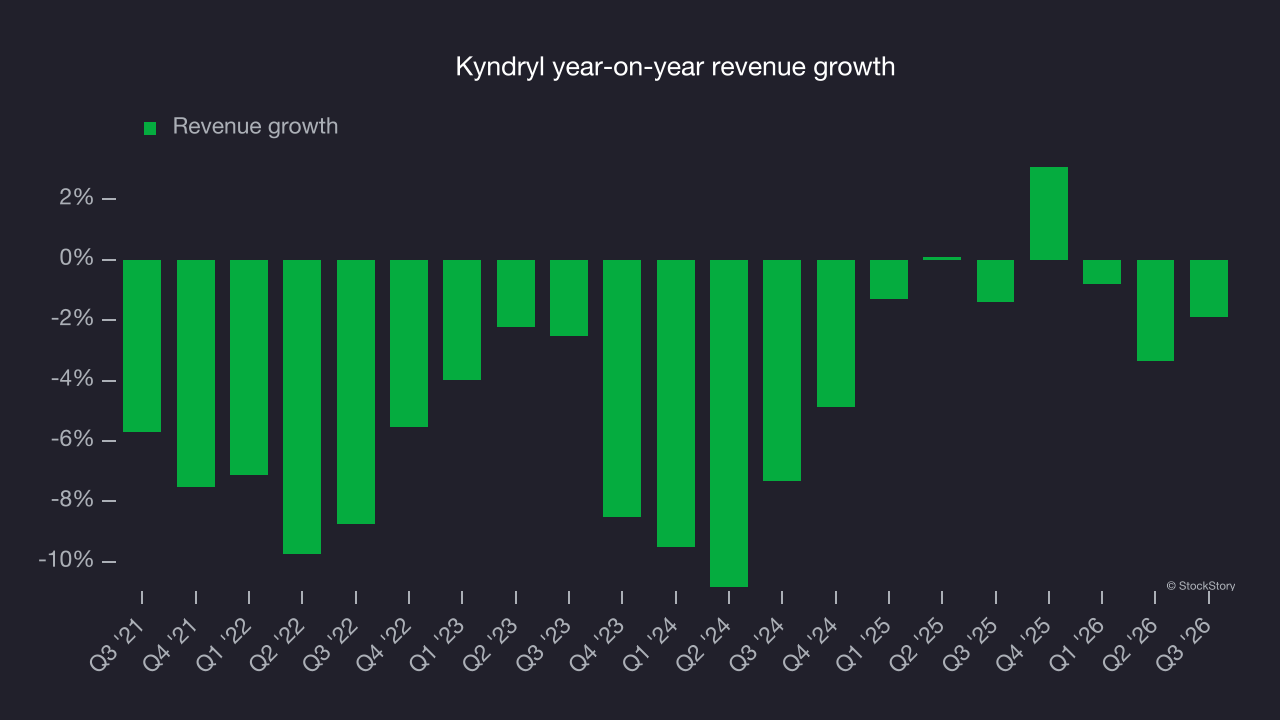
This quarter, Kyndryl reported an uninspiring 1.9% year-on-year revenue decline to $3.65 billion, in line with Wall Street’s consensus estimates.
Looking ahead, sell-side analysts expect revenue to remain flat over the next 12 months, according to S&P. This projection is underwhelming and suggests its newer products and services will not yet improve revenue performance.
Operating margin
Operating margin is a key measure of profitability. Think of it as net income, or the bottom line, excluding the impact of taxes and interest on debt, which are less connected to business fundamentals.
Kyndryl was roughly breakeven when averaging the last five years of quarterly operating profits, one of the worst outcomes in the business services sector.
On the positive side, Kyndryl’s operating margin rose by 9.8 percentage points over the last five years.
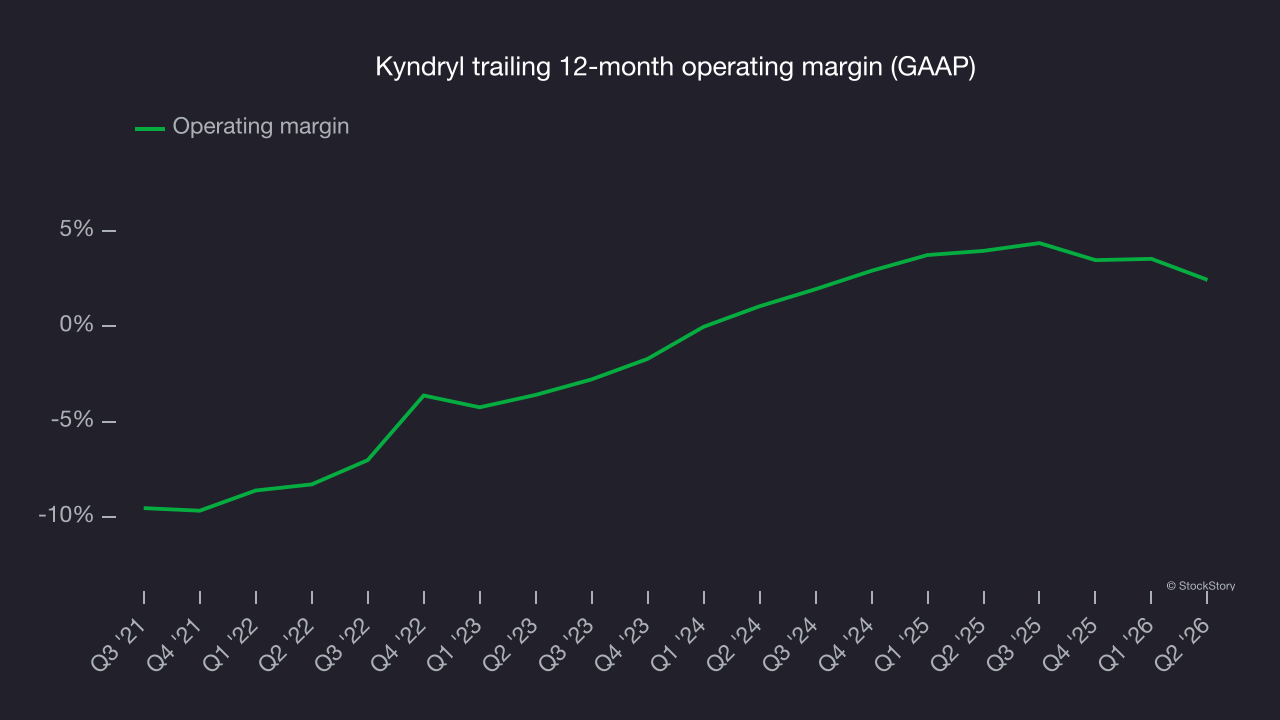
in line with the same quarter last year. This indicates the company’s overall cost structure has been relatively stable.
Earnings per share
We track the long-term change in earnings per share (EPS) for the same reason as long-term revenue growth. Compared to revenue, however, EPS highlights whether a company’s growth is profitable.
Kyndryl’s full-year EPS turned positive over the last four years. This is a positive development and marks a critical point for the business.
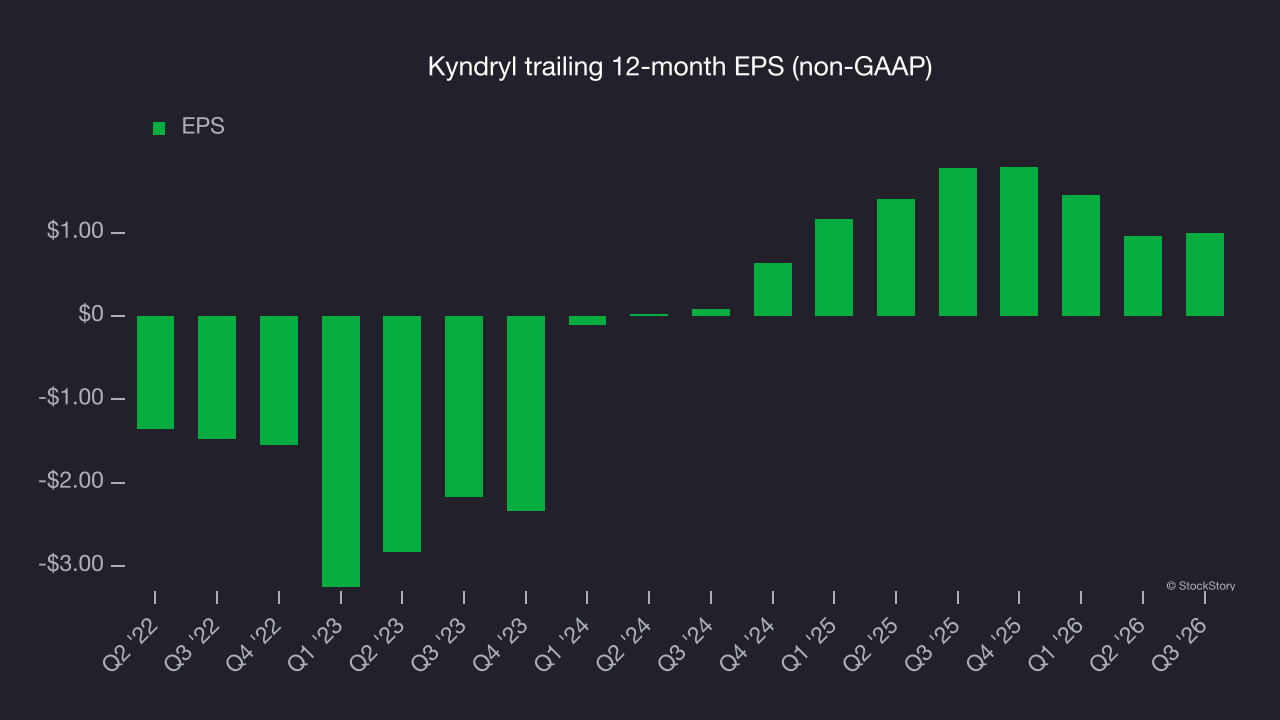
As with revenue, we analyze EPS over a more recent period because it can provide insight into an emerging theme or development for the business.
Kyndryl’s EPS grew at a 254% compounded annual growth rate over the last two years, outpacing its 1.3% annualized revenue declines. This indicates management adapted its cost structure in response to a challenging demand environment.
A closer look at Kyndryl’s earnings helps explain the drivers of its performance. A two-year view shows that Kyndryl has repurchased its stock, shrinking its share count by 5.4%. This indicates its EPS outperformed its revenue not because of increased operational efficiency but financial engineering, as buybacks boost per share earnings.
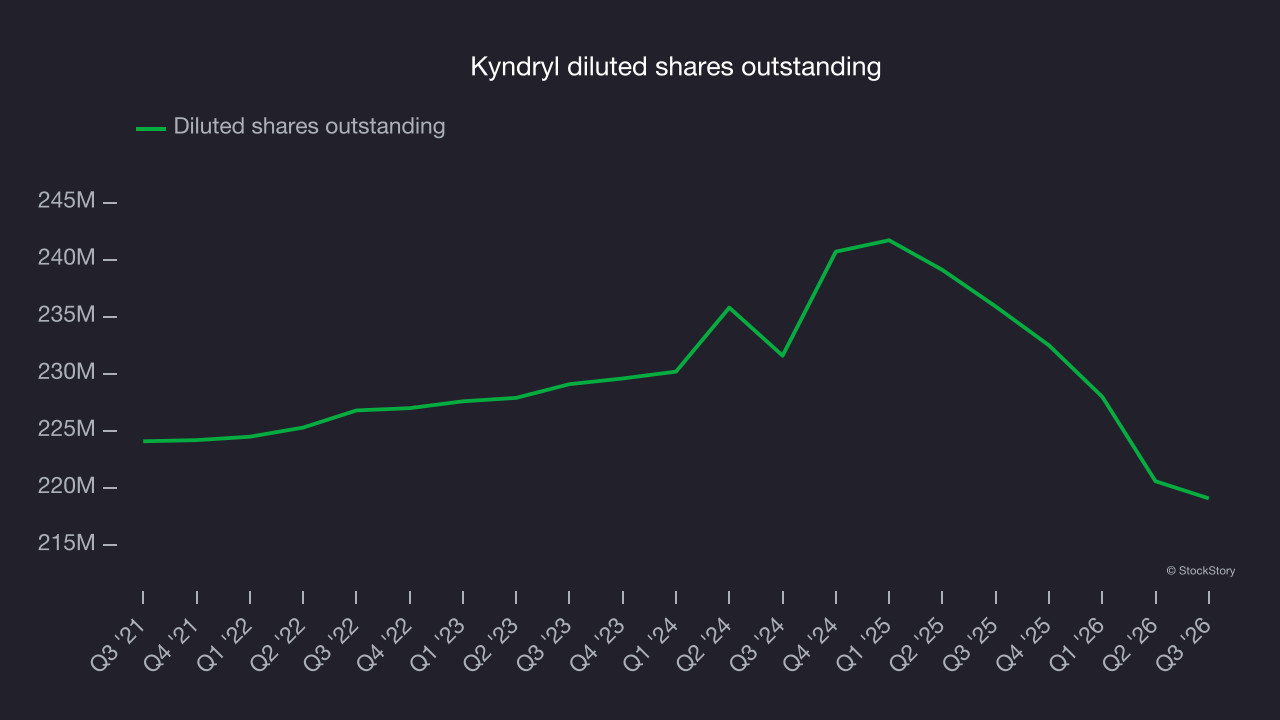
In Q3, Kyndryl reported adjusted EPS of $0.42, up from $0.38 in the same quarter last year. This result beat analysts’ consensus estimates by 10%. Over the next 12 months, Wall Street expects Kyndryl’s full-year EPS to grow 164% from $1 to $2.64, according to S&P.
Key takeaways from Kyndryl’s Q3 results
Kyndryl delivered a decent quarter, with EPS topping analysts’ consensus estimates and some key metrics above expectations. Shares soared 11.2% to $14.39 immediately after the results.
Kyndryl had a solid quarter, but one earnings result doesn’t necessarily make the stock a buy. When making that decision, consider the bigger picture: valuation, business quality and the latest earnings. Read the full research report here (it’s free).