IPG Photonics’s stock price has taken a beating over the past six months, shedding 30.2% of its value and falling to $80.06 per share. This might have investors contemplating their next move.
Is now the time to buy IPG Photonics, or should you be careful about including it in your portfolio? Dive into our full research report to see our analyst team’s opinion, it’s free.
Why Do We Think IPG Photonics Will Underperform?
Even though the stock has become cheaper, we’re passing on IPG Photonics for now. Here are three reasons why there are better opportunities than IPGP, plus one stock we’d rather own.
1. Revenue Spiraling Downwards
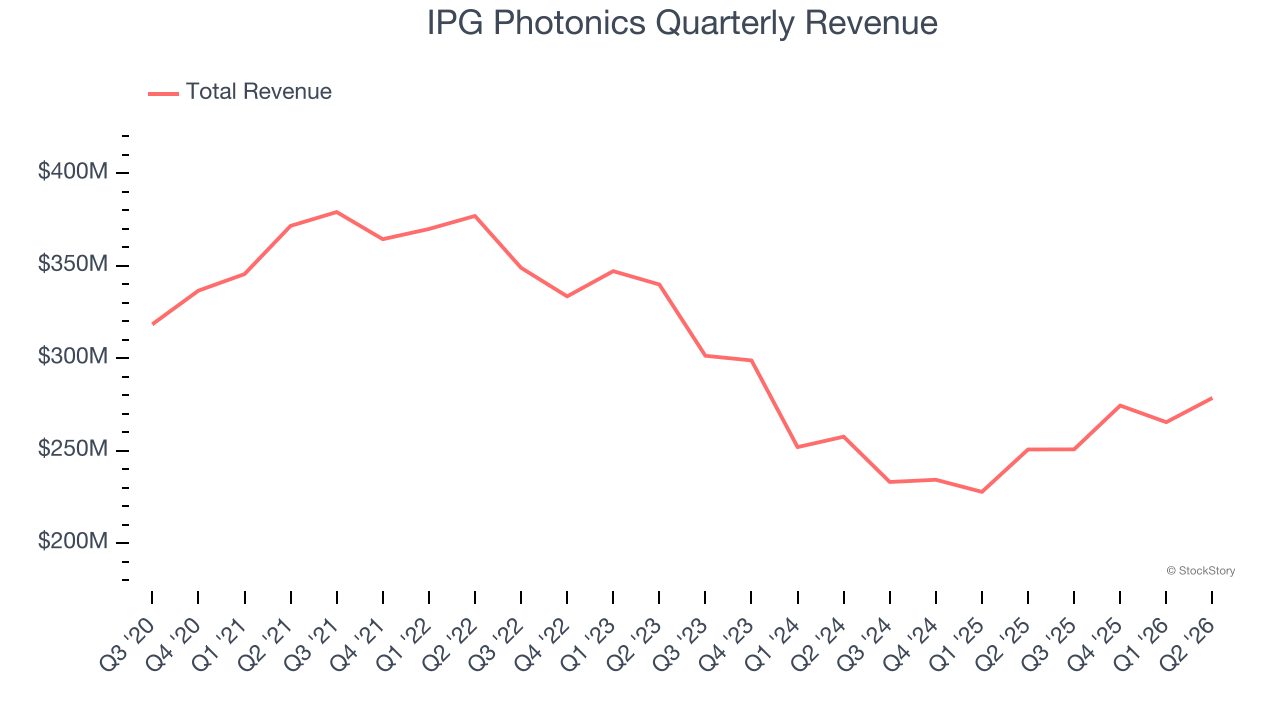
A company’s long-term sales performance is one signal of its overall quality. Any business can put up a good quarter or two, but many enduring ones grow for years. IPG Photonics struggled to consistently generate demand over the last five years as its sales dropped at a 4.9% annual rate. This was below our standards and signals it’s a low quality business. Semiconductors are a cyclical industry, and long-term investors should be prepared for periods of high growth followed by periods of revenue contractions.
2. Shrinking Operating Margin
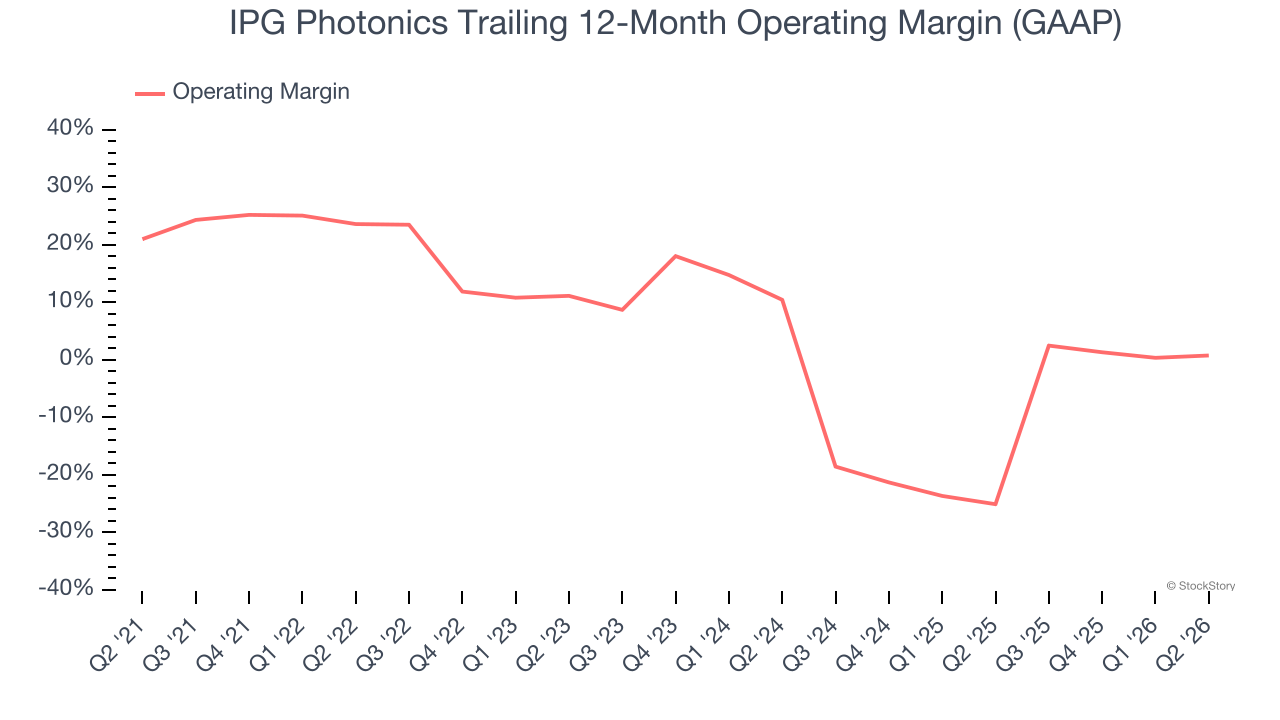
Operating margin is one of the best measures of profitability because it tells us how much money a company takes home after procuring and manufacturing its products, marketing and selling those products, and most importantly, keeping them relevant through research and development.
Looking at the trend in its profitability, IPG Photonics’s operating margin decreased by 22.8 percentage points over the last five years. IPG Photonics’s performance was poor no matter how you look at it - it shows that costs were rising and it couldn’t pass them onto its customers. Its operating margin for the trailing 12 months was breakeven.
3. EPS Trending Down
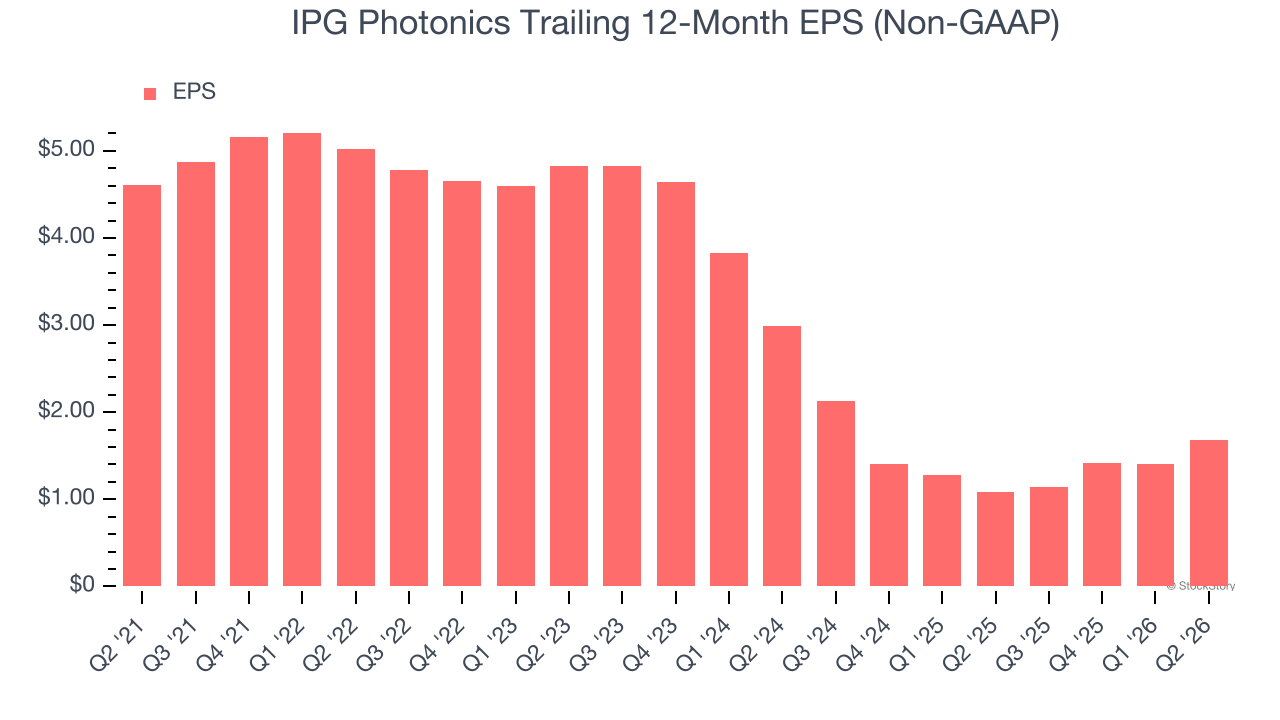
We track the long-term change in earnings per share (EPS) because it highlights whether a company’s growth is profitable.
Sadly for IPG Photonics, its EPS declined by 18.3% annually over the last five years, more than its revenue. This tells us the company struggled because its fixed cost base made it difficult to adjust to shrinking demand.
Final Judgment
We cheer for all companies solving complex technology issues, but in the case of IPG Photonics, we’ll be cheering from the sidelines. After the recent drawdown, the stock trades at 38.3× forward P/E (or $80.06 per share). At this valuation, there’s a lot of good news priced in - we think other companies feature superior fundamentals at the moment. Let us point you toward one of our top digital advertising picks.
Stocks We Like More Than IPG Photonics
ONE MORE THING: Top 5 Growth Stocks. The biggest stock winners almost always had one thing in common before they ran. Revenue growing like crazy. Meta. CrowdStrike. Broadcom. Our AI flagged all three. They returned 315%, 314%, and 455%, respectively.
Find out which 5 stocks it’s flagging this month — FREE. Get Our Top 5 Growth Stocks for Free HERE.
Stocks that have made our list include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-small-cap company Comfort Systems (+1,154% between June 2020 and June 2025). Find your next big winner with StockStory today.