Natural gas producer Expand Energy (NASDAQ: EXE) reported Q3 2026 results beating Wall Street’s revenue expectations, with revenue up 30.6% year on year to $3.29 billion. Its non-GAAP profit of $1.46 per share was 10.8% above analysts’ consensus estimates.
For more on Expand Energy, read the full research report for free.
Expand Energy (EXE) Q3 2026 highlights:
- Revenue $3.29 billion (10.8% year-on-year growth)
- Nat gas, oil, and NGL revenue: $1.88 billion vs S&P analysts’ consensus estimates of $1.80 billion (1.7% year-on-year growth, 4.4% beat)
- Adjusted EPS $1.46 vs S&P analysts’ consensus estimates of $1.32 (10.8% beat)
- Adjusted EBITDA $1.23 billion vs analysts’ consensus estimates of $1.19 billion (37.4% margin, 3.3% beat)
- Operating margin 19.5%, down from 28.8% in the same quarter last year
- Free cash flow margin 10.3%, down from 16.9% in the same quarter last year
- Market capitalization $21.77 billion
“With our diversified scale, investment-grade balance sheet and coast-to-coast customer access, Expand Energy is uniquely positioned to monetize the volatility we see in the gas market today, provide advantaged supply to premium markets and capitalize on the demand growth we expect in the future,” said President and Chief Executive Officer Danny Brown. “Capturing value requires a talented team, disciplined capital allocation and operational excellence. I look forward to working with this team to continue the momentum built and firmly establish Expand Energy as North America’s leading integrated gas company.”
Revenue growth
A company’s long-term performance can give signals about its business quality. Even a bad business, especially in a cyclical industry, can perform well for a year or so, but a top-tier one should exhibit resilience through cycles. Expand Energy’s revenue grew at an impressive 17.9% compounded annual growth rate over the last five years. Its growth surpassed the average energy upstream and integrated energy company and shows its offerings resonate with customers.
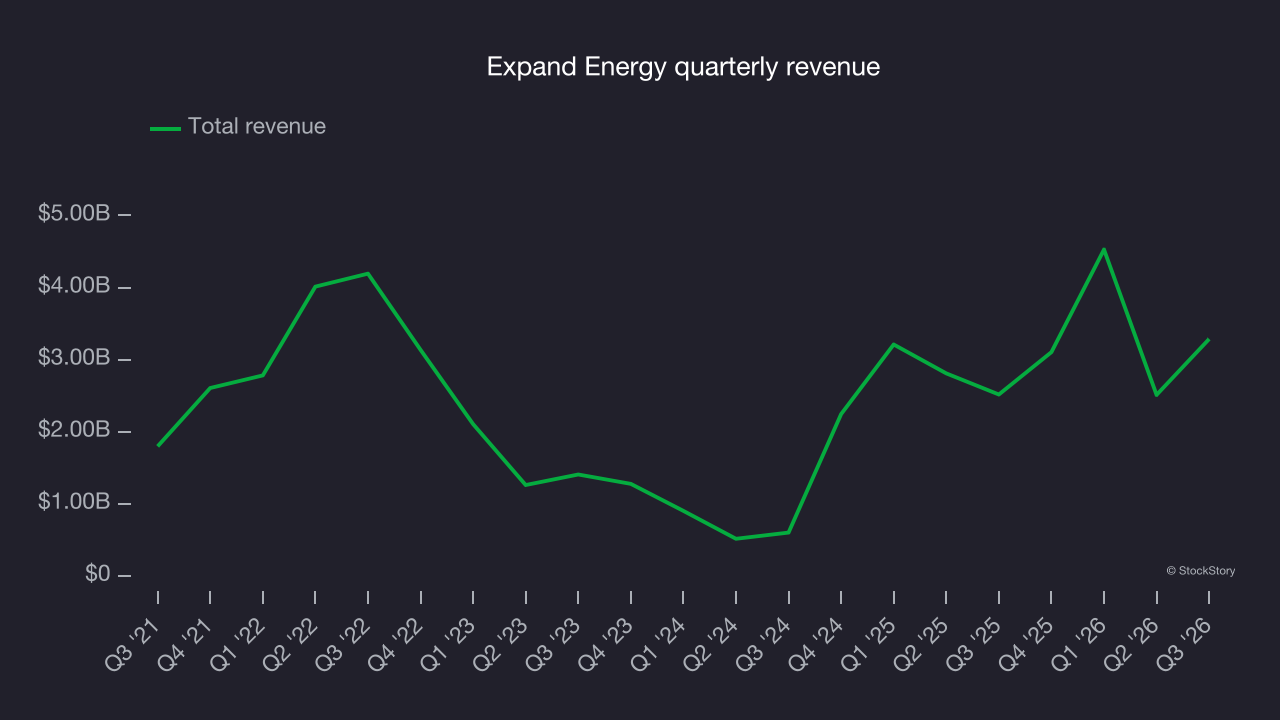
Within energy, a single timeframe, even a long one, only sheds light on how well a company navigated the last commodity cycle. To better assess whether a company compounds through cycles, it helps to take an even longer, ten-year view. Expand Energy’s annualized revenue growth of 4.8% over the last ten years is below its five-year trend, but the results still suggest decent demand.
This quarter, Expand Energy reported strong year-on-year revenue growth of 30.6%, and its $3.29 billion of revenue exceeded Wall Street’s consensus estimates by 82.8%.
Adjusted EBITDA margin
Adjusted EBITDA margin strips out accounting distortions tied to depletion and historical drilling spend, providing a clearer view of the cash-generating power of the underlying asset base before financing and reinvestment decisions.
Expand Energy has been an efficient company over the last five years. It was one of the more profitable businesses in the energy upstream and integrated energy sector, with an average EBITDA margin of 47.3%.
Analyzing the trend in its profitability, Expand Energy’s EBITDA margin rose by 13.4 percentage points over the last year, as its revenue growth provided operating leverage.
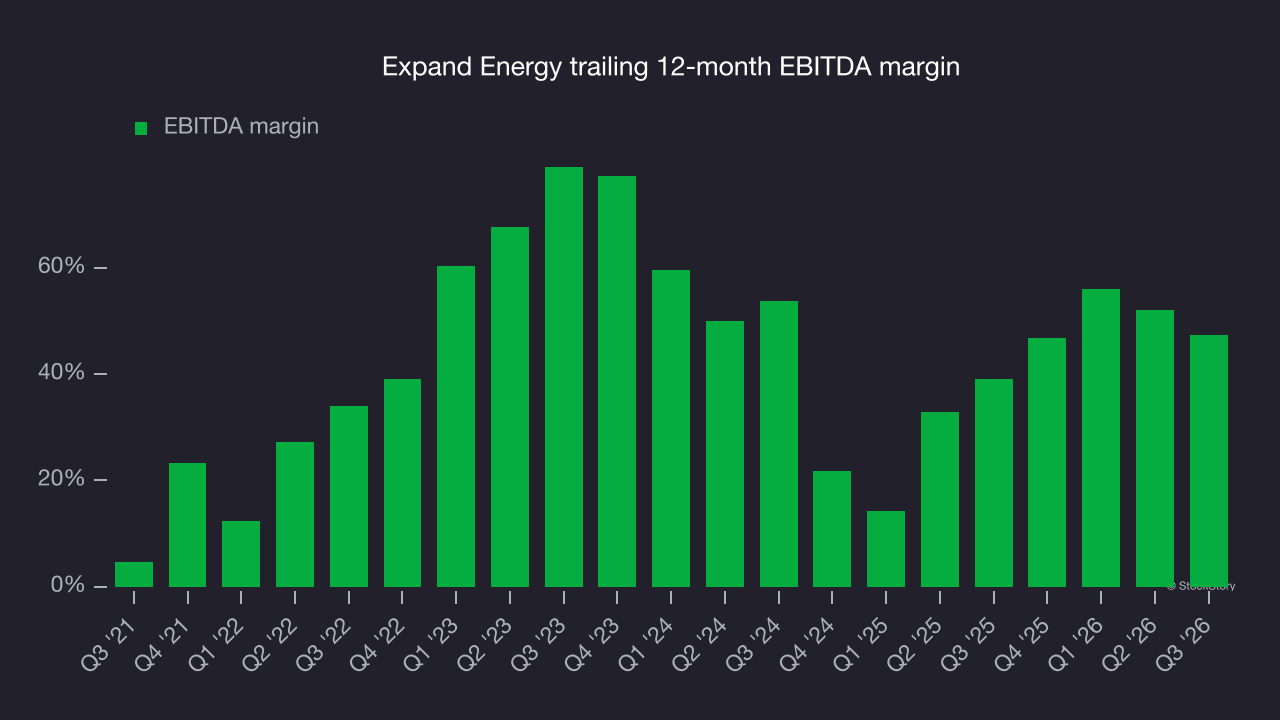
In Q3, Expand Energy generated an EBITDA margin of 37.4%, down 20.9 percentage points year on year. This contraction shows it was less efficient because its expenses grew faster than its revenue. Adjusted EBITDA beat Wall Street’s consensus estimates by 3.3%.
Free cash flow
As mentioned above, adjusted EBITDA ignores capital structure and drilling expenditure decisions. These are two major aspects of an energy producer’s business, so investors need to account for them to get a comprehensive picture of business quality. In other words, adjusted EBITDA margins could be solid but free cash flow abysmal because asset decline rates are high and drilling is expensive. Free cash flow reflects not only the economics of production to date but also the cost of staying in business through further drilling or extraction.
Expand Energy has shown strong cash profitability, giving it an edge over its competitors and the ability to reinvest or return capital to investors. The company’s free cash flow margin averaged 15% over the last five years, an impressive level for an upstream and integrated energy business.
Absolute free cash flow margin levels matter, but so does the stability of free cash flow. All else equal, a 25.0% average free cash flow margin that stays steady regardless of commodity prices is preferable to very high margins when times are good and negative ones when they’re tough.
Expand Energy’s ratio of quarterly free cash flow volatility to WTI crude price volatility over the past five years was 7.4 (lower is better), indicating strong insulation from commodity swings. This indicates that its cash generation is relatively insulated from swings in commodity prices compared with most peers. This resilience supports access to capital in downturns and positions the company to act as a consolidator when distressed assets come to market at attractive prices.
Why assess stability against commodity prices at the free cash flow line? Why not compare revenue or EBITDA to WTI in the case of Expand Energy? Because what ultimately matters is not how much revenue or profit a company earns when prices are high but how much cash it can generate when prices are low. Free cash flow is the superior metric because it includes everything from hedging effectiveness to growth and maintenance capex to management behavior during good times and bad.
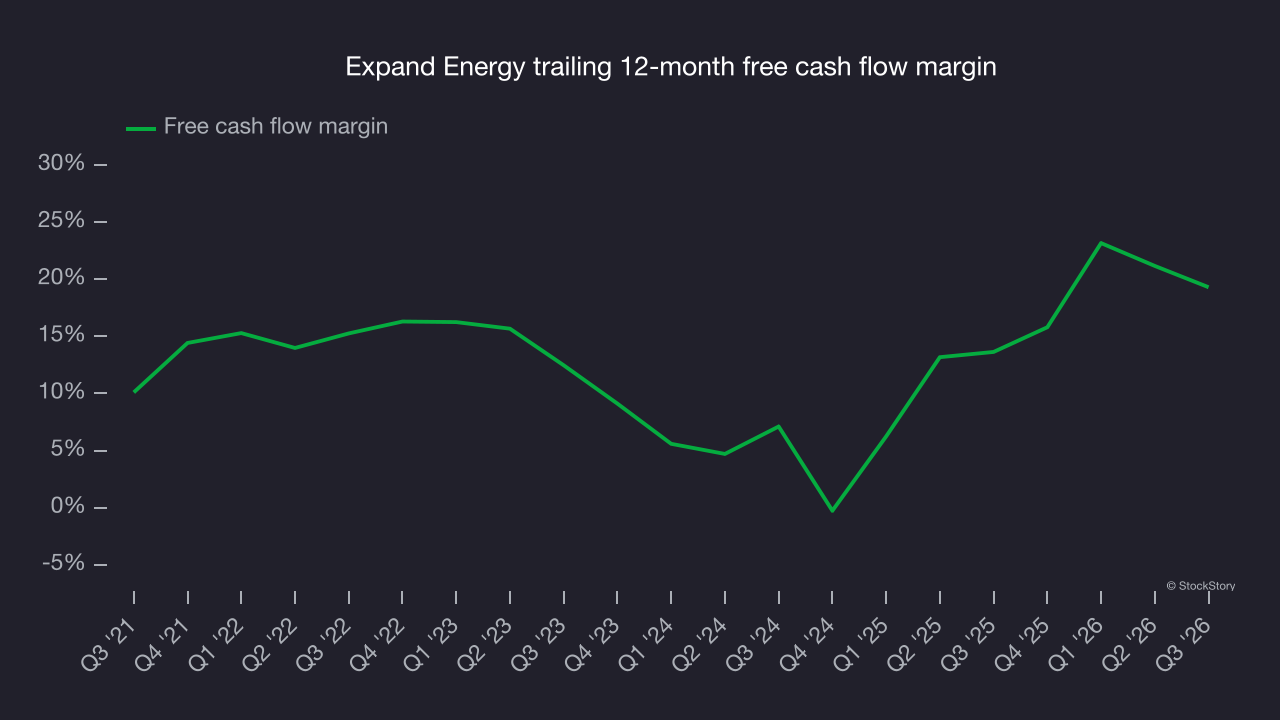
Expand Energy’s free cash flow totaled $339 million in Q3, equivalent to a 10.3% margin. The company’s cash profitability declined by 6.6 percentage points from the same quarter last year, but a single quarter should not be overinterpreted because investment needs can be seasonal, leading to temporary swings. Long-term trends are more important.
Key takeaways from Expand Energy’s Q3 results
Expand Energy delivered a decent quarter, led by revenue that came in well above analysts’ consensus estimates and EPS that also topped Wall Street’s consensus. Shares remained flat at $94.38 immediately after the results.
When evaluating Expand Energy as an investment, it’s important to consider its valuation, business quality and latest quarterly results. For more on Expand Energy, read our full research report here (it’s free).