
Global media and entertainment company iHeartMedia (NASDAQ: IHRT) missed Wall Street’s revenue expectations in Q3 2026 as revenue rose 3.3% year on year to $1.03 billion. Its GAAP loss of $0.06 per share was significantly below analysts’ consensus estimates.
For more on iHeartMedia, read our free full research report.
iHeartMedia (IHRT) Q3 2026 highlights:
- Revenue $1.03 billion vs analysts' consensus estimates of $1.05 billion, according to S&P (3.3% year-on-year growth, 2.2% miss)
- EPS (GAAP) -$0.06 vs analysts' consensus estimates of -$0.03 (significant miss)
- Adjusted EBITDA $170.5 million vs analysts' consensus estimates of $201.1 million (16.6% margin, 15.2% miss)
- EBITDA guidance $575 million at the midpoint for the full year, below analysts' consensus estimates of $776.8 million
- Operating margin 7.1%, up from -11.7% in the same quarter last year
- Free cash flow -$10.39 million compared to -$32.82 million in the same quarter last year
- Market capitalization $327.6 million
Revenue growth
A company’s long-term revenue performance can indicate its overall quality. Any business can deliver a good quarter or two, but many enduring ones grow for years. Over the last five years, iHeartMedia grew its revenue at a weak 3.2% compounded annual growth rate, falling short of the consumer discretionary sector standard.
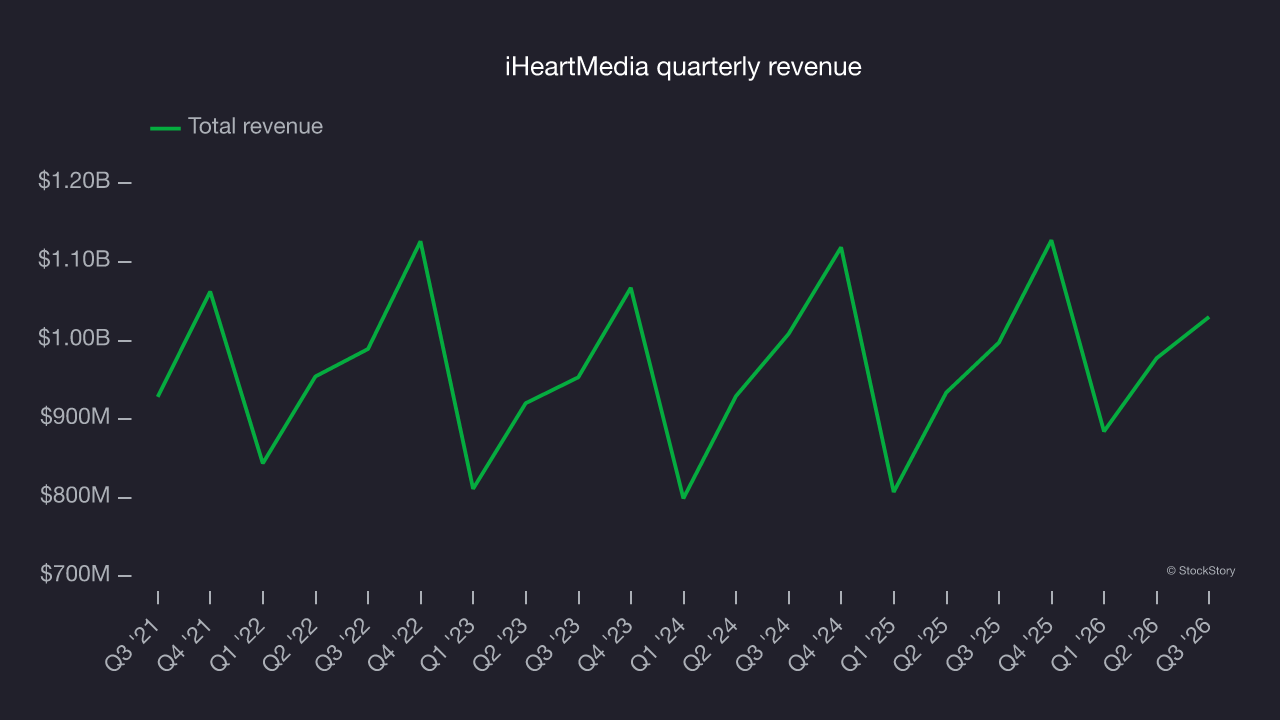
Long-term growth is the most important, but within consumer discretionary, product cycles are short and revenue can be hit-driven due to rapidly changing trends and consumer preferences. iHeartMedia’s annualized revenue growth of 2.8% over the last two years aligns with its five-year trend, suggesting its demand was consistently weak. 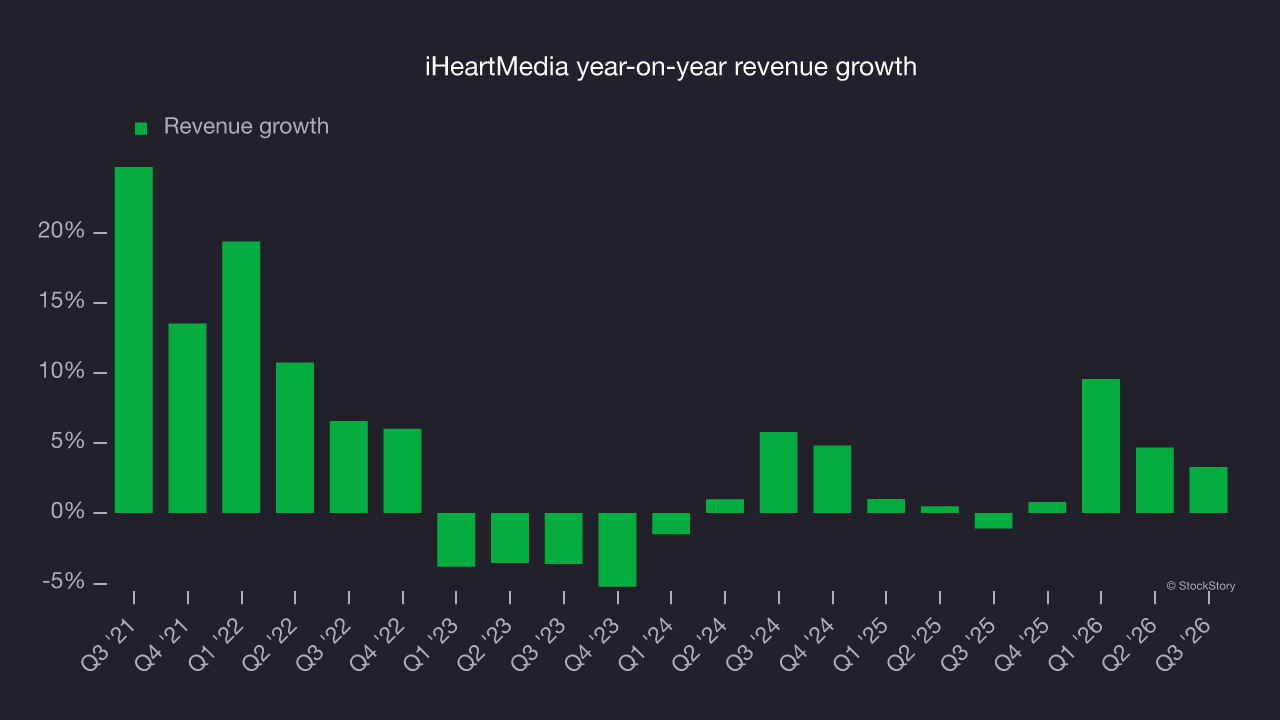
iHeartMedia also breaks out the revenue for its three most important segments: Multiplatform, Digital Audio and Services, which are 54.6%, 37.7% and 7.9% of revenue. Over the last two years, iHeartMedia’s Digital Audio revenue (podcasting) averaged 14.5% year-on-year growth while its Multiplatform (broadcasting, networks and events) and Services (media representation) revenues averaged 2.7% and 1.3% declines. 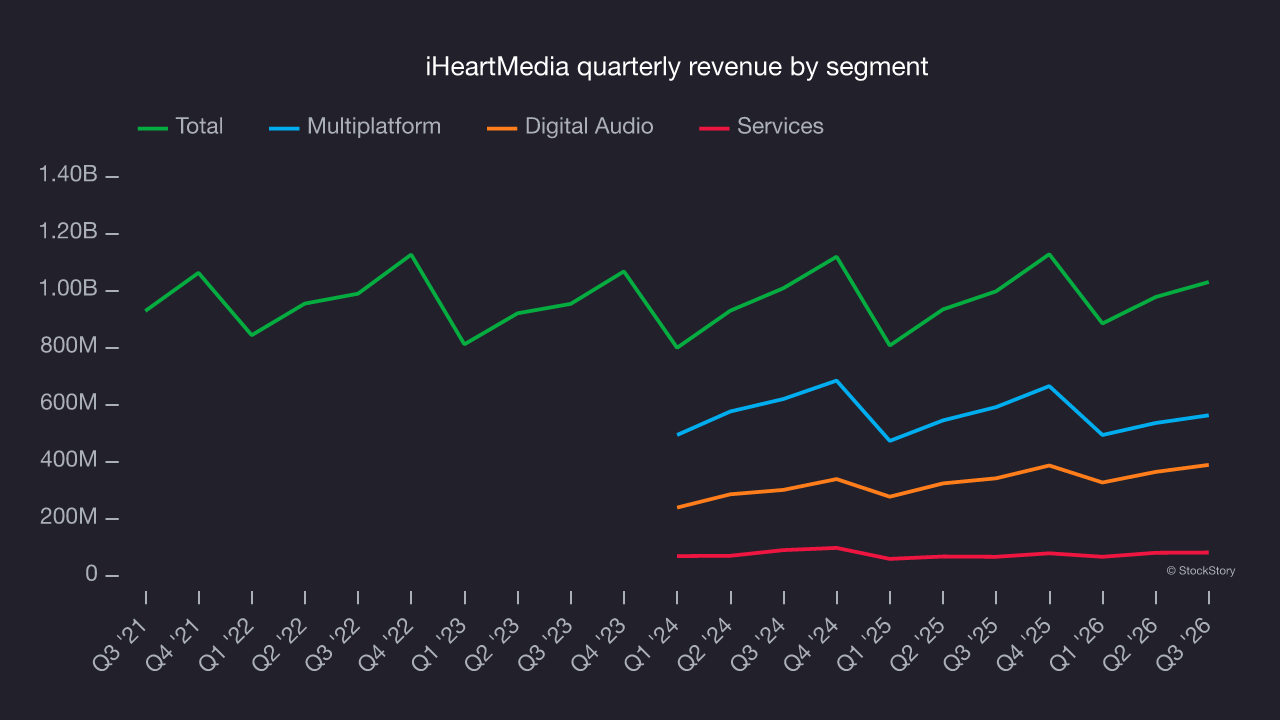
This quarter, iHeartMedia’s revenue grew by 3.3% year on year to $1.03 billion, falling short of Wall Street’s consensus estimates.
Looking ahead, sell-side analysts expect revenue to grow 4.2% over the next 12 months, according to S&P, similar to its two-year rate. While this projection suggests its newer products and services will fuel better top-line performance, it is still below the sector average.
Operating margin
iHeartMedia’s operating margin has risen over the last 12 months and averaged 2.5% over the last two years. The company’s improved efficiency is a positive, but its suboptimal cost structure means profitability remains thin for a consumer discretionary business.
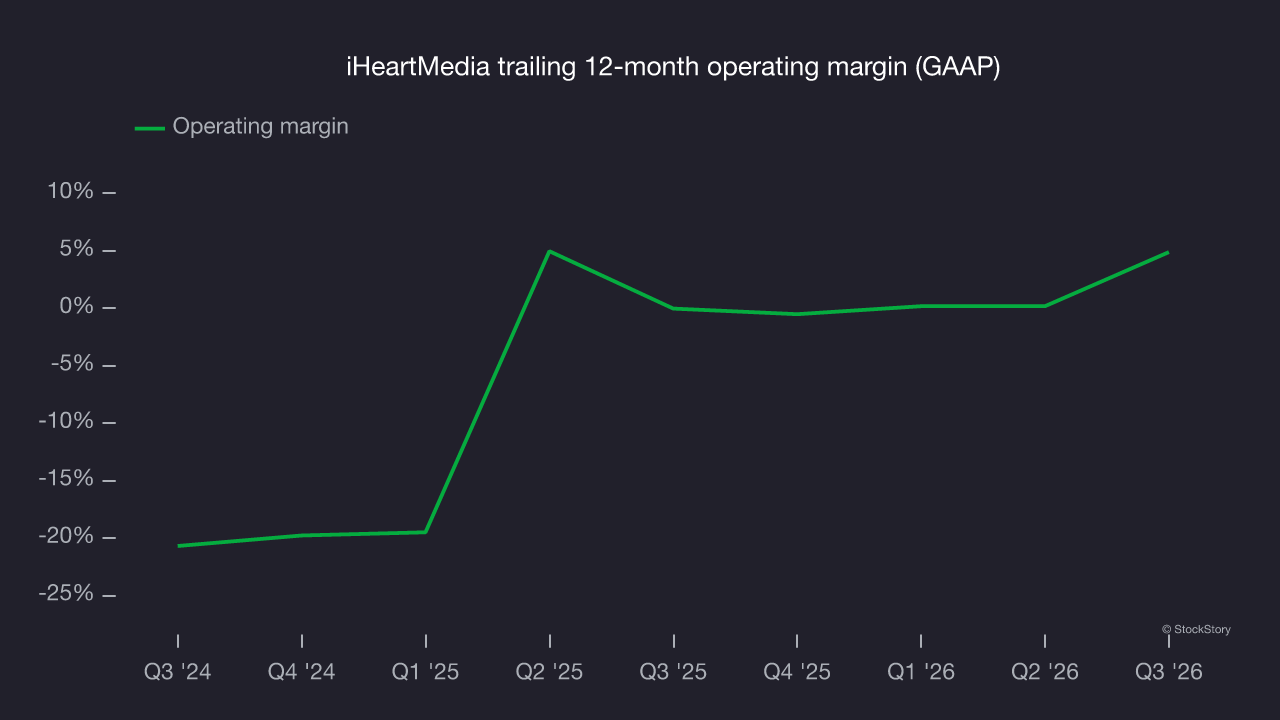
This quarter, iHeartMedia generated an operating profit margin of 7.1%, up 18.8 percentage points year on year. This increase was a positive development and shows it was more efficient.
Earnings per share
Revenue trends explain a company’s historical growth, but the long-term change in earnings per share, or EPS, points to the profitability of that growth. For example, a company could inflate its revenue through excessive spending on advertising and promotions.
Although iHeartMedia’s full-year earnings are still negative, it reduced its losses and improved its EPS by 4.4% annually over the last five years. The next few quarters will be critical for assessing its long-term profitability.
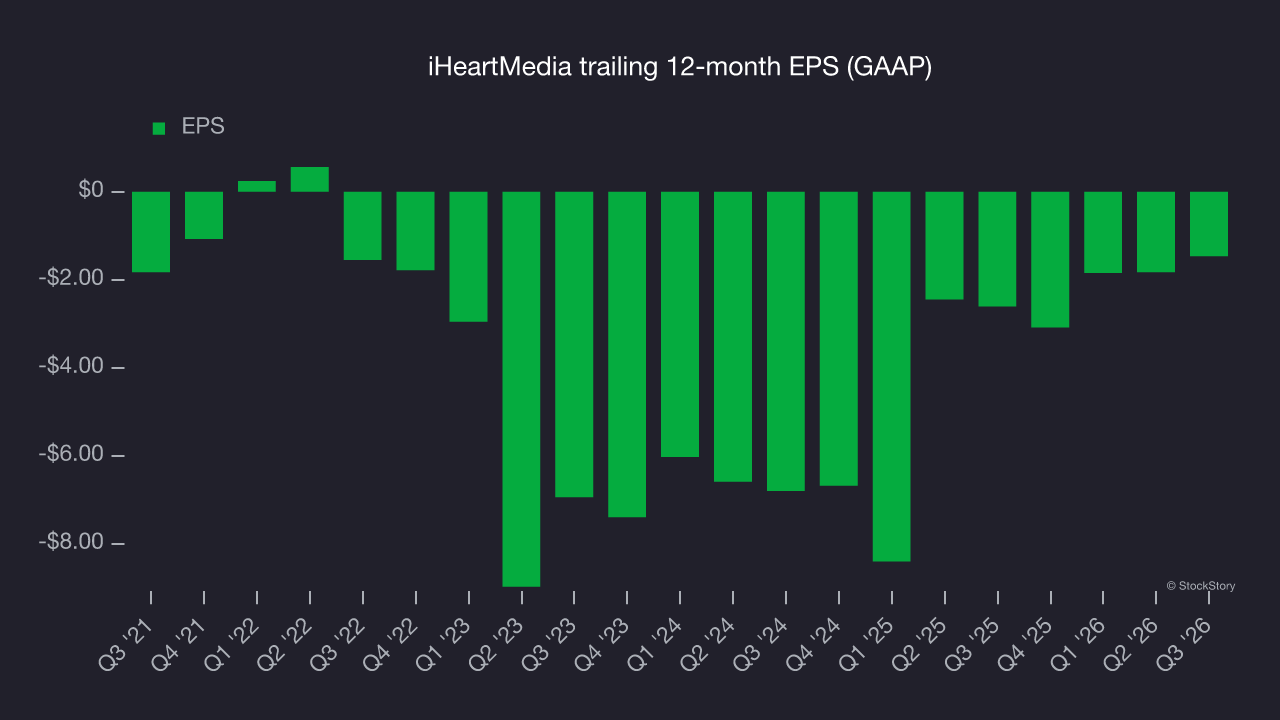
In Q3, iHeartMedia reported EPS of negative $0.06, up from negative $0.43 in the same quarter last year. Despite the year-on-year improvement, EPS missed analysts’ consensus estimates. Over the next 12 months, Wall Street expects iHeartMedia to narrow its losses. Analysts forecast its full-year EPS will improve from negative $1.46 to negative $0.06, according to S&P.
Key takeaways from iHeartMedia’s Q3 results
iHeartMedia’s full-year EBITDA guidance missed expectations, and quarterly EPS fell short of Wall Street’s consensus estimates, leaving few positives in a weak quarter. Shares plunged 36.9% to $1.12 immediately after the results.
iHeartMedia underperformed this quarter, but does that create an investment opportunity at its current price? What happened in the latest quarter matters, but not as much as longer-term business quality and valuation when deciding whether to invest in this stock. Read the full research report for more on iHeartMedia (it’s free).




