As the Q2 earnings season comes to a close, it’s time to take stock of this quarter’s best and worst performers in the defense contractors industry, including Parsons (NYSE: PSN) and its peers.
Defense contractors typically require technical expertise and government clearance. Companies in this sector can also enjoy long-term contracts with government bodies, leading to more predictable revenues. Combined, these factors create high barriers to entry and can lead to limited competition. Lately, geopolitical tensions–whether it be Russia’s invasion of Ukraine or China’s aggression towards Taiwan–highlight the need for defense spending. On the other hand, demand for these products can ebb and flow with defense budgets and even who is president, as different administrations can have vastly different ideas of how to allocate federal funds.
The 14 defense contractors stocks we track reported a very strong Q2. As a group, revenues beat analysts’ consensus estimates by 4% while next quarter’s revenue guidance was 1.1% above.
Amidst this news, share prices of the companies have had a rough stretch. On average, they are down 5.9% since the latest earnings results.
Weakest Q2: Parsons (NYSE: PSN)
Delivering aerospace technology during the Cold War-era, Parsons (NYSE: PSN) offers engineering, construction, and cybersecurity solutions for the infrastructure and defense sectors.
Parsons reported revenues of $1.58 billion, flat year on year. This print fell short of analysts’ expectations by 1.9%. Overall, it was a disappointing quarter for the company with full-year revenue guidance missing analysts’ expectations significantly and full-year EBITDA guidance missing analysts’ expectations significantly.
“Our second quarter results highlight the demand for our solutions and the effectiveness of our strategy in a dynamic macro environment,” said Carey Smith, chair, president, and chief executive officer.
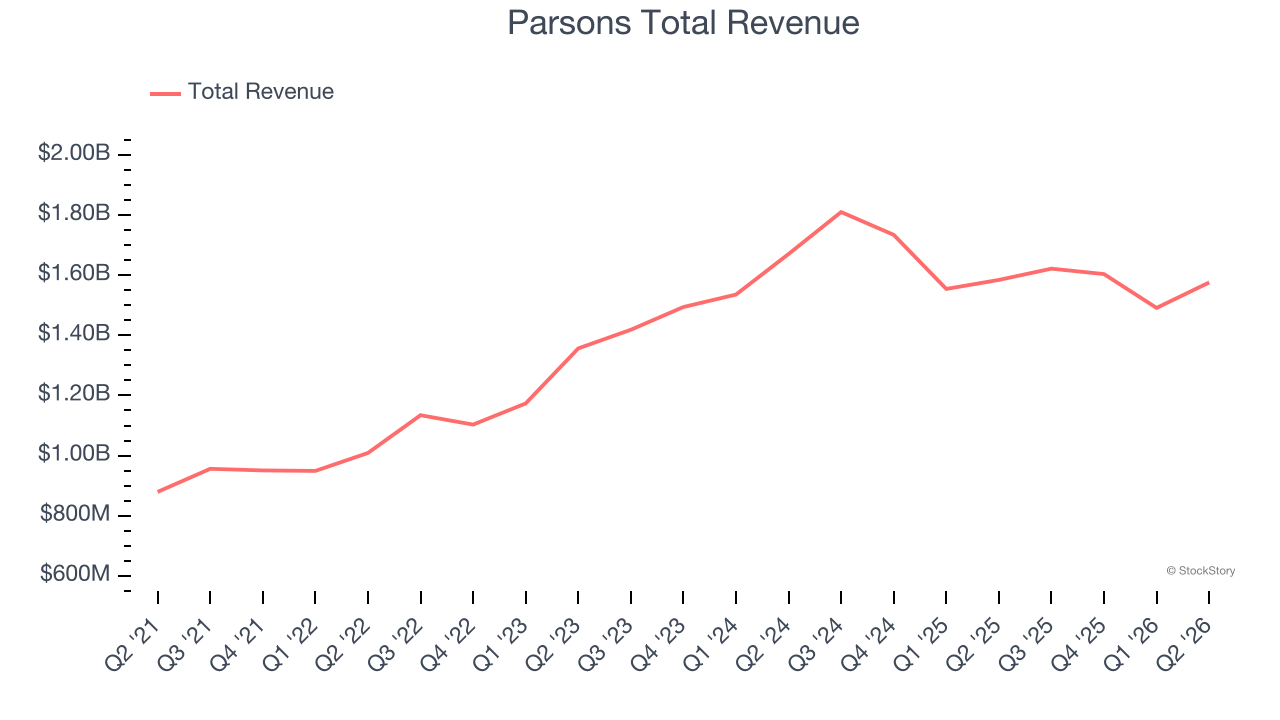
Parsons delivered the weakest performance against analyst estimates, slowest revenue growth, and weakest full-year guidance update of the whole group. The market seems disappointed with the results as the stock is down 29.3% since reporting and currently trades at $43.86.
Read our full report on Parsons here, it’s free.
Best Q2: Huntington Ingalls (NYSE: HII)
Building Nimitz-class aircraft carriers used in active service, Huntington Ingalls (NYSE: HII) develops marine vessels and their mission systems and maintenance services.
Huntington Ingalls reported revenues of $3.42 billion, up 10.9% year on year, outperforming analysts’ expectations by 8.2%. The business had an incredible quarter with a beat of analysts’ EPS estimates.
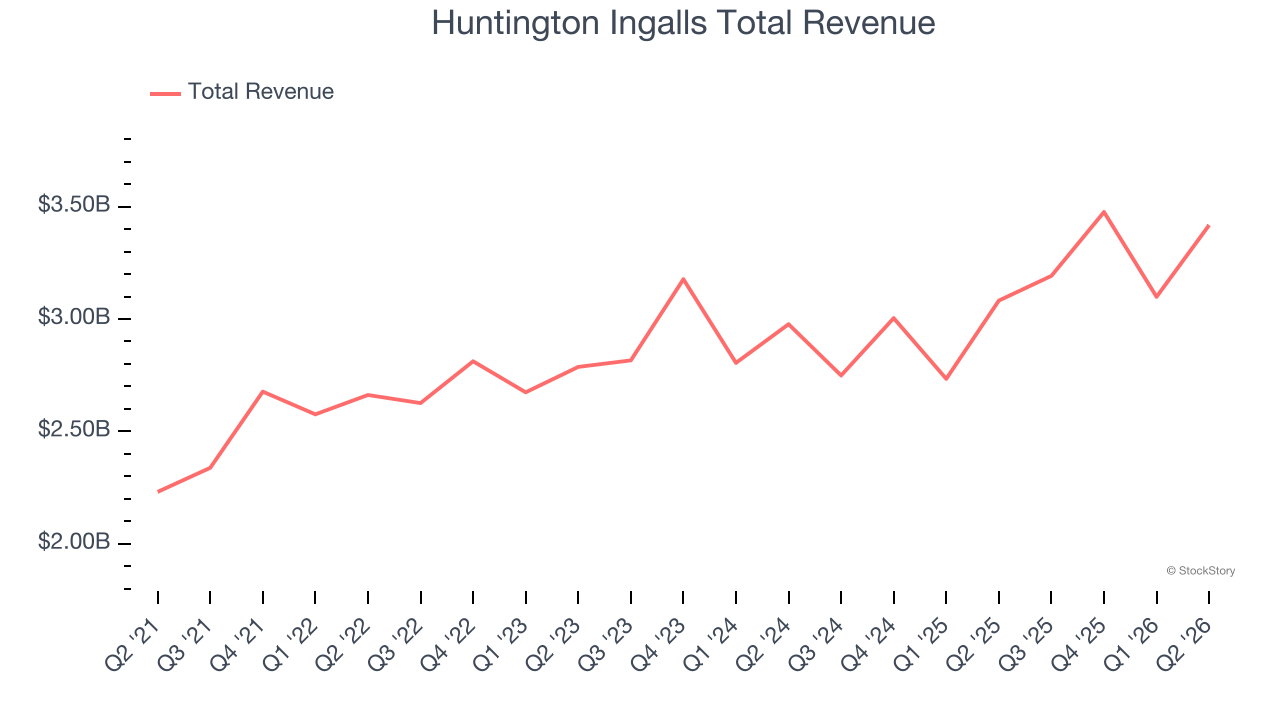
Although it had a fine quarter compared to its peers, the market seems unhappy with the results as the stock is down 4% since reporting. It currently trades at $269.29.
Is now the time to buy Huntington Ingalls? Access our full analysis of the earnings results here, it’s free.
BWX (NYSE: BWXT)
Contributing components and materials to the famous Manhattan Project in the 1940s, BWX (NYSE: BWXT) is a manufacturer and service provider of nuclear components and fuel for government and commercial industries.
BWX reported revenues of $901.6 million, up 18% year on year, in line with analysts’ expectations. Still, its results were good as it locked in full-year EBITDA guidance beating analysts’ expectations and an impressive beat of analysts’ EBITDA estimates.
As expected, the stock is down 18.4% since the results and currently trades at $141.73.
Read our full analysis of BWX’s results here.
Leidos (NYSE: LDOS)
Formed through the split of IT services company SAIC, Leidos (NYSE: LDOS) offers technology and engineering solutions such as military training systems for the defense, civil, and health markets.
Leidos reported revenues of $4.56 billion, up 7.2% year on year. This print topped analysts’ expectations by 2.6%. Overall, it was a very strong quarter as it also recorded an impressive beat of analysts’ EBITDA estimates and a beat of analysts’ EPS estimates.
The stock is up 5% since reporting and currently trades at $124.70.
Read our full, actionable report on Leidos here, it’s free.
Leonardo DRS (NASDAQ: DRS)
Developing submarine detection systems for the U.S. Navy, Leonardo DRS (NASDAQ: DRS) is a provider of defense systems, electronics, and military support services.
Leonardo DRS reported revenues of $913 million, up 10.1% year on year. This number surpassed analysts’ expectations by 0.9%. It was a very strong quarter as it also produced a beat of analysts’ EPS estimates and an impressive beat of analysts’ EBITDA estimates.
The stock is down 19.3% since reporting and currently trades at $37.55.
Read our full, actionable report on Leonardo DRS here, it’s free.
Market Update
Over the past year, investors have been forced to repeatedly answer the same question: what is the market’s biggest risk? The answer has changed several times, and each shift has reshaped market leadership.
Late in 2025 and early 2026, artificial intelligence became the market’s primary uncertainty. Investors questioned whether AI would erode software pricing power and weaken competitive moats as AI made it easier to replicate once-differentiated products.
By the spring, technology took a back seat to geopolitics. The U.S. conflict with Iran briefly became the market’s dominant narrative, raising concerns about oil prices, inflation, and global growth. But as energy markets remained orderly and fears of a prolonged supply disruption faded, investors quickly turned their focus back to fundamentals.
Want to invest in winners with rock-solid fundamentals? Check out our Strong Momentum Stocks and add them to your watchlist. These companies are poised for growth regardless of the political or macroeconomic climate.